Area Real Estate News & Market Trends

You’ll find our blog to be a wealth of information, covering everything from local market statistics and home values to community happenings. That’s because we care about the community and want to help you find your place in it. Please reach out if you have any questions at all. We’d love to talk with you!

April 28, 2026

Central Florida Price Reductions: 1,326 Homes With Price Cuts This Week


This week's numbers: 1,326 homes with active price reductions across Orange, Seminole, Volusia, and Lake counties. Average reduction: 3.55%. Listings sitting 60+ days: 51.4% of the total -- that is where buyers have the most leverage.

1. This Week's Price Reduction Snapshot

Every week, we pull fresh data from the Stellar MLS to track price reductions across four Central Florida counties. Here is where things stand as of April 26, 2026:

Orange County

538 price reductions (-52 from last week)

Average reduction: 3.67%

47.0% listed 60+ days

Browse Orange County

Seminole County

168 price reductions (+6 from last week)

Average reduction: 4.01%

52.4% listed 60+ days

Browse Seminole County

Volusia County

305 price reductions (-21 from last week)

Average reduction: 3.1%

49.2% listed 60+ days

Browse Volusia County

Lake County

315 price reductions (-62 from last week)

Average reduction: 3.44%

57.1% listed 60+ days

Browse Lake County

51.4% of all price-reduced listings have been on the market 60 days or longer. That is the number that matters most for buyers -- it signals sellers who are ready to negotiate on more than just price. Closing cost assistance, rate buydowns, and repair credits are all on the table when DOM climbs past 60.

2. Week-Over-Week Changes

Compared to last week's data:

  • **Orange County** saw 52 fewer listings (likely absorbed by buyers)
  • **Seminole County** added 6 new price reductions
  • **Volusia County** saw 21 fewer listings (likely absorbed by buyers)
  • **Lake County** saw 62 fewer listings (likely absorbed by buyers)

These shifts reflect real buyer and seller activity -- not seasonal estimates. When listing counts drop, it typically means deals are closing. When they rise, new motivated sellers are entering the market.

3. What This Means for Buyers

Leverage is real right now. With 1,326 motivated sellers adjusting prices across four counties, buyers are not competing against the frenzy that defined 2021 and 2022. The data shows room to negotiate -- particularly on listings that have crossed the 60-day mark.

If you are pre-approved, this is the environment where a well-structured offer on a price-reduced listing can land below asking with concessions attached.

4. What This Means for Sellers

Price is a positioning decision, not a concession. The sellers who are closing right now are the ones who adjusted early and strategically. A price reduction does not mean desperation -- it means your listing re-enters buyer search alerts, gets fresh algorithmic exposure, and competes where actual demand exists.

If your listing has been sitting 45+ days without meaningful showing activity, the market is giving you a signal. We can help you read it.

5. What This Means for Investors

Price-reduced listings are where the math works. When a seller has already cut the price, your acquisition cost drops -- and with 51.4% of listings past 60 days, there is room to negotiate further. That improves your cap rate, your cash-on-cash return, and your exit strategy flexibility.

Whether you are looking at buy-and-hold rentals or fix-and-flip candidates, this week's data across 4 counties gives you a clear map of where motivated sellers are concentrated.

Frequently Asked Questions

How many price-reduced homes are available in Central Florida this week?

As of April 26, 2026, there are 1,326 homes with active price reductions across Orange, Seminole, Volusia, and Lake counties, averaging 3.55% off original list prices.

What does a price reduction mean for buyers?

A price reduction signals a motivated seller. Beyond the lower price itself, it often means faster closing timelines, openness to seller concessions, and more room to negotiate repairs or rate buydowns.

How often is this data updated?

We refresh our price reduction data weekly using direct Stellar MLS exports. Each Tuesday, new reductions are added and sold properties are removed within 24 hours of closing.

Which county has the most price reductions right now?

Orange County currently leads with 538 active price reductions, averaging 3.67% off list prices.

Find Your Next Price-Reduced Home

Brenden Rendo and The Homes In Orlando Team track every price cut across Central Florida weekly. Whether you are buying, selling, or investing -- the data tells the story.

407-616-9019

Send Us a Message | Search Homes

April 16, 2026

Home Maintenance Budget Guide: Avoid Unexpected Repair Costs

For first-time homebuyers, the scariest part of owning often isn't the mortgage, it's the moment an ordinary day turns into unexpected home repairs. The core tension is simple: homeownership comes with ongoing home expenses that keep showing up even after move-in, and it's hard to tell which costs are normal and which ones signal trouble. When home maintenance costs feel random, every leak, rattle, or flicker can feel like a financial threat. With steady homeownership budgeting, maintenance becomes a predictable part of the plan.

TLDR:
  • Homeownership costs fall into two buckets (routine upkeep and emergency repairs) and the timing is what catches owners off guard.
  • A common baseline: the typical homeowner spends 1.02% of their home's value annually on maintenance, repair, and upkeep.
  • Inventory every major system (roof, HVAC, water heater, plumbing, appliances) with its install year, then assign each a monthly, seasonal, or annual cadence.
  • Flag aging equipment early (HVAC systems around 15 to 20 years old are a practical alert point) and build a replacement reserve before it fails.
  • Short, scheduled checks on roof, gutters, HVAC filters, the outdoor AC unit, and plumbing prevent small issues from turning into budget-wreckers.

Understanding Home Maintenance Costs

Home maintenance spending falls into two buckets: routine upkeep and emergency fixes. Routine costs are the small, planned items that keep systems running, while emergency repairs are the sudden failures that demand cash fast. The tricky part is timing, because every major system has a lifecycle, and several can reach "replacement age" around the same period.

This matters because maintenance doesn't hit your budget evenly. According to Bankrate's Hidden Costs of Homeownership Study, the average single-family homeowner now spends about $1,783 a month (roughly $21,400 a year) on hidden costs like maintenance, repairs, property taxes, insurance, and utilities. A steady set-aside helps you stay calm when something breaks and avoid using high-interest debt.

Think of your home like a car with overlapping service intervals. Filters are predictable, but a dead water heater is not, even if it was always going to happen. With the cost types clear, you can start estimating, scheduling, and projecting annual upkeep by system age.

Build a Realistic Home Maintenance Budget Plan

A simple system-by-system plan keeps routine upkeep predictable and makes surprise repairs less financially stressful. Use the steps below to estimate costs, schedule key tasks, and project what you will likely spend this year based on your home's age and major equipment.

  1. Set a baseline annual maintenance number
    Start with a rough target so you are not guessing from zero. Many budgets use a home value percentage as a starting point, and the typical homeowner spends 1.02% of their home's value annually on maintenance, repair, and upkeep. Treat this as a baseline to adjust up for older homes or down for newer, recently updated homes.

  2. Inventory your home systems and their ages
    Write down the install year or approximate age of your roof, HVAC, water heater, plumbing fixtures, appliances, and exterior items like paint and gutters. This turns "random problems" into a clear list of parts with timelines. If you are unsure, check inspection reports, permit history, model tags, or ask the prior owner.

  3. Turn the inventory into a upkeep calendar
    Assign each item a simple cadence: monthly (like HVAC filters), seasonal (like gutter cleaning), and annual (like servicing). Put tasks on your phone calendar and include a realistic cost range next to each one, even if it is just "$20 to $50." A calendar reduces the odds you skip small jobs that later trigger bigger failures.

  4. Add a replacement reserve for aging equipment
    Flag systems nearing end-of-life and start saving ahead of time, even if they still work today. The 15 to 20 years old range is a practical alert point for many HVAC system components, so you can begin building a cushion for repair spikes or replacement. Do the same for other big-ticket items based on their age, condition, and any warning signs.

  5. Build your annual projection and monthly set-aside
    Add your scheduled upkeep costs plus your replacement reserve to create one yearly total, then divide by 12 for a steady monthly transfer into a dedicated maintenance fund. Review the plan every 6 months and after any repair, then adjust categories that came in higher or lower than expected. This keeps your budget tied to real spending, not wishful thinking.

Prevent Big Repairs: Roof, HVAC, and Plumbing Mini-Checklist

Catching small problems early is one of the cheapest "repairs" you can make. Use the same calendar you built for your maintenance budget plan and plug these mini-checks into it so you're funding prevention, not panicking over emergencies.

  1. Do a roof walk-around every month (and after big storms): From the ground, look for missing/curled shingles, sagging spots along the roofline, and granules piling up in gutters or downspout outlets. Use binoculars, don't climb unless you're trained and conditions are dry. If you spot a new stain on a ceiling or damp insulation in the attic, treat it as urgent; small leaks often become expensive repairs quickly.

  2. Keep gutters and downspouts moving water away, fast: Clean gutters at least twice a year, then test them with a hose for proper flow. Confirm downspouts discharge 4-6 feet away from the foundation (extensions are an inexpensive fix) and that splash blocks aren't buried. This single habit reduces roof-edge rot, basement moisture, and siding damage, three common "mystery costs" that can wreck a maintenance budget.

  3. Seal roof penetrations and sun-exposed surfaces before they fail: Once or twice a year, check flashing and sealant around vents, chimneys, and skylights for cracks or gaps. If your roof gets intense sun exposure, consider a reflective option, some homeowners add an additional roof coating on compatible roof types to help reduce UV wear. When you budget, treat sealant, small flashing repairs, and coating touch-ups as planned line items, not surprises.

  4. Use a simple HVAC routine: filter, drain, and airflow check: Replace or clean filters on a set schedule (many homes land in the 1-3 month range depending on pets, dust, and allergies), and keep supply/return vents unblocked by furniture or rugs. During the cooling season, inspect the condensate drain line and pan for standing water, algae, or rust, early signs of a clog that can cause water damage. A checklist approach helps you identify and address small issues before they become breakdowns.

  5. Give the outdoor AC unit breathing room and a gentle clean: Clear leaves and weeds in a 2-foot radius, and keep shrubs trimmed back so the coil can shed heat properly. With the power off, rinse the fins gently from the inside out using a garden hose (no pressure washer), then straighten lightly bent fins with a fin comb if needed. Better airflow means less strain, which can extend equipment life and keep energy costs steadier.

  6. Run a quarterly plumbing "leak and pressure" sweep: Check under every sink, behind toilets, around the water heater, and near the washing machine for drips, corrosion, or soft/swollen cabinet floors. Note how quickly hot water arrives at fixtures and watch for new hammering/banging noises, both can hint at pressure or valve issues worth addressing early. If you have a water meter, do a quick "all water off" test for 30-60 minutes; any movement can signal a hidden leak that deserves follow-up.

A proactive home repair mindset works best when you document what you found, what you fixed, and what you're watching, those notes turn into clearer estimates, fewer repeat problems, and a budget that matches your home's real needs.

Home Maintenance Budget Questions, Answered

How can I accurately estimate annual home maintenance costs before buying a house?

Ask for the home's age and service history, then build a starter list by system: roof, HVAC, plumbing, electrical, appliances, exterior, and drainage. During inspection, request rough replacement timelines and 2 to 3 quotes for any flagged items so you can turn "maybe" into a dollar range. Put every quote into a one-page yearly categories list so you can see the likely annual total at a glance.

What are the key home systems I should budget for to avoid unexpected repair expenses?

Prioritize the big-ticket essentials that can cascade into damage: roof, HVAC, water heater, plumbing leaks, electrical panel, and foundation drainage. Add a small line for routine materials like filters, sealants, and caulk because home maintenance saves by preventing emergency calls.

How do I create a realistic maintenance budget that fits my financial situation?

Start with what you can comfortably auto-save monthly, then split it into "routine upkeep" and "future replacements." A running log helps you track every spend and spot patterns because tracking expenses is essential for avoiding cash crunches. Adjust quarterly based on real receipts, not guesses.

What are some practical tips for staying on top of routine home upkeep without feeling overwhelmed?

Keep tasks small and scheduled: one short check per week beats a massive weekend scramble. Use a home maintenance checklist to keep your home in good working order, then copy only the items that match your house into your calendar. Store photos and notes in the same place as your receipts so nothing gets lost.

How can a home warranty or service plan help me manage maintenance and repair costs after purchasing a home?

It can make some costs more predictable by shifting certain covered breakdowns into a known fee structure. Still, you should budget separately for exclusions, wear-and-tear items, and anything not covered, then keep a yearly categories list so you know what you truly spend. For faster budgeting, you can copy numbers from PDF quotes using a spreadsheet import or OCR tool, and paste them into your log.

What Central Florida Homes Need (That National Guides Miss)

Generic maintenance budgets miss a few realities of owning in Orange, Seminole, Volusia, or Lake County. Florida heat, humidity, hurricane season, and the state's tightening insurance market all shift which line items deserve more attention (and more dollars) in your annual plan.

  1. Plan two roof checks a year, plus one after every named storm: Florida's UV exposure ages shingles faster than national averages, and insurance carriers (including Citizens) are increasingly tying coverage decisions to roof age and condition. If your roof is 12+ years old, get a wind-mitigation inspection and a written condition report on file. Many Orange County homes built in the early 2010s are hitting that replacement window now.

  2. Treat the AC like a primary system, not an appliance: A Central Florida HVAC runs 8-9 months a year versus 4-5 in cooler states, so the 15-20 year alert window from national guides should be tightened to 12-15 years here. Schedule two service visits annually (spring tune-up, fall coil clean), and start a replacement reserve sooner than the box in step 4 above suggests. In Seminole County, where many homes were built in the late 1990s, AC system age is one of the top three issues that show up on inspection.

  3. Watch for humidity damage that doesn't show up nationally: Soft fascia, attic mold, slow plumbing leaks, and bathroom caulk failure all run faster in Florida humidity. Add quarterly bathroom and laundry-room caulk checks to the plumbing sweep in the previous section, and inspect attic insulation annually for water staining. A dehumidifier or mini-split combo in a converted garage or sunroom is often a smart spend.

  4. Budget for water heater replacement on a tighter cycle: Some Central Florida zip codes have hard water that shortens water heater life by 20-30%. If you're on well water (more common in parts of Lake County and rural Volusia), flush the tank annually and budget replacement at year 8-10 instead of year 12.

  5. Hurricane prep is a budget line, not a one-time event: Plywood, hurricane straps, generator fuel, tree trimming, and impact-resistant garage door upgrades all belong on the annual list. Many homeowners discover during their first storm that prep costs more than they budgeted because they're competing with everyone else in the region for the same supplies and contractors. Lock in pre-season service appointments and replace generator fuel additives every six months.

Building a Steady Home Maintenance Budget for Fewer Surprises

Homeownership gets stressful when routine wear turns into urgent repairs, and the cost is never convenient. A proactive maintenance mindset, backed by simple tracking and long-term home care planning, protects a home investment instead of constantly reacting to problems. When small costs are expected and organized, decisions get calmer and peace of mind in homeownership becomes the norm, not a lucky break. Proactive maintenance turns surprise repairs into planned expenses. Start today by opening a dedicated maintenance fund or scheduling the key annual checkups that fit the home's age and systems. That steady habit offers real support for homebuyers and builds resilience for whatever the house needs next.

Thinking about buying your first home in Central Florida?

A realistic maintenance budget starts with knowing what you're buying. I'll walk you through the inspection report, flag the system ages that matter most, and help you plan the first year of ownership before you close.

Visit homesinorlando.forsale or call 407-616-9019 to talk with Brenden Rendo.

Posted in Topic Of Interest
April 5, 2026

Orlando Housing Market: Rates Spike, Builders Slashed $134K

Orlando Housing Market Alert: International Conflict Spikes Rates, While Builders Slash Prices by $134K

April 5, 2026

Key Episode Takeaways

  • The Iran Effect: International conflict has spiked the 10-year Treasury, pushing Orlando mortgage rates back up over 6.5%.
  • Builder Desperation: Taylor Morrison, Lennar, and Pulte are engaged in a price war, with some St. Cloud homes slashed by an astounding $134,000.
  • Stale Resale Market: Over 50% of resale listings in Greater Orlando have been active for more than 60 days.
  • 3.99% Rates Exist: Builders are using aggressive FHA rate buy-downs to move sitting inventory, beating resale financing by 2.5 points.

Uncertainty Returns: How Global Conflict Drove Up Orlando Interest Rates

Welcome to this solo edition of the Orlando Real Estate Buzz. Brendan Rendo here, with Joe out sick. This week, we have to address the major shift that just hit the market. While we all want lower rates, uncertainty is the enemy, and we just got hit with an absolute "bomb."

Before the conflict in Iran began, the market was finding its footing. The 10-year Treasury had dropped to 3.99, and we actually saw mortgage rates dip below 6% for a short time. Heading into the spring selling season, everyone was feeling motivated. Showings were up, and transactions were picking up here in Orlando.

But since the start of the conflict, the 10-year has been on a steady climb, peaking around 4.41. That uncertainty has pushed mortgage rates back over 6.5%, settling around 6.45% today.

"Uncertainty is the worst thing in the world for the housing market. And that’s really what we have right now."

It’s not just rates hurting budgets. Oil prices and the cost of gasoline at the pump are rippling through the economy. Here in Orlando, we are seeing gasoline jump from recent lows of $2.97 up to nearly $4.30. That brings the inflation threat back, and the Fed is likely to remain steady rather than offering the cuts we all want.

The 3.99% Rate Buydown: Orlando Builder Incentives Skyrocket

If you are looking to buy a home right now in Central Florida, the only rational place to start is new construction. The growth in Orlando means most of these options are on the outskirts—think Apopka or out the 528—but the builders have inventory they must move, and their incentives are staggering.

I definitely would start with the new build. Why? Take a look at these recent weekly promotions that hit our inbox:

  • Lennar: They are promoting an FHA 5/1 ARM at **3.99%**. Compared to a resale home running at six and a quarter on FHA, that’s a savings of nearly $500 to $600 a month in payment over a traditional resale.
  • Pulte: We are heading out to look at one this weekend offering **4.99%** on a 30-year fixed, plus flex money toward closing costs.

These offers completely change the affordability equation. While the location requires some give and take on the commute, the mathematical difference in monthly payment makes new builds overwhelmingly more attractive than existing homes.

"It really comes down to: can you live with the location compared to where your work is?"

Taylor Morrison Slash: $134K Price Cuts in St. Cloud

This is where things get truly eye-popping. This past week, Taylor Morrison’s price cut sheet in St. Cloud looked like a complete fire sale. I have never seen builder cuts like this. Look at these specific homes:

  • A house listed at $709,000 was cut to $595,000—saving **$114,000**.
  • Another listed at $714,000 was cut to $580,000—a **$134,000 savings**.
  • A property at $744,000 was slashed to $620,000—a **$124,000 reduction**.

This aggressive slashing of prices by major home builders completely resets the market. While this is fantastic news for new buyers, it is devastating for anyone who already owns in these communities and paid the higher price. This is where we are heading, potentially even years down the road, into a return of predominant short sales.

If you bought a home for $700,000 and the builder just dropped the price of the identical floor plan to $600,000, that $600,000 is now your "highest and best" comparable. If you face a job transfer to Austin, Texas, next month, your comparable says $600k. What do you do in that situation?

1,455 Price Cuts: Why Orlando Resales Are Going Stale

The "market stabilizing" narrative doesn't fit what the data is telling us on the resale side. I run a weekly update tracking the number of price cuts in the Greater Orlando area (Orange, Lake, Volusia, and Seminole), and last week alone, leading up to month-end, there were **1,455 price cuts**.

When we look at the percentage of homes that hit the stale stage (on the market for 60+ days), it’s over half of our entire inventory:

  • Orange County: 54% of listings are over 60 days.
  • Lake County: 51% of listings are over 60 days.
  • Volusia County: Nearly 60% of homes are sitting at 60 days or more.

This is precisely why we are seeing more expired and canceled listings. Buyers are sitting back, waiting, and the pool of active buyers is shrinking. We are currently seeing about a 46% gap between the number of buyers and the number of sellers. You can't just sit back and assume a house is going to sell; you have to get down into the specifics of your community itself.

"Real estate is so hyperlocal. You get one section of Altamonte Springs that can go an average of 27 days, and another similar subdivision is averaging 80 days."

The Weekly Outlook for Central Florida Real Estate

We need this global conflict to resolve quickly to get the oil flowing and bond rates dropping again. Until then, the market remains volatile. Here are the core numbers we are watching in Orlando for the five counties (Orange, Seminole, Volusia, Lake, Osceola):

  • Active Inventory: 7,365 single-family homes.
  • Average Days on Market (County Leaders): Osceola leads the "slow market" at 94 days, followed by Volusia at 86 days and Lake at 81. Seminole County is currently the lowest/most resilient market because it is a desirable suburban family community with good schools.
  • Low Sales Volume: We only had 399 homes sold in the final week before month-end. Considering the size of the region, 400 is an incredibly low number. Most of these deals were locked in before the rates took this latest uptick.

We will have the full final numbers for the month next week. Stay on top of these hyper-local shifts. It is the only way to succeed in this changing market, especially if you are considering new construction.

If you have any questions, always feel free to reach us directly at 407-616-9019. We can help you navigate these dynamic numbers in Central Florida.

SEARCH ORLANDO HOMES | ORLANDO PRICE REDUCTIONS | WHAT IS MY HOME WORTH? 

March 31, 2026

Central Florida Price Cuts Weekly Update — March 31, 2026

This week's MLS data is in, and the numbers tell a clear story: sellers across Central Florida are adjusting. As of March 31, 2026, there are 1,455 price-reduced homes spread across Orange, Seminole, Volusia, and Lake counties. That's real negotiating leverage sitting on the table for buyers who know where to look.

TLDR:
  • 1,455 total price-reduced homes across four Central Florida counties this week
  • Seminole County leads with the deepest average cuts at 8.98% off
  • Orange County has the most inventory with 590 reduced listings — 347 in Orlando alone
  • Over half of all reduced listings have been on market 60+ days — signaling motivated sellers
  • Volusia County shows 60.4% of reduced homes sitting 60+ days, the highest of all four counties

The Big Picture: Four Counties, 1,455 Price Cuts

Here's how the numbers break down county by county:

County Price-Reduced Listings Avg. Reduction 60+ Days on Market
Orange County 590 4.06% 53.9%
Lake County 377 3.66% 51.2%
Volusia County 326 6.66% 60.4%
Seminole County 162 8.98% 46.9%

The pattern is consistent: sellers are meeting the market. When more than half of reduced listings have been sitting for 60+ days, that tells you pricing expectations are still catching up to where buyers actually are.

Orange County: 590 Reductions Led by Orlando

Orange County dominates the volume with 590 price-reduced homes and an average reduction of 4.06%. Orlando accounts for 347 of those — nearly 59% of the county's total.

The standout pockets worth watching:

  • Orlando — 347 listings, avg. 3.91% off, avg. price $478,455
  • Winter Garden — 69 listings, avg. 2.78% off, avg. price $700,665
  • Apopka — 59 listings, avg. 3.46% off, avg. price $449,943
  • Winter Park — 30 listings, avg. 7.34% off, avg. price $941,338
  • Windermere — 21 listings, avg. 7.62% off, avg. price $1,711,608

Winter Park and Windermere are cutting the deepest on a percentage basis — a signal that even luxury sellers are recalibrating. At 7%+ off on average, those represent significant dollar amounts on higher-priced homes.

Browse all 590 Orange County price reductions →

Seminole County: Deepest Cuts at 8.98% Average

Seminole County may have fewer total listings at 162, but the reductions are the most aggressive in the four-county area. The 8.98% average reduction is more than double Orange County's.

  • Sanford — 39 listings, avg. 3.19% off, avg. price $426,065
  • Oviedo — 31 listings, avg. price $574,111
  • Longwood — 20 listings, avg. 3.37% off, avg. price $494,185
  • Lake Mary — 16 listings, avg. 3.18% off, avg. price $449,693
  • Winter Springs — 14 listings, avg. 2.72% off, avg. price $442,535

Another notable stat: only 46.9% of Seminole's reduced listings have been on market 60+ days, the lowest of the four counties. That suggests sellers here are adjusting faster rather than waiting it out.

Browse all 162 Seminole County price reductions →

Volusia County: 326 Reductions, Highest Share of Stale Listings

Volusia County has 326 price-reduced homes with a 6.66% average reduction — the second-deepest cuts behind Seminole. More notably, 60.4% of those reduced listings have been on market for 60+ days, the highest percentage of any county this week.

  • New Smyrna Beach — 75 listings, avg. 4.09% off, avg. price $732,831
  • DeLand — 55 listings, avg. 3.11% off, avg. price $420,184
  • Daytona Beach — 45 listings, avg. 5.6% off, avg. price $273,527
  • Deltona — 35 listings, avg. 3.09% off, avg. price $356,536
  • Ormond Beach — 30 listings, avg. 3.18% off, avg. price $648,983
  • DeBary — 20 listings, avg. 5.43% off, avg. price $520,136

Daytona Beach at $273,527 average is the most accessible price point in the county. With a 5.6% average cut, that's roughly $15,000 off — real money for first-time buyers.

Browse all 326 Volusia County price reductions →

Lake County: 377 Reductions Anchored by Clermont

Lake County comes in with 377 price-reduced homes and a 3.66% average reduction — the most conservative cuts of the four counties. Clermont leads with 95 listings, a quarter of the county's total.

  • Clermont — 95 listings, avg. 2.95% off, avg. price $611,078
  • Leesburg — 62 listings, avg. 3.99% off, avg. price $363,165
  • Eustis — 31 listings, avg. 5.54% off, avg. price $451,256
  • Groveland — 28 listings, avg. 3.58% off, avg. price $404,659
  • Mount Dora — 26 listings, avg. 6.32% off, avg. price $516,856
  • Tavares — 25 listings, avg. 3.07% off, avg. price $304,730

Eustis and Mount Dora stand out with deeper cuts (5.5%+ and 6.3%) compared to the county average. For buyers who want small-town character with lake access, those numbers are worth a closer look.

Browse all 377 Lake County price reductions →

What This Means for Buyers

Three takeaways from this week's data:

  1. Volume favors buyers. 1,455 price-reduced listings across four counties means options. You're not competing for scraps — you're choosing from a deep pool.
  2. Days on market = leverage. Over half of these homes have been sitting for 60+ days. Sellers with stale listings are often more willing to negotiate on price, closing costs, or repair credits.
  3. Location matters. Seminole County's 8.98% average cut tells a different story than Lake County's 3.66%. The deeper the cut, the more a seller has already moved toward you.

Frequently Asked Questions

How many homes have price reductions in Central Florida right now?

As of March 31, 2026, there are 1,455 price-reduced homes across Orange County (590), Lake County (377), Volusia County (326), and Seminole County (162).

Which Central Florida county has the deepest price cuts?

Seminole County currently has the deepest average price reduction at 8.98%, followed by Volusia County at 6.66%, Orange County at 4.06%, and Lake County at 3.66%.

What percentage of price-reduced homes in Central Florida have been on the market over 60 days?

Across the four-county area, more than half of price-reduced listings have been on market 60+ days: Volusia County leads at 60.4%, followed by Orange County (53.9%), Lake County (51.2%), and Seminole County (46.9%). These longer days on market often signal stronger negotiating leverage for buyers.

How often is this price cut data updated?

This data is pulled directly from Stellar MLS and updated weekly. Each county's price reduction page on homesinorlando.forsale reflects the most current MLS data available.

Want to see these price cuts before everyone else?

Set up a free daily alert and get notified the moment a new price reduction hits your target area. Or call me directly — I track this data every week and can tell you which ones are worth your time.

Search All Price-Reduced Homes

Or call Brenden Rendo: 407-616-9019

March 29, 2026

Disney World Zip Code & Orlando Theme Park Zip Codes 2026

It's one of the most searched questions about Orlando: what zip code is Disney World in? The short answer is 32830. But the full answer matters more if you're looking to buy a home, invest in a vacation rental, or simply understand the geography of Orlando's theme park corridor. Walt Disney World is so large — roughly 25,000 acres — that it touches multiple zip codes, and each one offers a different real estate picture. The same goes for Universal Studios and SeaWorld.

I've been selling homes in the Orlando theme park corridor since 2012. Here's the complete breakdown of every zip code connected to the three major parks, with current home prices, neighborhood details, and what each area offers buyers.

TLDR:
  • Disney World's main zip code is 32830, but the resort spans 32836, 32821, and borders 32819
  • Universal Studios is in 32819 (Dr. Phillips), with 32818 and 32835 nearby
  • SeaWorld is in 32821 (Williamsburg area), between I-Drive and Disney
  • Home prices near the parks range from $355K (Metrowest) to $991K (Lake Buena Vista)
  • All three parks sit in a cluster of southwest Orlando zip codes — see the complete Orlando zip code guide for the full map

Walt Disney World Zip Codes

Walt Disney World doesn't fit neatly into one zip code. The resort's 25,000 acres span four zip codes, and the surrounding residential areas add several more to the picture.

32830 — Walt Disney World Resort (Core)

This is the official Disney World zip code — the one on the mailing address for Magic Kingdom, EPCOT, Hollywood Studios, and Animal Kingdom. Zip code 32830 is almost entirely owned by Disney and has virtually no residential real estate. If you're mailing something to Disney World, this is the zip code you use.

32836 — Lake Buena Vista / Disney Springs

Zip code 32836 includes Disney Springs (formerly Downtown Disney) and the Lake Buena Vista area. This is where Disney meets residential real estate. You'll find luxury homes, gated communities, and properties that quite literally back up to Disney property lines.

  • Median home price: $991,096
  • Neighborhood: Lake Buena Vista
  • Best for: Luxury buyers, vacation rental investors, Disney employees wanting a short commute
  • Active listings: 139

32821 — Williamsburg Area

Zip code 32821 sits between Disney's Animal Kingdom and International Drive. It's one of the most popular areas for vacation rental investment because of its proximity to both Disney and SeaWorld. The Williamsburg area has a mix of resort-style condos, vacation homes, and traditional residential properties.

  • Median home price: $419,825
  • Neighborhood: Williamsburg / South I-Drive
  • Best for: Vacation rental investors, short-term rental owners, SeaWorld and Disney commuters
  • Active listings: 195

32819 — Dr. Phillips / Bay Hill

Zip code 32819 is the residential powerhouse next to Disney. Dr. Phillips and Bay Hill are established, upscale neighborhoods with top-rated schools, Restaurant Row on Sand Lake Road, and a straight shot to both Disney and Universal. This is where most full-time residents who work at the parks choose to live.

  • Median home price: $630,919
  • Neighborhood: Dr. Phillips, Bay Hill, Restaurant Row
  • Best for: Families, luxury home buyers, theme park employees wanting quality of life
  • Active listings: 234

Universal Studios Orlando Zip Codes

Universal Orlando Resort — including Universal Studios, Islands of Adventure, and the new Epic Universe — sits in zip code 32819. But the surrounding zip codes offer more affordable options for buyers and renters.

32819 — Dr. Phillips (Universal's Home Zip)

Universal shares zip code 32819 with Dr. Phillips, making this area a dual-park hub. North International Drive, CityWalk, and the resort hotels are all here. If you want to live within minutes of both Universal and Disney, 32819 is the zip code.

32818 — Metrowest

Zip code 32818 covers Metrowest, one of Orlando's largest master-planned communities. It's directly west of Universal Studios and offers significantly more affordable housing than Dr. Phillips. For theme park workers or investors looking for rental income near Universal, Metrowest is the value play.

  • Median home price: $355,275
  • Neighborhood: Metrowest, West Orlando
  • Best for: First-time buyers, Universal employees, value-oriented investors
  • Active listings: 99

32835 — Kirkman South / International Drive South

Zip code 32835 covers the southern stretch of International Drive, including the Orange County Convention Center. It borders both Universal and the tourist corridor. Housing here tends toward condos and smaller properties that attract investors targeting the short-term rental market.

  • Median home price: $355,535
  • Neighborhood: Kirkman South, Metrowest South, Convention Center area
  • Best for: Investors, convention-area rental demand, I-Drive workers
  • Active listings: 302

SeaWorld Orlando Zip Code

32821 — Williamsburg (SeaWorld's Home Zip)

SeaWorld Orlando and its water park Aquatica sit in zip code 32821, the same zip that borders Disney's southern edge. This makes 32821 uniquely positioned between two of the three major parks. The area is heavily tourism-oriented, with a mix of vacation rentals, resort communities, and traditional residential neighborhoods.

SeaWorld employees and frequent visitors will find 32821 convenient, but nearby Hunters Creek (32837) offers a more residential, family-friendly alternative just minutes south.

Best Residential Zip Codes Near All Three Parks

If proximity to all three theme parks matters — whether for work, investment, or lifestyle — here are the residential zip codes that put you closest to the action:

Zip Code Area Median Price Nearest Park Best For
32819 Dr. Phillips $630,919 Universal (5 min), Disney (15 min) Families, luxury
32836 Lake Buena Vista $991,096 Disney (5 min) Luxury, investment
32821 Williamsburg $419,825 SeaWorld (5 min), Disney (10 min) Vacation rentals
32818 Metrowest $355,275 Universal (10 min) Value, first-time buyers
32835 Kirkman South $355,535 Universal (10 min), SeaWorld (10 min) Investors, I-Drive
32837 Hunters Creek $563,366 SeaWorld (10 min), Disney (15 min) Families
32824 Meadow Woods $406,562 Disney (15 min), SeaWorld (15 min) Affordable option

For the full directory of all 29 Orlando zip codes with an interactive map, visit our Orlando Zip Codes guide.

Frequently Asked Questions

What is the zip code for Walt Disney World?

Walt Disney World's main mailing address uses zip code 32830. However, the resort is so large that it spans parts of several zip codes including 32836 (Lake Buena Vista/Disney Springs), 32821 (Williamsburg area near Disney's Animal Kingdom), and 32830 for the core resort including Magic Kingdom and EPCOT.

What zip code is Universal Studios Orlando in?

Universal Orlando Resort is located in zip code 32819, which covers the Dr. Phillips and Bay Hill neighborhoods. The surrounding areas of 32818 (Metrowest) and 32835 (Kirkman South) are also close to Universal and offer more affordable housing options.

What zip code is SeaWorld Orlando in?

SeaWorld Orlando and Aquatica are located in zip code 32821, in the Williamsburg area of southwest Orlando between International Drive and Walt Disney World.

Can you buy a house near Disney World in Orlando?

Yes. Several residential zip codes surround Disney World with homes ranging from the mid-$300s to over $1 million. Dr. Phillips (32819) offers luxury homes with a median around $631,000. Hunters Creek (32837) is more family-oriented with a median around $563,000. Meadow Woods (32824) provides the most affordable options near the parks with a median around $407,000.

Which Orlando zip code is best for vacation rental investment near the theme parks?

Zip code 32821 (Williamsburg area) and 32836 (Lake Buena Vista) are popular for vacation rental investment due to their proximity to Disney World and established short-term rental zoning. The International Drive corridor in 32819 and 32835 also sees strong vacation rental demand from Universal Studios visitors.

How far are the Orlando theme parks from each other by zip code?

Disney World (32830) and SeaWorld (32821) are about 10 minutes apart. Universal Studios (32819) is roughly 20 minutes from Disney World and 10 minutes from SeaWorld. All three theme parks sit within a cluster of zip codes in southwest Orlando, making the surrounding residential areas convenient for anyone working in or visiting the parks.

Looking to Buy Near the Theme Parks?

Whether you're searching for a vacation rental investment near Disney or a family home close to Universal, I can help you find the right property in the right zip code. I've been working the Orlando theme park corridor since 2012.

Search Homes Near the Parks

Contact Brenden Rendo | 407-616-9019

The Homes In Orlando Team | 890 Northern Way, Suite D-1, Winter Springs, FL 32708

March 17, 2026

7 Orlando Housing Market Data Points That Push Back on the Doomer Narrative

7 Orlando Housing Market Data Points That Push Back on the Doomer Narrative

Housing is expensive, and rates are higher than the unicorn years of 2020. But before you believe the "crash" narrative taking over your social media feed, you need to look at the numbers hitting the ground right here in Orange and Seminole Counties. Affordability is finally improving, and it's happening because buyers finally have the upper hand.

TLDR — March 2026 Weekly Update:
  • Central Florida inventory has surged to 7.19 months of supply — the highest level since 2010.
  • Mortgage rates have eased to 6.11%, well below last year's 7.5% peaks.
  • The Buy-vs-Rent gap is the smallest it's been in 3 years.
  • Builders in Horizon West and Sunbridge are buying rates down as low as 5.25%.
  • The data shows a healthy rebalancing toward buyers — not a 2008-style crash.

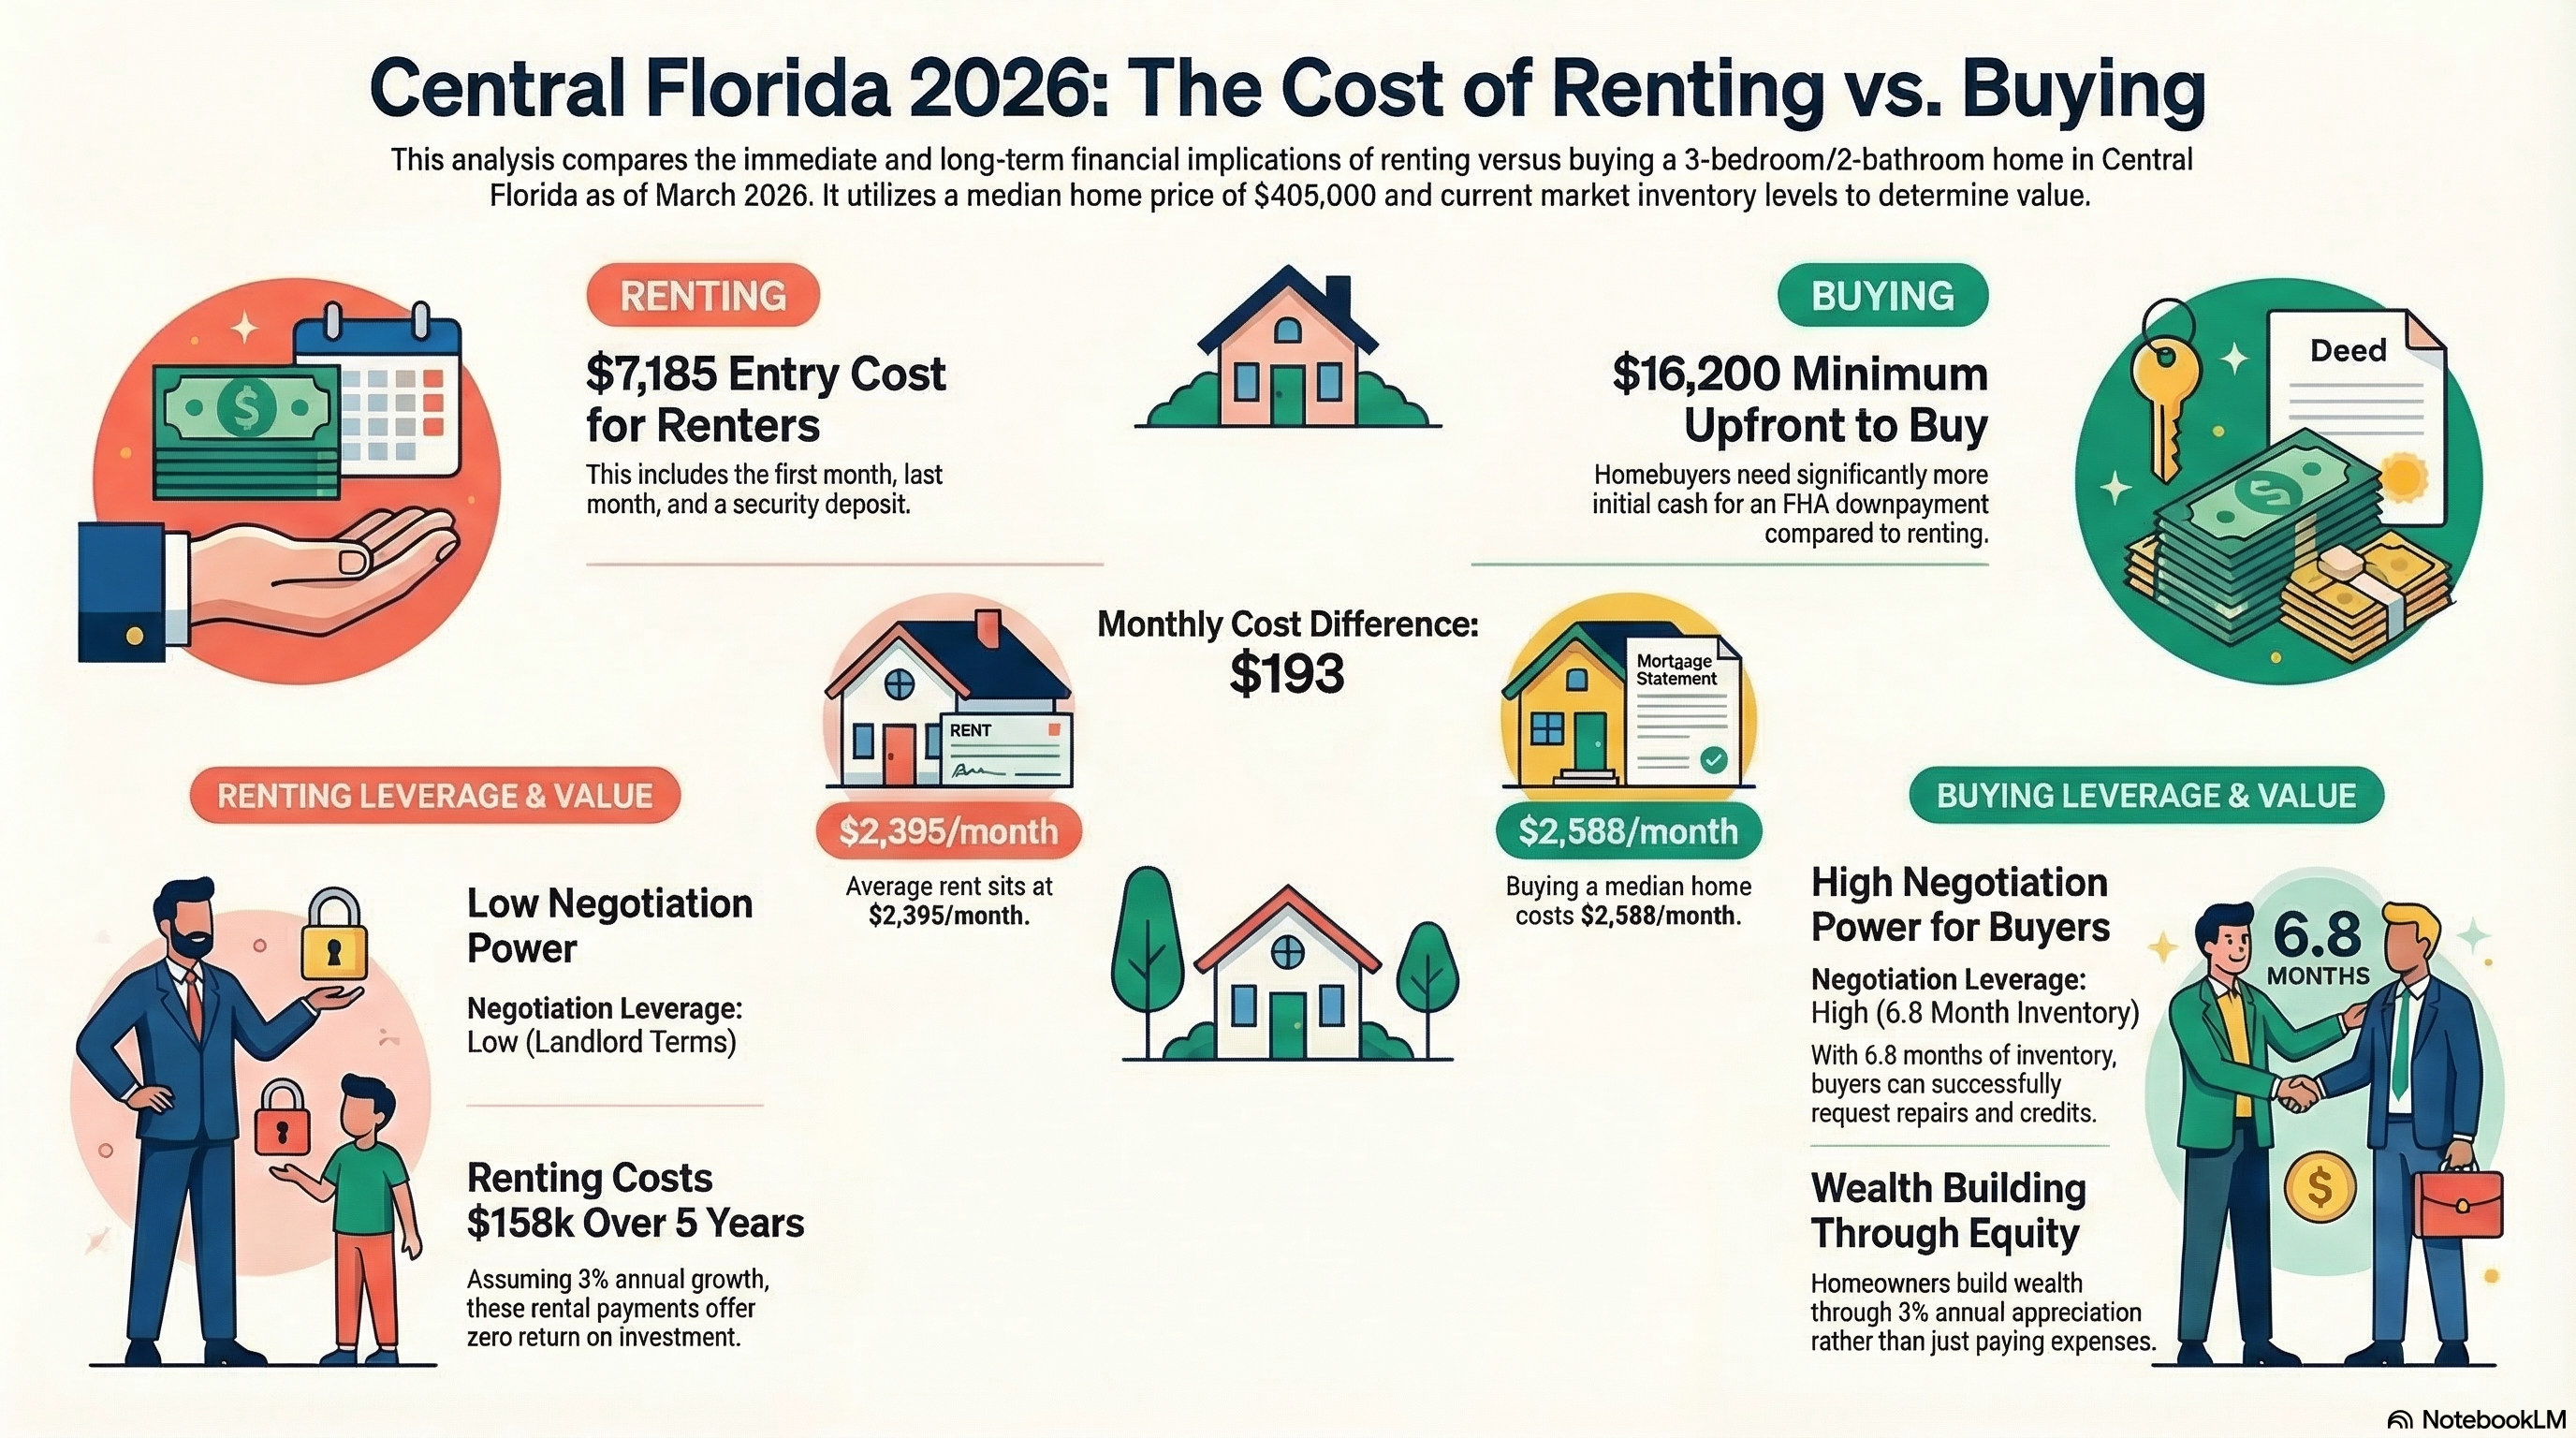
Rent vs Buy Orlando 2026 — Central Florida affordability data

1. Mortgage Rates Have Eased & Refis Are Back

As of March 16, 2026, the average 30-year fixed rate in Florida is 6.11%. That is a massive relief from the 7.5% peaks we saw last year. For families in Altamonte Springs or Lake Mary who bought in 2024, the math for a refinance is finally starting to work, potentially shaving hundreds off monthly payments.

2. The Buy vs. Rent Gap is the Smallest in 3 Years

In Orlando, the average 3-bedroom house for rent is now $2,395/month. When you compare that to a median mortgage payment in our current market, the gap is narrowing. With wages up and home price growth slowing to a sustainable 2-4%, the "cost of waiting" is officially starting to outweigh the "cost of owning."

3. Monthly Payments Actually Dipped in 2025

Nationwide and locally, median mortgage payments dropped by roughly $102 last year. For a typical home in Apopka or Winter Garden, that's $1,200 a year back in your pocket. Combined with the Florida Homestead exemption, your "real" monthly cost is lower than the headlines suggest.

4. Renters Are Gaining Leverage

For the first time since 2020, landlords are offering concessions. Whether you're in Baldwin Park or Downtown Orlando, vacancy rates are higher, giving renters the power to negotiate or finally make the jump into homeownership as leases expire.

5. Builders Are Cutting Prices & Buying Rates

In Horizon West and Sunbridge, builders aren't just cutting prices; they are buying down rates. We are seeing incentives as low as 5.25% for qualified buyers, which changes your monthly payment far more than a simple price drop on a resale home would.

6. Inventory: 7.19 Months of Supply

The Orlando Regional REALTOR® Association recently confirmed that inventory has hit 7.19 months — the highest point since November 2010. A "balanced" market is 6 months. We have officially crossed that line, meaning you can finally ask for repairs, closing cost credits, and a fair price without being outbid in 2 hours.

7. No One Serious Is Predicting a Crash

The professionals who study housing for a living aren't calling for 2008. We are seeing a normalization. Prices are expected to grow modestly or hold steady. If you're waiting for a 50% drop, you're missing out on the best selection of homes we've seen in a decade.

Find the Best Deals in Central Florida

Because inventory is at a 10-year high, "price drops" are your best friend. I've curated the most up-to-date lists of the most motivated sellers across all four Central Florida counties I cover. Click below to see the latest adjustments:

📍 Seminole County

Over 68% of homes are selling below list. Check out the latest cuts in Lake Mary and Oviedo.

View Seminole County Price Drops »

📍 Orange County

7.19 months of supply is a buyer's dream. See price reductions in Winter Garden and Lake Nona.

View Orange County Price Drops »

📍 Volusia County

Coastal markets like DeLand and Deltona are seeing meaningful adjustments as the rebalancing spreads east.

View Volusia County Price Drops »

📍 Lake County

Clermont and Mount Dora sellers are coming off peak pricing — strong opportunities for relocation buyers.

View Lake County Price Drops »

Frequently Asked Questions

Is Orlando in a Buyer's or Seller's market?

With over 7 months of inventory, we have officially moved into a Buyer's Market for the first time in years. This means you have more leverage to negotiate price and repairs.

What is the median home price in Orlando right now?

The median price is holding steady in the $405,000 - $415,000 range, though price adjustments are common in the luxury and new construction segments.

Are home prices going to drop in Orlando in 2026?

No serious housing economist is calling for a 2008-style crash. Central Florida prices are expected to grow modestly at a 2-4% annual pace or hold steady, while individual sellers are cutting prices on stale listings to compete with the higher inventory.

Should I buy now or wait for rates to drop in Orlando?

With 30-year rates at 6.11%, inventory at a 10-year high, and builders buying rates down to as low as 5.25% for qualified buyers, the cost of waiting is starting to outweigh the cost of owning. Buyers today have negotiating leverage on price, repairs, and closing costs that did not exist 18 months ago.

Expert Advice for the Orlando Market

Don't let a viral chart dictate your financial future. Get the local facts.

The Homes In Orlando Team | Brenden Rendo
635 Green Briar Blvd, Altamonte Springs, FL 32714
Phone: +1-407-616-9019

View All Orlando Area Listings Today »

March 12, 2026

Orlando Housing Market: The Home Shortage Myth & Starter Home Gap

March 12, 2026 — Orlando Housing Market Update

Three big themes this week: mortgage rates pushed higher as the Iran conflict drove the 10-year Treasury from ~4.09 to ~4.24; the popular "housing shortage" narrative gets challenged directly; and the real gap is the absence of true starter homes in the $250,000–$300,000 range. Orlando's local numbers held steady — single-family sales stayed above 400 for a second straight week, inventory is rising, and days on market hover around 75 days, keeping negotiating leverage firmly with buyers.

Jump to: Rates & Iran · The housing shortage myth · Institutional investors · Florida insurance reality · The missing starter home · Orlando numbers

There are weeks when the market feels like it is moving on pure math, and there are weeks when it feels like it is being pushed around by headlines, politics, and emotion. This is one of those second weeks. In this episode of the Orlando market update, the biggest theme is not just what the numbers say, but how badly those numbers are often used. That matters, because buyers, sellers, and investors are making real decisions with real money based on half-truths, clickbait, and political talking points.

The episode opens with a straightforward warning: rates have moved up again, and they are doing it at a bad time. Spring is when the resale market typically starts to build momentum, and Orlando had finally shown signs of life. Yet the conflict in Iran pushed oil prices up, helped drive the 10-year Treasury higher, and put upward pressure on mortgage rates. The move may sound small to people outside housing, but when buyers have been sitting on the fence waiting for anything psychologically better than 6%, even a quarter-point shift can change behavior.

"If you're out there and you're starting to look, you may not want to lock in rates."

Rates, Iran, Oil, and the 10-Year Treasury

One of the clearest parts of the transcript is the relationship between geopolitical tension and rate movement. The point is not abstract. Oil surged. Gas prices jumped. The 10-year Treasury climbed from below roughly 4.09 to around 4.24. At the same time, the margin between the 10-year and the 30-year mortgage stayed relatively tight, roughly around 2%, which means lenders still have some room to help if they choose to keep momentum in the resale market going.

That is the practical takeaway for buyers. The market is in a wait-and-watch mode, but it is not frozen. If the conflict drags on another four to six weeks, higher oil and higher gas could push inflation back up for a month or two even after a relatively calm CPI print. That means a buyer needs to talk to a lender about flexibility. A strong lender with access to multiple underwriting channels matters in an environment like this because it creates options if rates shift quickly. The transcript makes the point well: this is one of those "double-edged sword" moments. Rates could get worse if the conflict escalates, but they could also settle down just as quickly if things calm.

The "Housing Shortage" Narrative Gets Challenged

This is the emotional core of the episode. The rant is clear: stop repeating that there are simply "not enough homes" as if that ends the discussion. The argument here is that homes exist, but many of them are not easy, turnkey, or sitting in perfect condition waiting for a retail buyer to swipe a card. They need to be found. They need work. They may be off-market. They may be inherited homes, vacant homes, tired homes, or homes owned by people who have lived there for decades and have not taken the step to sell yet.

That distinction matters. A true shortage would mean homes fly off the shelf no matter what. Prices would be screaming higher everywhere. Days on market would not be stretching. Negotiation would not be normal. Yet that is not what the speaker sees. Homes are sitting longer. Some markets are moving faster than others, but nationally there are millions of vacant homes. Locally, off-market opportunities still exist. The transcript even gives a real-world example of a neighborhood home sitting vacant after the owner passed away, plus a bizarre title-fraud attempt that neighbors helped stop.

The message is not that every claim about housing supply is fake. The message is that the broad, lazy "there just aren't enough homes" narrative often hides the more useful truth. The issue is more specific. There may be shortages in certain product types, price bands, neighborhoods, or condition levels. But that is not the same thing as saying opportunity does not exist.

"We do not have a housing shortage. The houses are out there. You've got to go find them."

Institutional Investors, Local Investors, and Political Noise

Another major thread in the transcript is frustration with how institutional investors are used as a convenient villain. The speaker argues that both sides of the political aisle use numbers as propaganda, and housing is no exception. The cleanest example is the claim that institutional investors are "destroying housing." The counterpoint here is that institutional buyers account for only about 1.4% of homes bought and sold, while small local investors represent something closer to 25%.

That distinction matters because it changes the policy conversation. The transcript's view is not anti-investor. It is anti-bad-analysis. Local investors buy distressed homes because many owner-occupants do not want to deal with rehab, unknown costs, contractors, and project management. When someone passes on a house that needs $60,000 in work even though it is priced $150,000 under market, that is not proof that investors stole it. It is proof that many buyers do not want the hassle.

This part of the episode is really about critical thinking. Stop letting headlines replace actual analysis. Stop letting emotional social content define the market. And stop assuming every statistic is being presented in good faith.

Florida Insurance Reality Is More Nuanced Than the Headlines

Florida insurance gets treated the same way. The national narrative is usually that insurance is exploding forever and there is no relief in sight. But the local point made in this episode is the opposite: year over year, Florida has actually seen some of the largest insurance decreases, and Orlando specifically has seen rates level off and decline by roughly 2 points. That is not the same thing as saying insurance is cheap, but it is a direct challenge to the nonstop doom loop.

The transcript then gives a concrete example: a roughly $250,000 new construction home with an insurance quote of just $512 per year. That is a huge reminder that context matters. Newer homes will often price very differently than older ones, and buyers have options to lower cost beyond just shopping carriers. Roof improvements, hurricane clips, and better structural mitigation can make a real difference.

The Missing Starter Home Is the Real Problem

This may be the most useful part of the entire episode. The argument is that the American housing ladder has broken. Instead of moving from renting to a starter home and then into a move-up or forever home, too many people are going from expensive "luxury" apartments straight into trying to buy a $400,000 to $600,000 house. That jump is too large, and it is one reason affordability feels impossible.

The speaker makes a sharper point: the market has skipped the true starter home. The sweet spot is somewhere around $250,000 to $300,000. Production builders do not want to live there because they need to maximize profit per square foot and satisfy shareholders. So the market keeps producing larger, more expensive homes while younger or newer buyers stay stuck in rent.

That is where the argument for smaller homes really comes in. There is nothing wrong with a first home being 1,100 to 1,200 square feet. It does not have to be your dream home. It is a starter. It is an investment. The transcript says people who buy earlier in life can end up with roughly 22% higher net worth than those who rent until 35 to 40. Whether the exact number moves over time or not, the underlying point stands: homeownership earlier in the wealth-building cycle matters.

"There's nothing wrong with your first home being 1,100 or 1,200 square feet. It's a starter home."

Orlando Numbers: Still Steady, Still Negotiable

The local Orlando numbers are the part that keeps this episode grounded. Despite higher rates, the single-family market stayed above 400 weekly sales for a second straight week, something the speaker says had not happened in over a year. Inventory is also growing, which is normal for the season and could climb into the 850 to 860 range if the pattern holds through early summer. That is healthy. More inventory with stable sales is not a collapse. It is a market with choice.

On the condo side, weekly sales are still around the 100 level, inventory has increased a bit, and the original-list-to-sale-price ratio is running around 94%. That means negotiation is still very much part of this market. Days on market remain elevated, around 75 days, and more than half the homes on the market have been sitting for more than 60 days. That is exactly why the episode keeps returning to opportunity. There is room to negotiate. There is room to structure deals. There is room for buyers who are willing to do the work and not get hypnotized by national noise.

What Buyers Should Do With This

First, stop shopping emotionally. Watch the 10-year Treasury. Know that mortgage pricing is not magic. Talk to a lender who can move between multiple outlets. Stay flexible on lock timing. Second, do not assume the MLS tells the full story. Direct mail, neighborhood outreach, tax records, off-market networking, and local relationships still matter. Third, reframe the starter home. Smaller is not failure. Smaller is the first rung. Fourth, challenge fear-based assumptions about insurance, investors, and supply with real local analysis.

Search Orlando homes  ·  Browse price reductions  ·  Get your free home valuation  ·  Talk to our trusted lender

What Sellers Should Do With This

If you are a seller, you should take two lessons from this episode. One, do not assume a broad "housing shortage" will save an overpriced listing. It won't. Two, if buyers are stretched by rates, gas, insurance, and debt, then pricing and presentation matter more, not less. If your home is clean, priced well, and marketed honestly, it will still draw attention. If it is not, the market will tell you quickly.

Watch the Full Episode

Frequently Asked Questions

Is there actually a housing shortage in Orlando?

Not in the traditional sense. Many homes exist but are off-market, need renovation, or are held by owners reluctant to sell at current prices. The real issue is a shortage of move-in-ready, competitively priced inventory — not a shortage of homes.

Why are starter homes so hard to find in Orlando right now?

Production builders avoid the $250,000–$300,000 price range because profit margins are too thin at that price point. The result is a genuine gap in entry-level housing, which pushes first-time buyers toward older inventory or further from urban centers.

How long are homes sitting on the market in Orlando?

As of March 2026, the average days on market in Orlando is approximately 75 days, with more than half of active listings exceeding 60 days. That extended timeline gives buyers meaningful negotiating leverage on price, concessions, and repairs.

Talk to a Local Orlando Market Expert

Rates are moving, inventory is growing, and the negotiating window is open. Get accurate, local guidance before you make your next move.

The Homes In Orlando Team | Brenden Rendo
890 Northern Way, Suite D-1, Winter Springs, FL 32708
Phone: +1-407-616-9019

Search All Orlando Area Listings Today

March 9, 2026

3 Biggest Pricing Mistakes Orlando Home Sellers Are Making in 2026

What you need to know before pricing your Orlando home in 2026:

  • Average days on market in Orlando is running around 75 days, and more than half of active listings have been sitting over 60 days
  • The list-to-sale ratio on area condos is approximately 94%, meaning buyers are routinely negotiating 6% off asking price
  • Overpriced homes go algorithmically invisible to the buyers most likely to make competitive offers
  • Three mistakes are responsible for most stalled listings: pricing too high as a buffer, skipping pre-listing inspections, and relying on comparables that are already 90+ days old
  • Each mistake is fixable, and correcting them early almost always produces a better outcome than a price reduction 45 days in

Every spring, the same conversation plays out across Orange and Seminole counties. A seller sits down with their agent, reviews what their neighbor got two years ago, adds a little cushion "just in case," and lists at a number that feels safe. Six weeks later, the home is still on the market, showings have dropped off, and the seller is now looking at a price reduction that wipes out any equity advantage they thought they had built in.

The 2026 Orlando market is not a forgiving environment for pricing errors. Buyers have more inventory to choose from than they did 18 to 24 months ago. Mortgage rates have pushed monthly payment sensitivity to the point where a $10,000 difference in list price can push a buyer into or out of a property depending on their debt-to-income ceiling. And the days of homes attracting multiple offers regardless of condition or price are largely over in most Central Florida neighborhoods. What replaces that environment is a more analytical buyer, one who compares carefully, negotiates deliberately, and walks away from anything that does not clearly justify its price.

The sellers who do well in this market are the ones who understand that pricing is not just a number. It is a positioning decision. The sellers who struggle are usually making one of the same three mistakes.

1. Pricing Too High to Leave Room for Negotiation

This is the most common pricing mistake in Central Florida right now, and it is also the most counterintuitive to correct. The logic sounds reasonable on the surface: list high, leave room to come down, and land somewhere in the middle. In practice, this strategy consistently produces worse outcomes than accurate pricing from day one.

Here is why. The majority of home searches in 2026 happen through portals and apps that filter by price bracket. A buyer with a $450,000 budget typically sets their ceiling at $450,000 or $460,000, not $475,000. If your home is priced at $469,000 because you want room to negotiate, the largest pool of qualified buyers for your property never sees it. You are not negotiating with anyone because the people most likely to make competitive offers on a $450,000 home have algorithmically filtered you out.

The homes that go under contract quickly in Orlando right now are not the ones that gave buyers the biggest discount. They are the ones that entered the market at a price that generated immediate attention from multiple buyers in the right range. That attention creates competition. Competition creates offers. Competing offers create leverage for the seller. An accurately priced home in Lake Mary, Oviedo, or the neighborhoods of East Orlando has a real shot at inspiring multiple showings in the first two weeks, which is when buyer interest is at its peak.

The data backs this up. With average days on market hovering around 75 days across the Orlando metro and more than half of active listings sitting past the 60-day mark, the market is giving sellers clear feedback that initial pricing matters. A home that sits for 60 days and then reduces price is, in most cases, selling for less than it would have if it had been correctly priced from the start. Buyers who see a price reduction often wonder what is wrong with the property. The stigma of a stale listing is a real cost, and it rarely shows up in the listing price analysis a seller does before going to market.

Think of your list price as an invitation. If the invitation is priced correctly for the right guests, more people show up. More people showing up means a better outcome, not because you gave anything away, but because you created the conditions for the market to work in your favor.

You can see how this plays out in real time by reviewing price-reduced listings in Orange County. The volume and frequency of reductions tells you where the original pricing was off relative to actual buyer demand.

2. Skipping the Pre-Listing Inspection

Florida buyers in 2026 carry a specific anxiety that does not exist to the same degree in other markets: insurance cost and eligibility. After years of insurer exits, premium increases, and tightened underwriting standards, buyers have become deeply cautious about committing to a home without understanding exactly what it will cost to insure. That caution shows up most visibly in the inspection and due diligence period, and it is where a surprising number of deals fall apart.

A pre-listing inspection changes this dynamic entirely. When a seller provides a completed 4-Point inspection and Wind Mitigation report before buyers even tour the home, several things happen. First, there are no surprises. A buyer who finds a four-year-old roof, updated electrical, and a well-maintained HVAC system in a pre-listing report does not go looking for leverage during the contract period. They make a cleaner offer because they have confidence in what they are buying. Second, the insurance conversation is simplified. A Wind Mitigation report that qualifies for credits gives the buyer a concrete picture of carrying costs. In a market where a new construction home can come in with annual insurance under $600, the comparison matters, and sellers of resale homes who can demonstrate their property's insurability have a real competitive advantage.

Third, and most practically, a pre-listing inspection eliminates the "discovery" dynamic that buyers use to renegotiate price after going under contract. In a buyer's market, inspections are regularly used as a second round of negotiation. A buyer who finds $8,000 in items during their own inspection will ask for concessions. A seller who has already disclosed those items, or better still already addressed them, removes that leverage entirely.

The Homes In Orlando Team covers the cost of a professional pre-listing inspection for sellers who list with us, including both the 4-Point and Wind Mitigation reports. This is not a marketing gimmick. It is a structural advantage that consistently produces stronger offers and smoother closings. You can find out what your home is worth and learn how to claim this benefit by visiting our free home valuation tool.

If you are considering selling in Seminole County or Orange County in the next 90 days, the inspection investment, whether you pay for it yourself or work with an agent who covers it, will almost certainly return more than it costs.

3. Pricing Based on Comparables That Are Already Stale

The third mistake is the subtlest of the three, and it is particularly damaging right now because the Orlando market has been shifting on a quarterly basis rather than an annual one.

Traditional comp analysis in a stable market looks back 90 to 180 days. When the market is consistent, what sold eight months ago is a reasonable approximation of what will sell today. In 2026, that assumption is a liability. What sold in the fourth quarter of 2025, when buyer sentiment was different, rates were different, and inventory levels were different, is not necessarily a reliable anchor for what a buyer will pay today. The macro environment has shifted enough in recent months that 90-day comps can overstate value in some neighborhoods and, in a smaller number of cases, understate it where local demand has remained strong.

The sellers most exposed to this mistake are the ones relying on their own Zillow research, a Zestimate, or a list of sales their agent pulled six weeks ago and has not revisited since. If the comps feeding your pricing decision are primarily from Q3 or Q4 2025, you are not pricing your home. You are guessing at where it was priced six months ago.

What matters most right now is 30-day data. What has actually closed in your ZIP code or subdivision in the last 30 days? What are the active listings competing directly with yours priced at? How many of those active listings have already made price adjustments? In neighborhoods like Lake Mary and surrounding Seminole County communities, you can get a real-time read by reviewing homes that have recently reduced their asking price. The pattern of when and how much tells you where the original estimates were off relative to buyer behavior.

The practical correction here is straightforward: ask your agent for a comp analysis that specifically excludes anything over 45 days old and weights closed sales in the last 30 days most heavily. If there are not enough recent closes in your immediate area, pull from adjacent neighborhoods with similar price points and construction vintage. That discipline, even if it produces a number that is somewhat lower than what you hoped, gives you a starting price that the market can actually meet. A home priced to close in 30 days will, in most cases, net more than a home priced to sit for 75 and then reduced twice.

4. How to Position Your Home to Win in This Market

Fixing these three mistakes is not complicated, but it does require a willingness to let data lead rather than emotion. The sellers who do well right now are the ones who approach the listing as a strategic decision rather than a wishful one.

Start with an honest comp review that uses only recent data. Get clear on what buyers in your price band are actually seeing when they search. If your price puts you in a bracket where buyers are comparing your home to newer construction or homes with recent updates, you need to either price below that competition or invest in the presentation to justify the comparison. There is no middle ground. A home that is priced the same as better options will lose that comparison every time.

Then address the inspection piece proactively. Even if your agent does not cover the cost, the investment in a pre-listing 4-Point and Wind Mitigation report is typically under $300 to $400 and pays for itself many times over in smoother negotiations and fewer post-inspection concession requests.

Finally, watch the market in real time once your home is listed. Ten to fifteen showings without an offer is the market telling you something specific. That feedback is valuable, and acting on it quickly is almost always better than waiting to see if the next showing breaks the pattern.

The buyers who are active in this market right now are analytical, patient, and negotiation-aware. They are not going to overpay for a home because the seller has an emotional attachment to a particular number. But they will pay full price, and sometimes more, for a home that is priced accurately, shows cleanly, and has the documentation to back up its value. That is the window that exists right now, and it is a real one for sellers who are willing to work within it.

Orange County

See where sellers in Orange County have already adjusted pricing, and what the current competition looks like.

Browse Price Reductions

Seminole County

Review active price reductions across Seminole County to benchmark where demand is meeting supply today.

Browse Price Reductions

Frequently Asked Questions

Why does pricing my Orlando home too high actually hurt my bottom line?

A high list price filters out qualified buyers at the search level. Most buyers set maximum price alerts and your home never appears. With average days on market in Orlando running around 75 days and over half of active listings sitting past 60 days, an overpriced home goes stale fast. The longer it sits, the more leverage shifts to buyers who will negotiate harder on price and concessions. An accurate price creates competition; competition drives the final number up.

How does a pre-listing inspection help me sell faster in Orlando?

Florida buyers in 2026 are acutely focused on insurance eligibility and carrying costs. A pre-paid 4-Point and Wind Mitigation inspection tells buyers exactly what they are getting before they make an offer, so there are no surprises during the contract period that kill the deal. Homes with inspection reports on file routinely receive stronger, cleaner offers because buyers feel confident about what they are committing to, and their lenders and insurers have fewer objections.

How do I know if I need to reduce my asking price?

The market tells you clearly. If you have had 10 to 15 showings in areas like Lake Mary, Oviedo, or Orlando proper without receiving an offer, price is almost always the issue. You can gauge where the market is heading by reviewing how other sellers are adjusting. Look at active listings in your ZIP code that show price reduction history. In 2026, the list-to-sale ratio on Orlando area homes is running around 94%, meaning buyers regularly negotiate 6% off asking. If your home has been on the market more than 30 days without meaningful interest, a price correction will do more than any open house.

Get an Accurate Orlando Home Value Without the Guesswork

Find out what your home is actually worth in today's market, and learn how to qualify for The No Surprises Listing.

The Homes In Orlando Team | Brenden Rendo
890 Northern Way, Suite D-1, Winter Springs, FL 32708
Phone: +1-407-616-9019

Get Your Free Orlando Home Valuation Today

Posted in Topic Of Interest
Feb. 27, 2026

Paperwork Survival Guide for Buying or Selling a Home

TLDR: Create one master digital folder (with numbered subfolders like 01_Contract, 02_Disclosures, etc.) the day you start your home transaction. Name every file consistently using a date-type-source-version format. Keep a running "Action Notes" doc to track what each document requires and its deadline. Protect sensitive loan docs, set twice-weekly calendar reminders to file new documents, and retain all signed closing paperwork long after the deal closes. A little structure upfront prevents the "we need this today" panic later.

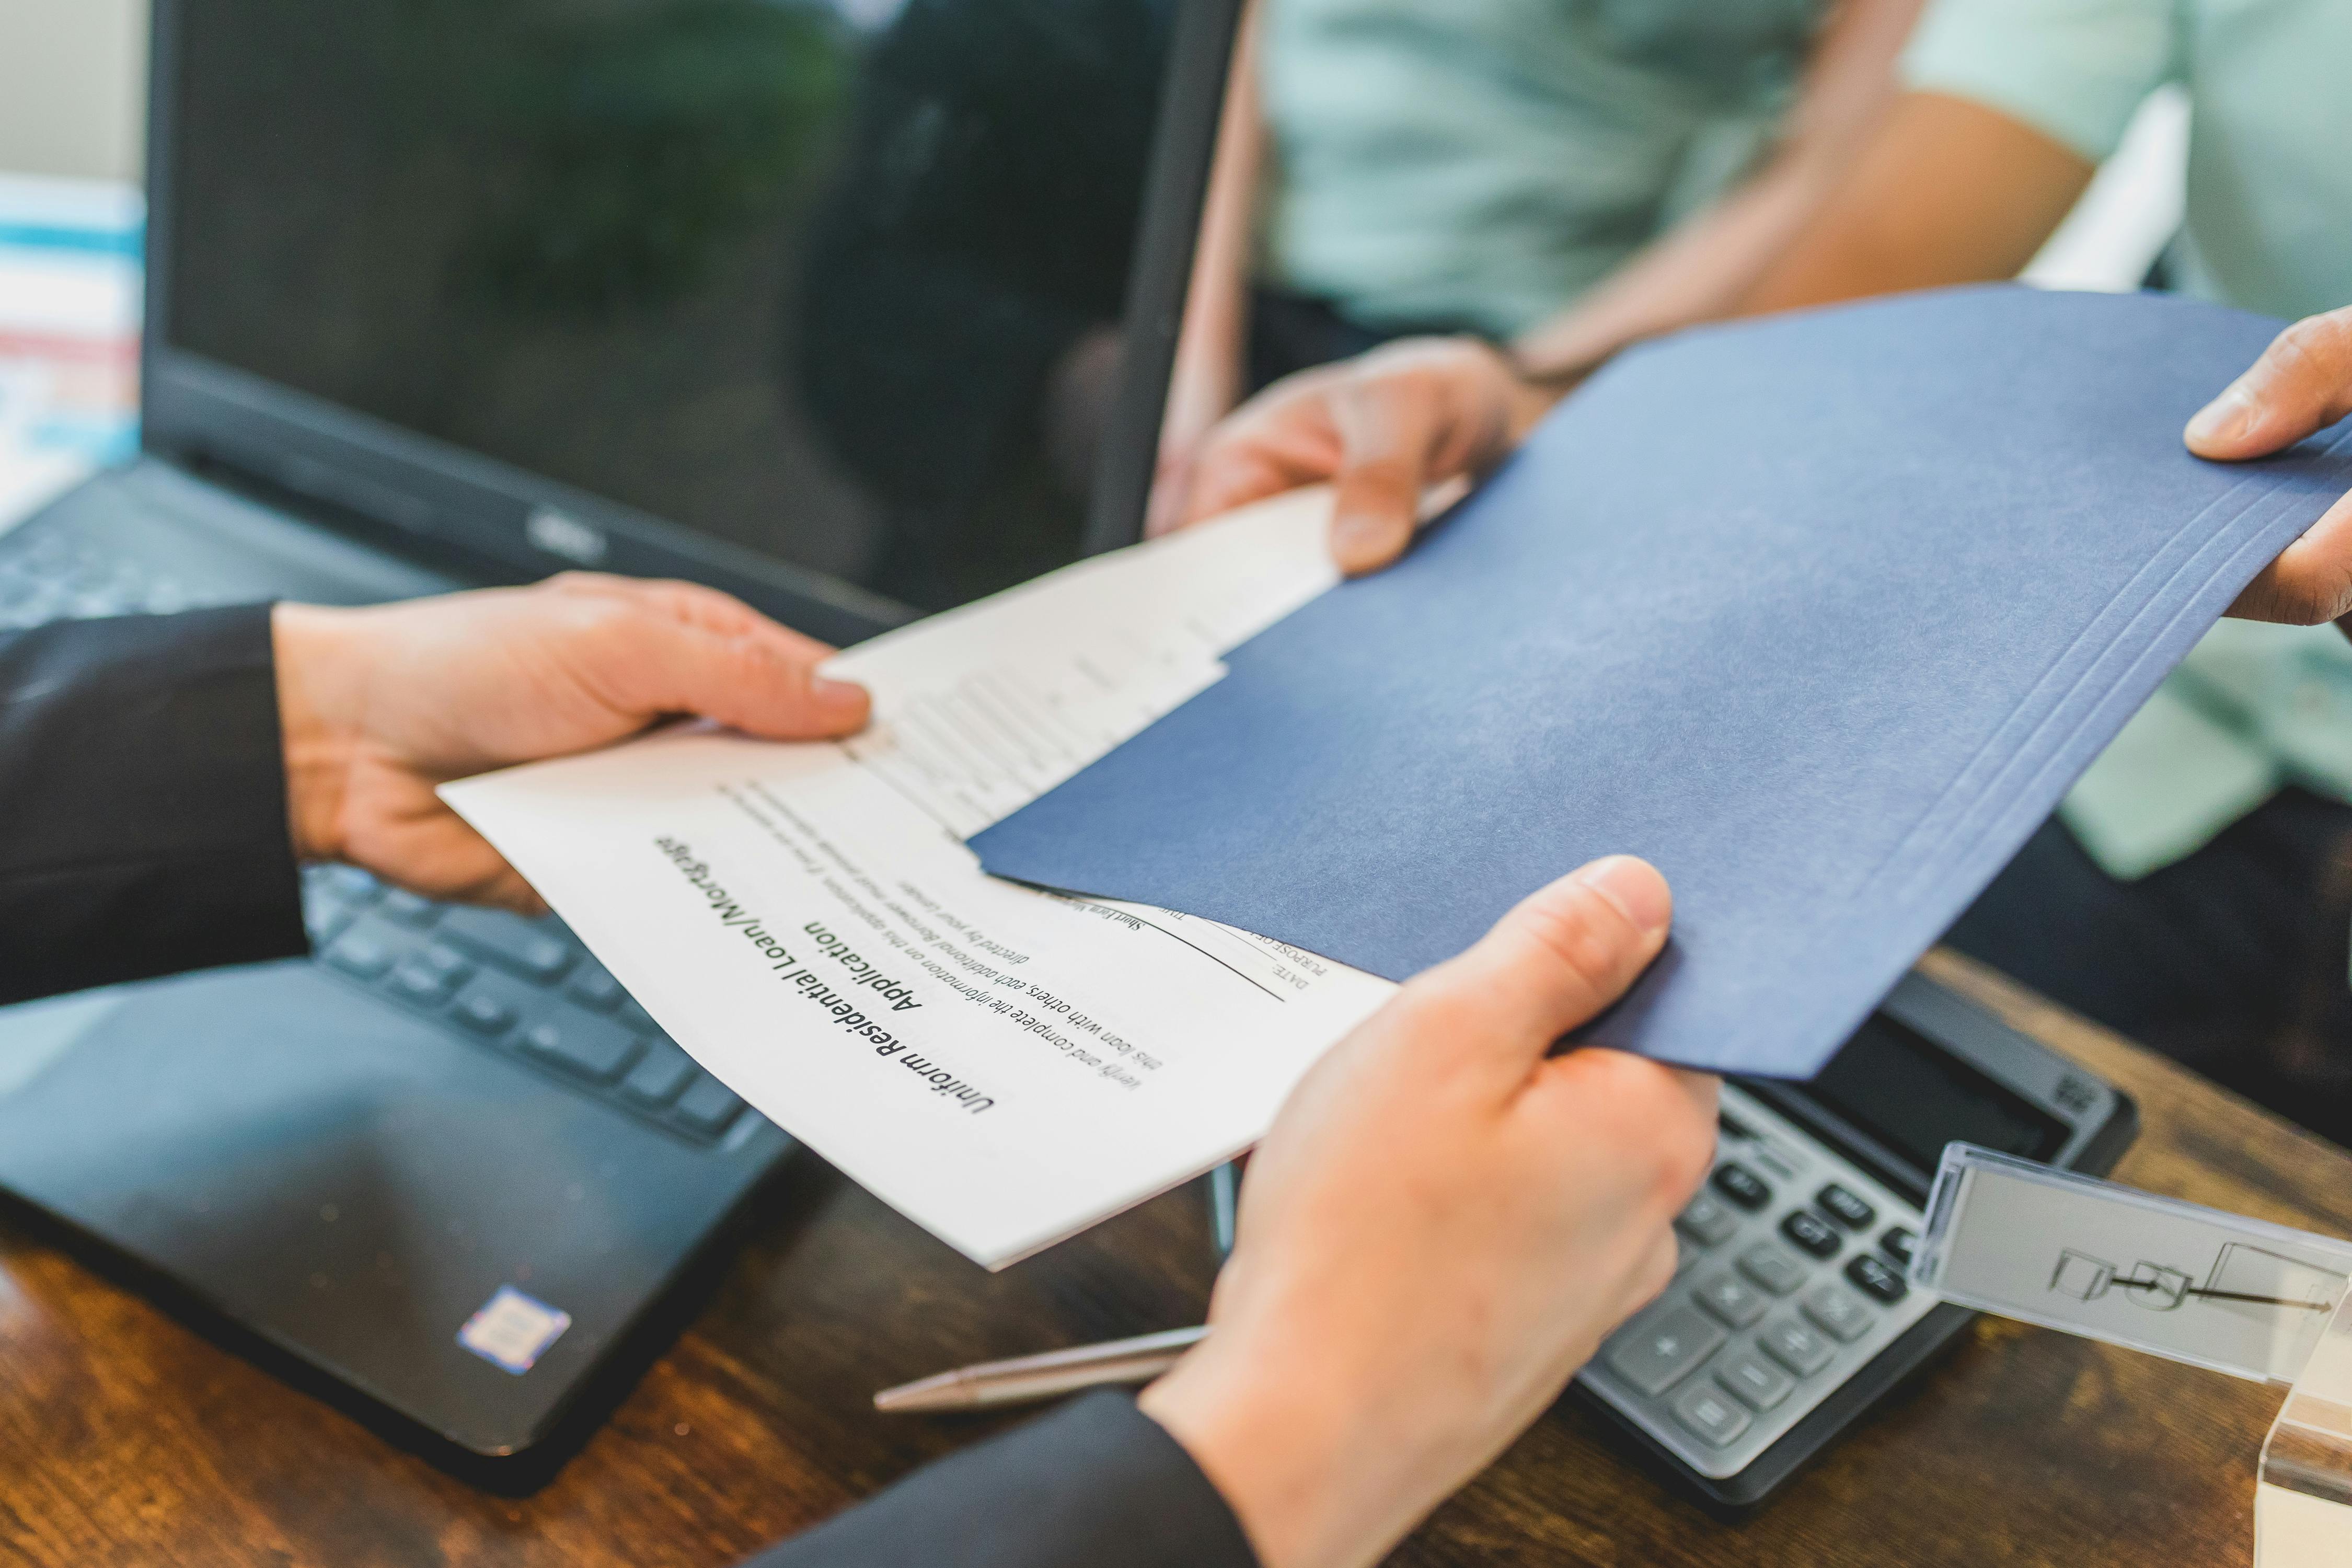
Real estate agent giving a printed document to a buyer
Image via Pexels

Paperwork Survival Guide for Buying or Selling a Home (Without Losing Your Mind)

Home real estate paperwork involves a lot of moving parts: lenders, escrow or closing agents, inspectors, appraisers, agents, and you. The fastest way for things to go sideways is when a document goes missing, a version gets mixed up, or a deadline sneaks past while you're searching your inbox. A little structure early can save you hours later, and can prevent stressful "we need this today" surprises.

The quick version you can actually use

Create one "home transaction" folder (digital and physical) the day you start touring or listing. Rename files consistently so you can spot the latest version at a glance. Then set a simple weekly routine: download new docs, file them, and write down what action (if any) each document requires.

Start with a simple filing routine and stick to it

Document category Common examples Why it matters Where to store it
Offer & contract Purchase agreement, addenda, counteroffers Locks in price, contingencies, timelines "01_Contract" folder + a printed copy
Disclosures Seller disclosures, HOA docs, lead-based paint form Reveals risks, rules, fees "02_Disclosures" folder
Loan & financing Loan Estimate, pay stubs, bank statements Approvals and final loan terms "03_Loan" folder (tight access)
Inspections & repairs Inspection report, repair requests, receipts Negotiations + future reference "04_Inspection_Repairs" folder
Closing Closing Disclosure, settlement statement, deed, policies Final costs, ownership, coverage "05_Closing" folder + fire-safe copy

(For many buyers, the Loan Estimate and Closing Disclosure are two of the most important forms to review carefully during the process.)

Keeping your documents organized digitally (and actually accessible)

A digital system is only helpful if you can open what you saved, from anywhere, when it counts. For major text or formatting edits (like rewriting a letter, cleaning up an explanation, or updating a document you drafted), it can be easier to work in Microsoft Word first, especially if editing the PDF directly is limited. Once your edits are done in Word, you can convert the file to PDF using an online conversion tool. This is a good option to consider because it lets you upload your Word document, convert it, and then save it as a PDF.

How-to: Set up a "no-hunt" system in 20 minutes

This is the part most people skip, until they’re stressed.

  1. Create one master folder: Home_2026_MainSt_Buy (or your address + "Sell").
  2. Make subfolders using numbers (so they sort in order): 01_Contract, 02_Disclosures, etc.
  3. Pick a file naming rule and use it every time: YYYY-MM-DD_DocType_Source_V1 (example: 2026-02-12_LoanEstimate_Lender_V2.pdf)
  4. Create a running "Action Notes" doc (one page) with: document received date → what it is → what you must do → deadline.
  5. Protect the sensitive folder (loan docs, IDs): use a password-protected drive or at least restricted sharing permissions.
  6. Add a calendar reminder twice a week: "Download + file new home docs (10 min)."

Paperwork questions people ask mid-transaction

What should I keep after closing?

Keep everything you signed, the final closing documents, insurance policies, receipts for repairs, and warranty info. If you ever refinance, file a claim, or sell later, these come back.

Do I really need printed copies?

Not for everything. But it's smart to keep a small physical set: the signed contract, final closing docs, and any item your lender or agent flags as "must retain."

How do I avoid sending the wrong version?

Use one naming rule, and before you send, confirm the date + version number in the filename. If you're collaborating, store files in one shared location and avoid "email-only" document management.

What if I'm both buying and selling at the same time?

Split folders by address (or "Buy" and "Sell") and keep separate "Action Notes" docs. The paperwork is similar, but timelines and responsibilities differ.

A reliable extra resource worth bookmarking

If you want a grounded, plain-language guide to the closing stage, the Consumer Financial Protection Bureau (CFPB) has a Mortgage Closing Checklist you can download and use to track what to review and bring to closing. It's especially handy if you feel like you're signing a mountain of forms and want a structured way to sanity-check the process. It also pairs well with the CFPB's broader "Buying a House" tools, which walk through the journey step by step. CFPB resources are written for consumers (not industry insiders), so they're easier to skim when you're tired.

Conclusion

Paperwork doesn't have to be the scary part of buying or selling a home. Confusion does. If you label documents clearly, store them in consistent folders, and track deadlines in one place, you'll spend less time searching and more time making good decisions. Keep your "Action Notes" updated, and don't be afraid to ask a pro to clarify what a document is for before you sign. Most importantly, make organizing digital documents a routine, not a rescue mission.

Posted in Topic Of Interest
Feb. 26, 2026

Trump Executive Order: Is the Wall Street Housing Ban a "Toothless Tiger"?


Trump Executive Order: The "Wall Street Ban" That Isn't

Published: February 26, 2026 | By: Your Name

TL;DR: The 30-Second Reality Check
  • The HUD Re-Run: The "new" 15-day head start for families is a recycled policy that has existed for years.
  • The BTR Loophole: The order explicitly exempts "Build-to-Rent" properties, Wall Street's favorite new strategy.
  • No Private Power: The President cannot legally ban cash sales in the private market without Congress.
  • The Verdict: It’s a masterclass in political optics, not a solution to the housing crisis.

The headlines were a populist dream: "White House Stops Wall Street from Buying Your Neighborhood." For a nation exhausted by bidding wars, the January 20th Trump Executive Order felt like a long-awaited cavalry charge.

But peel back the rhetoric, and you don't find a ban. You find a "re-run."

1. The HUD "First-Look" Mirage

The centerpiece of this Order is the "First-Look" window. Problem is, HUD has been doing this for a decade. In May 2025, HUD actually reverted this window from 30 days back to 15 because it failed to help families win bids. The EO treats this failing policy as a revolutionary breakthrough.

2. The "Build-to-Rent" Greenlight

Section 3(b) contains an explicit carve-out for properties Exempted "constructed as rental communities." Wall Street giants like Blackstone are already shifting to this model. The administration isn’t stopping corporatization; they are literally handing them the roadmap.

3. The "Cash is King" Problem

This order targets federal programs (FHA, VA, Fannie Mae). But institutional buyers show up with billions in cash. Since a President can't unilaterally rewrite private contract law, the buyers who actually dominate the market will barely feel a speed bump.


What Would "Actual Teeth" Look Like?

  • Eliminating tax depreciation for mega-portfolios (50+ units).
  • Closing the BTR loophole entirely.
  • Mandating "First-Look" windows for the private MLS market.

The Trump Executive Order identifies a real villain but brings a wet noodle to a gunfight. Until we get legislation with actual teeth, Wall Street isn't leaving the neighborhood. It's just updating its paperwork.

© 2026 Your Blog Name. All rights reserved. Focused on housing policy and economic transparency.

Posted in Topic Of Interest