Area Real Estate News & Market Trends

You’ll find our blog to be a wealth of information, covering everything from local market statistics and home values to community happenings. That’s because we care about the community and want to help you find your place in it. Please reach out if you have any questions at all. We’d love to talk with you!

June 12, 2026

Clermont, Florida: Who It Fits, and Who Should Look Elsewhere

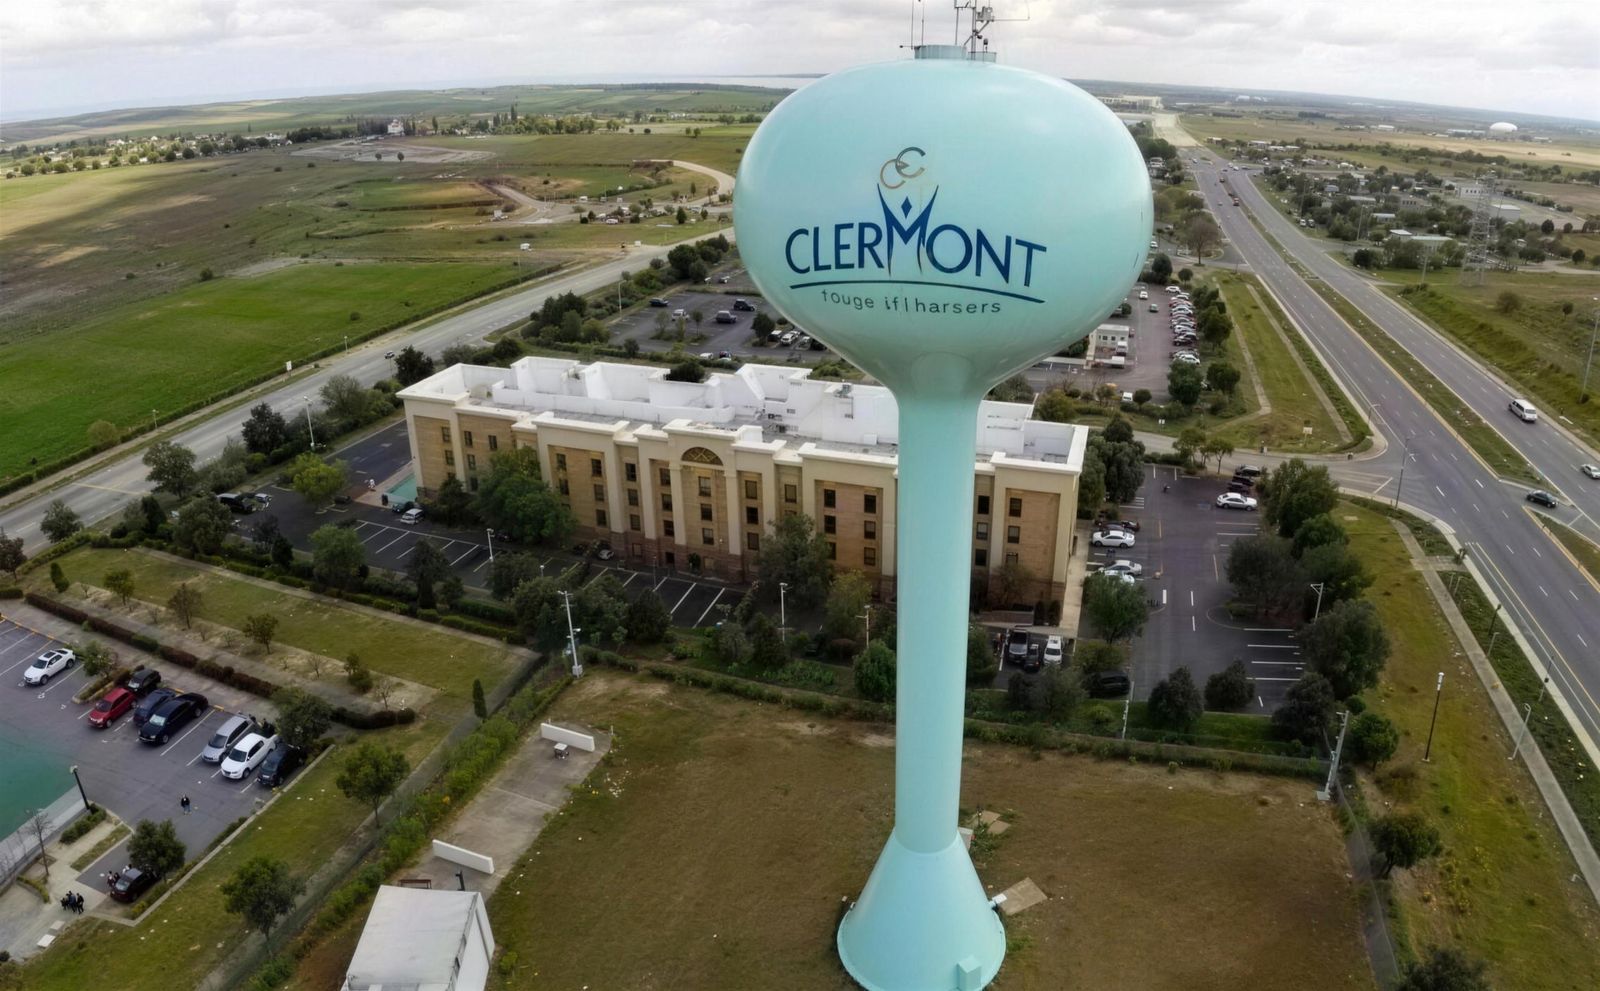
Aerial view of the Clermont FL water tower overlooking US-27 in Lake County, Florida
The Clermont water tower along US-27, landmark of Lake County's fastest-growing city.

Short answer: Clermont is where Central Florida buyers go when they want more home for the money without leaving the Orlando metro. It sits about 22 miles west of downtown Orlando in Lake County's hill-and-lake country (yes, Florida has hills here) with a median sale price of $450,000, a walkable lakefront downtown, and some of the fastest population growth in the region. Below is what I tell my own buyers about living in Clermont in 2026: prices, neighborhoods, schools, the commute, and how it stacks up against Winter Garden next door.

$450K
Median Sale Price
July 2026, 199 closed sales. Twelve-month median $440,340, down 3.2%
~48,000
Population
U.S. Census 2024 estimate, nearly tripled since 2000
675
Active Listings
Active residential listings in Clermont, August 30, 2026
22 mi
To Downtown Orlando
Via SR-50 or the Turnpike; SR-429 serves the attractions corridor
TLDR:
  • It's the value play of the west Orlando metro: more square footage and bigger lots than Winter Garden, in exchange for a slightly longer commute.
  • Clermont's median sale price over the last twelve months is $440,340, down 3.2% against the year before, and the typical home went under contract in 39 days.
  • The landscape is genuinely different, rolling hills, the Clermont Chain of Lakes, and a waterfront downtown with the South Lake Trail running through it.
  • Growth is the trade-off: one of Central Florida's fastest-growing cities means new construction everywhere and building traffic on US-27 and SR-50.
  • Lake County Schools serves the city; zoning shifts as new schools open, so verify the zoned schools for any specific address before you offer.

Who Clermont Fits, and Who It Doesn't

Strong fit: families prioritizing space and budget; active adults (the 55+ inventory is deep and varied); outdoor enthusiasts; remote and hybrid workers who only fight the commute a few days a week; relocation buyers who want newer construction without Osceola-corridor congestion.

Weaker fit: daily downtown-Orlando commuters who hate driving; buyers who want a mature, fully built-out area, Clermont will be under construction for years; nightlife-first households.

Still deciding between towns? We pulled every closed sale between $446,500 and $503,500 in Clermont, Winter Garden and Minneola over the last 12 months and put them side by side: what $475,000 actually buys in each. Square footage, bedrooms, year built, and how many came with a pool.

Where Is Clermont, and What Makes It Different?

Clermont anchors south Lake County, about 22 miles west of downtown Orlando along SR-50 and US-27. Unlike most of flat Central Florida, Clermont sits in genuine hill country, the area around Sugarloaf Mountain is among the highest terrain in peninsular Florida, which is why you'll see cyclists and triathletes training on these roads year-round. The city wraps around the Clermont Chain of Lakes, with Waterfront Park and the historic Citrus Tower as its landmarks.

According to the U.S. Census Bureau, Clermont's population is roughly 48,000 and has nearly tripled since 2000, one of the fastest growth trajectories in Central Florida. That growth is the single most important thing to understand about living here: it brings new shopping, restaurants, and medical facilities every year, and it also brings construction and traffic.

Clermont Housing Market Snapshot (2026)

To see what is actually on the market rather than what has already sold, browse homes for sale in Clermont, which updates with current inventory.

Is Clermont a buyer's or seller's market right now? We answer that from current MLS data, weighing months of supply and how close sellers get to their original asking price against the four counties: Is Clermont a buyer's or seller's market?

Over the last twelve months 1,937 homes sold in Clermont at a median of $440,340, down 3.2% against the twelve months before. In July 2026 the median was $450,000 across 199 closed sales, and the typical home went under contract in 39 days. There are 675 active residential listings in the city as of August 30, 2026. That combination, flat prices, rising inventory, longer market times, is the same buyer-leaning pattern we're tracking across all four counties we serve, and it mirrors the broader trend in our Central Florida housing market hub.

For buyers, that means negotiating room. A meaningful share of Clermont listings have already taken at least one price cut, you can browse the current price-reduced homes in Lake County to see where sellers are adjusting. With mortgage rates still elevated by historical standards (track the current average via Freddie Mac's weekly Primary Mortgage Market Survey), sellers who price at 2022 levels sit; sellers who price to today's market move.

Rough price tiers as of mid-2026:

Segment Typical Range Notes
Condos & townhomes $200K to $350K Entry point; strongest fit for first-time buyers and downsizers
Established single-family $350K to $475K The heart of the market; 1990s to 2010s communities
New construction $400K to $550K+ Heavy builder activity along the US-27 corridor
Lakefront & premium $500K to $1M+ Chain of Lakes access, Lake Louisa area, golf communities

Best Neighborhoods in Clermont, FL: Communities to Know

  • Kings Ridge, established 55+ golf community; one of the most affordable ways into Clermont, with most homes well under the city median.
  • Summit Greens, gated 55+ community with clubhouse amenities, close to shopping on SR-50.
  • Heritage Hills, Mediterranean-style 55+ community in the hills south of SR-50.
  • Lake Louisa corridor, south Clermont near Lake Louisa State Park; newer communities and some of the city's premium price points.
  • Downtown / Waterfront district, older character homes within walking distance of Waterfront Park, the South Lake Trail, and the farmers market.
  • US-27 new-construction corridor, the growth engine; multiple active builder communities heading south toward Four Corners.

Note for 55+ shoppers: Clermont has an unusually deep bench of active-adult communities for a city its size, it's worth comparing two or three before committing, because HOA fees and amenity packages vary widely.

Clermont vs. Winter Garden: The Honest Comparison

This is the question I hear most from west-side buyers. The two cities are 15 minutes apart but compete for the same families.

  Clermont (Lake County) Winter Garden (Orange County)
Price for equivalent home Lower, more square footage and lot for the budget Higher, you pay a premium for location
Downtown Lakefront, trail-connected, growing restaurant scene Plant Street, the benchmark downtown in the west metro
Commute to Orlando Longer; SR-50 or Turnpike Shorter; SR-429 direct
Landscape Hills, chain of lakes, state park Flatter, master-planned (Horizon West)
School district Lake County Schools Orange County Public Schools
Best fit Value, space, outdoor lifestyle, 55+ options Walkable downtown premium, shortest commute

My plain-English version: if the Plant Street lifestyle and a shorter commute are worth roughly a county-line price premium to you, Winter Garden wins. If you'd rather put that premium into the house itself, or into a lake view, Clermont wins.

Schools, Commute, and Day-to-Day Life

Schools: Clermont is served by Lake County Schools. Because the city is growing fast, attendance zones shift as new schools open, verify the current zoned schools for any specific address directly with the district before you write an offer. We do this as a standard step for every buyer we represent here.

Commute: Downtown Orlando runs 35 to 50 minutes in rush hour via SR-50 or the Turnpike. The Disney/attractions corridor is typically 25 to 35 minutes south on US-27. SR-429 access on the east side of the area has meaningfully improved trips to Winter Garden, the airport, and the parks.

Lifestyle: This is Clermont's quiet superpower. The South Lake Trail connects downtown to the West Orange Trail network, Waterfront Park hosts triathlons and the weekly farmers market, Lake Louisa State Park offers 4,500+ acres of trails and paddling, and the National Training Center draws amateur and professional athletes. If your weekends involve a bike, a paddleboard, or running shoes, very little in the Orlando metro competes.

Is Clermont, FL Safe?

Clermont's reported violent crime rate for 2023 was 188.9 offenses per 100,000 residents, against 280.8 for Florida as a whole. Property crime ran the other direction, at 1,637.6 per 100,000 against the state's 1,330.2.

Those two numbers together are the honest answer. Violent crime in Clermont runs 32.73% below the Florida rate, while property crime runs 23.11% above it. In practical terms that points at theft from unlocked vehicles, package and garage theft, and job-site theft in the newer communities that are still building out, rather than at violence. If you are moving here, the habit worth bringing is closing the garage and locking the car, not avoiding a part of town.

Figures are reported offenses from the FBI Crime Data Explorer for the Clermont Police Department (ORI FL0350300), for 2023, which is the most recent year the department reported all twelve months. The 2024 file was still incomplete when this was written, so a single-year comparison is the fairest read available.

Cost of Living in Clermont, FL

Housing is the line that actually moves a Central Florida budget, and Clermont is not the inexpensive part of Lake County. Across 675 active residential listings on August 30, 2026, the median asking price was $469,900, or $224 per square foot. Lake County as a whole sits at $389,900 and $206.

That is a 20.52% premium over its own county on price, and 8.74% on a per square foot basis. What the premium buys is the elevation and the chain of lakes, newer construction on the south and west sides, and a shorter run to the Turnpike and SR-429 than most of Lake County can offer.

Florida charges no state income tax, so in a Florida budget the property tax line matters more than it would elsewhere, and a homestead exemption reduces the taxable value of a primary residence. Millage varies by taxing district inside Clermont, so treat any single quoted rate as an estimate until the specific parcel is checked.

Frequently Asked Questions

Is Clermont, FL a good place to live?

Yes, Clermont offers more home for the money than most of the Orlando metro, with rolling hills, a chain of lakes, a walkable waterfront, and a roughly 22-mile commute to downtown Orlando. The trade-off is growth: it is one of the fastest-growing cities in Central Florida, so traffic on US-27 and SR-50 is increasing as new communities build out.

What is the median home price in Clermont, FL?

Over the last twelve months 1,937 homes sold in Clermont at a median of $440,340, down 3.2% against the twelve months before. In July 2026 the median was $450,000 across 199 closed sales. Condos and townhomes sell well below that figure, while lakefront and golf-course communities run higher.

Is Clermont cheaper than Winter Garden?

Generally yes. Clermont sits in Lake County and typically offers a lower price per square foot and larger lots than neighboring Winter Garden in Orange County. Winter Garden buyers pay a premium for the Plant Street downtown district and a shorter commute to Orlando; Clermont buyers get more house, hills, and lake access for the same budget.

How far is Clermont from Orlando and the theme parks?

Clermont is about 22 miles west of downtown Orlando via SR-50 or the Florida Turnpike, and roughly 25-35 minutes to the Disney World area via US-27 south depending on traffic. The SR-429 expressway on the east side of the area shortens trips to Winter Garden, the airport corridor, and the attractions.

What school district serves Clermont, FL?

Clermont is served by Lake County Schools. School zoning varies by neighborhood and changes as new schools open in this fast-growing area, so verify the current zoned schools for any specific address directly with Lake County Schools before you buy.

Is Clermont, FL safe?

Violent crime is low here and property crime is not. For 2023, the most recent year with complete reporting, Clermont's violent crime rate was 32.73% below the Florida average while its property crime rate was 23.11% above it, per the FBI Crime Data Explorer. The realistic risk is vehicle, package and job-site theft rather than violence.

What is the cost of living in Clermont, FL?

Housing is the deciding line. Clermont's median asking price is $469,900 against $389,900 for Lake County, a 20.52% premium, and Florida charges no state income tax, which shifts the weight in a household budget onto the property tax line.

Thinking About a Move to Clermont?

If you are weighing Clermont against a neighbouring town on the same budget, start with the numbers: what $475,000 buys in Clermont, Winter Garden and Minneola, built from closed MLS sales and refreshed quarterly.

Comparing Clermont against the north side of the metro? Our Living in Lake Mary guide covers the same ground in Seminole County, including how its prices and school zoning actually work.

I'm Brenden Rendo, Realtor with The Homes In Orlando Team at NextHome Neighborhood Realty, and our team works Lake, Orange, Seminole, and Volusia counties every week, including the weekly price-reduction data that tells us exactly where Clermont sellers are negotiating. If you want a straight answer on what your budget actually buys here versus Winter Garden or anywhere else in the four-county area, call or text 407-616-9019 or reach out through homesinorlando.forsale.

Browse current price-reduced homes in Lake County to see where the deals are this week.
May 30, 2026

Orlando Home Insurance 2026: Citizens Rate Cut, 20 New Carriers & How to Lower Your Bill

If your homeowners insurance bill went up this year, you're not alone. According to a recent Pew Research Center survey, 71% of U.S. homeowners say their insurance costs have climbed over the past few years — and 42% say they've gone up "a lot." But here in Central Florida, I'm actually seeing something most of the country isn't: the start of real relief. Let me walk through both sides — the national trend, and the local news that means Orlando homeowners have more leverage than the headlines suggest.

71%
U.S. Homeowners Say Insurance Is Up
42% say it's gone up "a lot" (Pew Research, May 2026)
$3,303
Avg. Annual Premium Nationally
Up 24% ($648/yr) since 2021 (Consumer Federation of America)
−8.7%
Citizens Statewide Rate Cut for 2026
Homeowners multiperil −8.8%, effective July 1 (Citizens, OIR-approved)
17
New Carriers Entered Florida
Since 2022–23 reforms (FL Office of Insurance Regulation)
TLDR:
  • Nationally, premiums are up 24% since 2021 to an average $3,303/year — but Florida is bucking the trend.
  • Citizens' OIR-approved 2026 rates drop a statewide average of 8.7% (homeowners multiperil −8.8%, effective July 1), and 17 new carriers have entered the Florida market since the 2022–23 reforms.
  • An up-to-date wind mitigation report (renews every 5 years) is the single biggest discount lever for Florida homeowners.
  • Shop your policy every year, raise your deductible, bundle, and ask about mitigation discounts.
  • Never just drop coverage — raise the deductible or shop aggressively instead.

Why Premiums Climbed So Fast Nationally

The short version: insurers have been paying out a lot more in claims, and they pass that cost on. According to the Consumer Federation of America, the average annual home insurance premium has climbed 24% since 2021, reaching $3,303 — twice the rate of inflation over the same period. The typical homeowner now pays $648 more per year than they did four years ago, and premiums rose in 95% of U.S. ZIP codes between 2021 and 2024.

The main culprits are severe weather and rising rebuilding costs. More frequent storms, wildfires, floods, and hail mean more claims — and when those claims get paid, labor and materials cost far more than they did a few years ago. Insurers are recalibrating.

What's Different in Florida Right Now

For years, Florida was the poster child for unaffordable insurance — and plenty of the "moving to Florida" chatter online still claims you'll pay $20,000 a year or can't get covered at all. That's just not the reality on the ground anymore. Two things have shifted in our favor:

Citizens cut rates statewide. Citizens Property Insurance — the state-backed insurer a lot of Central Florida homeowners are still on — has OIR-approved 2026 rates that drop a statewide average of 8.7%, with homeowners multiperil policies down about 8.8% and every personal-lines policyholder getting at least a 2% cut. The new rates take effect July 1 for new policies and apply to existing ones at renewal. When I'm working with a buyer who's $20 over their monthly budget, a cut like that can be the difference that gets them into the home.

Seventeen new carriers entered the market. A couple of years ago there were barely any choices. Since the 2022–23 reforms, 17 new insurance carriers have entered Florida per the state Office of Insurance Regulation — driven partly by reform (including the changes around roof claims) and partly by a stretch of calmer storm seasons. More competition typically means lower rates and better coverage, and it gives you real options when it's time to shop.

What's Probably Driving Your Specific Bill

The national average tells you the trend, but your premium depends on factors specific to you and your home. The biggest ones insurers look at:

  • Where your home is located. Proximity to flood zones, storm-prone coastline, or a high-crime ZIP code pushes your rate up.
  • Your home's age and construction. Older roofs, wiring, and plumbing cost more to insure. Upgrades can sometimes lower your rate.
  • Your roof. In Florida, roof age and installation are a huge factor — which is exactly why the wind mitigation report below matters so much.
  • Your claims history. Filing claims, even small ones, can raise your renewal. Insurers also look at the property's claim history, not just yours.
  • Your credit score. In most states, including Florida, insurers can factor in credit. A strong score works in your favor.
  • Your coverage limits and deductible. Higher limits and lower deductibles both mean a higher premium.

6 Things Orlando Homeowners Can Do Right Now

1. Update your wind mitigation report.

This is the most overlooked discount in Florida — and often the biggest. A wind mitigation inspection documents your roof's age, how it was installed, and other storm-resistant features, and insurers use it to knock down your premium. The report is good for five years, and the inspection runs about $100 to $125. Here's a real example from this year: my own renewal came in around $3,200. I sent it to my agent at College Park Insurance, he found the same coverage through an A-rated carrier — contingent on a fresh wind mitigation inspection — and brought it down to roughly $2,100. That's about $1,000 saved for the cost of one inspection. If you haven't done yours in five years, call your agent today and ask whether you're still getting the wind mitigation discount.

2. Shop your policy every single year.

Loyalty doesn't get rewarded in this market. With 17 new carriers in Florida, there's more to shop than there's been in years. The whole process takes about five minutes on your end — scan your renewal notice, email it to a good independent agent, and let them do the legwork. That's literally what I did to find the $1,100 in savings above. Get a couple of competing quotes at renewal and don't assume your current carrier is still the best deal.

3. If you're on Citizens, confirm your rate cut.

With the statewide Citizens decrease rolling out, make sure your renewal actually reflects it — and use it as a prompt to compare against the newer private carriers, who may be able to beat it with better coverage.

4. Raise your deductible.

If you can comfortably cover a higher out-of-pocket cost on a claim, raising your deductible from $1,000 to $2,500 or even $5,000 can significantly lower your annual premium. Think of it as self-insuring the small losses and keeping coverage for the big ones.

5. Ask about mitigation and bundling discounts.

Beyond wind mitigation, many insurers discount for a new roof, storm shutters, an updated electrical panel, a monitored security system, or a whole-home generator. Bundling home and auto under one carrier usually adds a discount too. These aren't always advertised — call and ask specifically.

6. Review your coverage limits.

If your home's value has shifted, your limits may be out of sync. You don't want to be underinsured in a major loss — but you also don't want to pay to insure a higher rebuild cost than your home requires. And don't set it and forget it: every year or two, check whether anything changed (an addition, a new boat, a renovation) so your coverage still fits.

A Note on Dropping Coverage

When the bill goes up, the temptation to drop or gut your policy is real. According to CNBC, more than one in four homeowners say they'd drop coverage if they could. That's understandable — but it's one of the riskiest moves a homeowner can make.

A single storm, fire, or burst pipe can cost tens of thousands out of pocket. If you have a mortgage, your lender almost certainly requires coverage — and if you let it lapse, they'll add "force-placed insurance," which is typically far more expensive and far less comprehensive than a policy you'd choose yourself. If the cost is genuinely unmanageable, the better path is to update your wind mitigation, raise your deductible, trim optional riders, and shop aggressively. Dropping coverage entirely only defers a much bigger potential cost.

You Have More Leverage Than You Think

The national picture is frustrating, but Central Florida homeowners are in a better spot than most of the country right now — rates are softening, carriers are competing, and the wind mitigation discount is sitting there waiting to be claimed. Pick one thing from this list and act on it before your next renewal. Even shopping your rate once a year puts you ahead of most homeowners.

Whether you're buying, selling, or just trying to make your current home more affordable to own, the cost of insurance is part of the bigger picture across Orange, Seminole, Volusia, and Lake counties. If you'd like a referral to a trusted local insurance agent — or you're thinking about your next move in the Central Florida market — I'm happy to help.

Have questions about buying or selling in Orlando, or want a local insurance referral? Reach out to Brenden Rendo and The Homes In Orlando Team at 407-616-9019 or visit homesinorlando.forsale.

May 28, 2026

Orlando Real Estate Week of May 28, 2026: Hometown Heroes Returns, Citizens Cuts Rates, Pending Sales +5.7%

If you've been waiting on the sidelines because of the down payment or the insurance bill, this is the week the news started moving in your favor. Three big positive stories landed at the same time, and they stack on top of each other: Tallahassee funded the down payment help buyers have been asking for, Citizens Property Insurance is recommending its first rate cut in eleven years, and Orlando just posted the cleanest balance signal we've seen in a year.

$50M
New Hometown Heroes Funding
Included in the $115B FL budget heading for a Friday vote (May 2026)
2.6%
Citizens Statewide Rate Cut
First rate decrease recommendation since 2015; ~$359/yr savings for 60% of policyholders
+5.7%
Orlando New Pending Sales YoY
April Orlando MSA single-family: buyers are signing again
6.47%
30-Yr Fixed Mortgage Rate
Down from 6.6% two weeks ago, softening as the budget and insurance news lands
TLDR:
  • Down payment help is being refunded. The Florida budget heading for a Friday vote includes $50M in fresh Hometown Heroes funding, plus full SHIP ($165.7M) and SAIL ($70.8M) funding, and $405M+ for My Safe Florida Home and Condo programs.
  • Insurance is finally a positive talking point. Citizens Property Insurance is recommending a 2.6% statewide rate decrease, the first cut since 2015. Twenty new insurers have entered Florida since the 2022 reforms with over $850M in new capital.
  • Orlando is balanced and demand is back. April new pending sales jumped +5.7% YoY across the Orlando MSA. Active inventory tightened 4.4%. Median price held essentially flat at $440K.
  • Mortgage rates are softening. 30-year fixed sits at ~6.47%, down from 6.6% two weeks ago. 15-year fixed at 5.85% is a strong tool for move-up sellers using equity.
  • Three actions this week: Buyers: call your lender about Hometown Heroes eligibility. Sellers: re-shop your homeowner's insurance. Both: if you've been waiting for things to settle, they just did.

Florida Just Funded the Help Buyers Have Been Asking For

House and Senate leaders agreed late Sunday on a $115 billion state budget. The final vote is Friday, then it goes to Governor DeSantis. For our buyers and sellers, three line items matter most:

  • $50 million in additional funding for the Hometown Heroes Housing Program: down payment and closing cost help for eligible Florida workers including teachers, nurses, first responders, hospitality workers, and many more.
  • $165.7 million in full funding for SHIP (State Housing Initiatives Partnership), which flows to counties and cities to help working families buy and rehab homes.
  • $70.8 million in full funding for SAIL (State Apartment Incentive Loan): workforce rental development.

On top of that, over $405 million in unused funds is being reappropriated to My Safe Florida Home and the new My Safe Florida Condominium program: money homeowners can use to harden roofs, windows, and openings, which often lowers the insurance premium.

Why this matters for Orlando specifically

Hometown Heroes has been one of the most-used down payment programs in Florida. Orlando-area Realtors saw a huge volume of these loans in 2024-2025 before the money ran out. Refunding it means buyers who got priced out in March or April can come back to the table this summer with up to 5% of the loan amount (capped) for down payment and closing costs.

Pair this with the Citizens insurance news in the next section and we are looking at the best affordability cocktail in two years.

What to do this week

  • If you qualify as a "Hometown Hero" (and the eligibility list goes well beyond first responders), call your lender now and ask them to flag your file for the new tranche of funds.
  • If you own a home that needs roof, window, or door upgrades, get on the My Safe Florida Home inspection list early. These slots filled up fast last year.

Source: Florida Realtors: "Florida budget heads to vote with housing funds included" (May 26, 2026).

Insurance: The Story That Finally Turned the Corner

Citizens Property Insurance is recommending a 2.6% statewide average rate decrease for 2026. This is the first cut since 2015. Read that again: first cut in eleven years.

Three out of five Citizens policyholders will see an average 11.5% reduction, roughly $359 back in their pocket per year.

And it gets better

  • Citizens' policy count has dropped 76% from peak down to about 336,000 policies: policies are migrating back to the private market, which is exactly what we've been waiting for.
  • Florida's Office of Insurance Regulation just confirmed three more property and casualty insurers entered the market this week, bringing the total since the 2022 reforms to 20 new entrants and over $850 million in new capital.
  • The new entrants: Builder Reciprocal Insurance Exchange, Frontline Insurance Reciprocal Exchange, and Wingsail Insurance Company.
  • More insurers are also writing condo association wind-only policies in coastal counties (Miami-Dade, Broward, Palm Beach), which matters for coastal investor clients.

Why this is the talking point of the year

For a decade, "Florida insurance" was the conversation killer at every listing appointment. That conversation is now actually a positive. Lead with this number with nervous out-of-state buyers: the regulator is recommending the first rate cut in eleven years, and twenty new companies have entered the market since 2022.

Tactical note for buyers under contract

Have your insurance agent quote both renewal and a fresh shop: rates are moving fast and the best deal isn't always with your current carrier anymore.

Sources: Citizens Property Insurance 2026 Rate Filing • Governor DeSantis insurance press release.

The Orlando Market Pulse

April Orlando MSA snapshot (single-family)

Orlando-Kissimmee-Sanford MSA, from Florida Realtors / Stellar MLS:

Metric April 2026 YoY Change
Closed sales 2,534 -3.1%
Median sale price $440,000 -0.7% (essentially flat)
Active inventory 9,652 -4.4% (tightening, not flooding)
Dollar volume $1.4 billion -
New listings 3,688 -5.2% (measured, not panicked)
New pending sales 3,001 +5.7% (the headline number)

The picture in one sentence: Inventory is shrinking, pending sales are up almost 6%, and prices are holding within a percent of last year. That is the definition of a healthy, balanced market, not a falling one.

Latest weekly ORRA pulse (May 17-23, single-family)

  • 388 single-family closings across the ORRA reporting region in one week.
  • 3,744 new pending sales: buyers are clearly active.
  • 625 new listings added.

Median single-family prices by county:

County Median Price
Seminole $522,500
Orange $506,800
Lake $397,000
Volusia $339,500

Days on market range from 62 days in Seminole up to the high 80s in outer counties. The fastest-moving counties are closest to the urban core, which is the pattern we'd expect in a balancing market.

Condo and townhouse pulse (May 17-23)

  • 119 condo closings for the week, 927 new pending sales, 211 new listings.
  • Median condo prices: Volusia $342K, Lake $330K, Orange $300.9K, Seminole $230.5K.
  • Statewide context: Florida condo sales jumped +7% YoY in April and pending condo contracts were up ~15%: a real shift after the post-Surfside slowdown.

Mortgage rate check

  • 30-year fixed today: ~6.47% (Mortgage News Daily), down from 6.6% two weeks ago.
  • 15-year fixed: 5.85%: strong tool for buyers with cash or move-up sellers using equity.
  • Bottom line: rates are softening just as the budget and insurance news hits. That is a window.

Source: Orlando Regional REALTOR® Association Market Reports.

Zoom Out: Florida and National Quick Hits

  • Florida just logged eight consecutive months of rising sales. Single-family closings statewide were +2.4% YoY in April; condo and townhouse +7%.
  • Toll Brothers, on its earnings call last week, specifically called out "green shoots in Florida." When publicly-traded builders are bullish on Florida again, that is worth noting.
  • Nationally, Redfin's April median sale price hit $396,173 (+2.4% YoY): the biggest annual gain in 13 months. The "crash" narrative the national media has been running is not showing up in the actual numbers.
  • Honest caveat: April CPI came in at +3.8% (mostly energy driven), so the Fed is unlikely to cut at the June 16-17 meeting. The good news is mortgage rates are already moving down without waiting on the Fed.

Source: Florida Realtors: April 2026 statewide sales report.

What's Getting Built in Our Backyard

Three Orlando development stories worth knowing for buyers and investors:

  • Creative Village Phase 2: about $100 million in active vertical construction right now (Parcel H / "The Beacon"). The full Phase 2 plan delivers 450 market-rate apartments, 106 mixed-income units, and 600 student beds through 2029. Downtown Orlando is still building.
  • Former Orlando Sentinel site: 20 acres downtown moving forward as a $2 billion mixed-use redevelopment with Heatherwick Studio as design lead. This is going to redefine the north end of Downtown.
  • Accelerate Orlando: the City of Orlando has committed $44 million to affordable housing and homeless initiatives. Real money behind a real plan.
  • Wellness Way corridor near Clermont: infrastructure investments there are about to unlock the next wave of Southwest Orlando growth: Windermere → Dr. Phillips → Winter Garden → Horizon West → Clermont.

Three Things to Do This Week

  1. Buyers: Call your lender and ask whether you qualify for Hometown Heroes assistance. Get your file flagged for the new tranche before the program saturates again.
  2. Sellers: Re-shop your homeowner's insurance. There are real savings on the table right now, and your current carrier may not be the cheapest after the Citizens cut and the 20 new market entrants.
  3. Both: If you've been "waiting for things to settle," they just did. Down payment help is up, the insurance bill is coming down, and demand is returning. Let's talk.

If you're house-hunting price-reduced inventory across our coverage area, the county landing pages are the fastest way to browse: Orange County, Seminole County, Volusia County, and Lake County.

Ready to make a move? Reach Brenden Rendo directly at (407) 616-9019 or brenden@homesinorlando.forsale, or visit HomesInOrlando.ForSale to start your search. New episodes of the Orlando Real Estate Buzz drop every Thursday.

May 24, 2026

Central Florida Price Reductions: 1,274 Homes With Price Cuts This Week


This week's numbers: 1,274 homes with active price reductions across Orange, Seminole, Volusia, and Lake counties, averaging 3.19% off list -- that is where the negotiation room is. Supporting context: 52.4% of those listings have been on the market 60+ days.

1. This Week's Price Reduction Snapshot

Every week, we pull fresh data from the Stellar MLS to track price reductions across four Central Florida counties. Here is where things stand as of May 24, 2026:

Orange County

534 price reductions

Average reduction: 3.13%

50.0% listed 60+ days

Browse Orange County

Seminole County

164 price reductions

Average reduction: 3.22%

47.0% listed 60+ days

Browse Seminole County

Volusia County

315 price reductions

Average reduction: 3.22%

56.8% listed 60+ days

Browse Volusia County

Lake County

261 price reductions

Average reduction: 3.17%

55.9% listed 60+ days

Browse Lake County

52.4% of all price-reduced listings have been on the market 60 days or longer. That is the number that matters most for buyers -- it signals sellers who are ready to negotiate on more than just price. Closing cost assistance, rate buydowns, and repair credits are all on the table when DOM climbs past 60.

2. What This Means for Buyers

Leverage is real right now. With 1,274 motivated sellers adjusting prices across four counties, buyers are not competing against the frenzy that defined 2021 and 2022. The data shows room to negotiate -- particularly on listings that have crossed the 60-day mark.

If you are pre-approved, this is the environment where a well-structured offer on a price-reduced listing can land below asking with concessions attached.

3. What This Means for Sellers

Price is a positioning decision, not a concession. The sellers who are closing right now are the ones who adjusted early and strategically. A price reduction does not mean desperation -- it means your listing re-enters buyer search alerts, gets fresh algorithmic exposure, and competes where actual demand exists.

If your listing has been sitting 45+ days without meaningful showing activity, the market is giving you a signal. We can help you read it.

4. What This Means for Investors

Price-reduced listings are where the math works. When a seller has already cut the price, your acquisition cost drops -- and with 52.4% of listings past 60 days, there is room to negotiate further. That improves your cap rate, your cash-on-cash return, and your exit strategy flexibility.

Whether you are looking at buy-and-hold rentals or fix-and-flip candidates, this week's data across 4 counties gives you a clear map of where motivated sellers are concentrated.

Frequently Asked Questions

How many price-reduced homes are available in Central Florida this week?

As of May 24, 2026, there are 1,274 homes with active price reductions across Orange, Seminole, Volusia, and Lake counties, averaging 3.19% off original list prices.

What does a price reduction mean for buyers?

A price reduction signals a motivated seller. Beyond the lower price itself, it often means faster closing timelines, openness to seller concessions, and more room to negotiate repairs or rate buydowns.

How often is this data updated?

We refresh our price reduction data weekly using direct Stellar MLS exports. New reductions are added each Sunday and sold properties are removed within 24 hours of closing.

Which county has the most price reductions right now?

Orange County currently leads with 534 active price reductions, averaging 3.13% off list prices.

Find Your Next Price-Reduced Home

Brenden Rendo and The Homes In Orlando Team track every price cut across Central Florida weekly. Whether you are buying, selling, or investing -- the data tells the story.

407-616-9019

Send Us a Message | Search Homes

May 22, 2026

Down Payments Hit 4-Year Low — Orlando Buyer Guide (Q1 2026)

There is a number stuck in most buyers' heads (20% down) and it has not matched what people are actually paying at the closing table for a long time. Per Realtor.com's Q1 2026 down payment report, the median down payment in the U.S. just fell to its lowest level in four years. The gap between what buyers assume they need and what they are actually putting down is now wider than it has been in a long stretch. Here is what the data shows, and how it lands for buyers in Orange, Seminole, Volusia, and Lake counties.

$23,400
Median U.S. Down Payment
Q1 2026: lowest in 4 years (Realtor.com)
12.8%
Median Share of Purchase Price
Down 4 straight quarters from 14%+
11.1%
South Region Avg Down Payment
Largest YoY drop: down 1.2 pts (Q1 2026)
~36%
FHA + VA Share of Purchase Loans
FHA 24%+ for 5 quarters · VA 11.7% (decade high)
TL;DR:
  • Median U.S. down payment fell to $23,400 (12.8%) in Q1 2026, the lowest in four years.
  • The South posted the largest year-over-year decline at 11.1% average, down 1.2 percentage points.
  • FHA loans have held above 24% of purchase mortgages for five straight quarters; VA loans hit 11.7%, a decade high.
  • On the April 2026 median list price of $425,000, a 3.5% FHA down payment is $14,875, not $85,000.
  • Across Orange, Seminole, Volusia, and Lake, the buyers I see closing are using FHA, VA, and 5-10% conventional. The 20% myth is a story, not a market.

1. What the Q1 2026 Data Actually Says

The headline number is $23,400, 12.8% of the purchase price. Down payments have now declined for four consecutive quarters, off a median of $28,900 a year ago.

For context, the pre-pandemic norm in Q1 2019 was $12,500 at 10.7%. Even after four straight quarters of decline, today's typical down payment is still above the pre-runup baseline. Buyers are not putting less down than ever, they are putting less down than during the 2021-2023 squeeze.

The regional picture is not uniform:

  • Northeast: 17.3% average, $57,600 median, down 1.0 percentage point YoY.
  • West: 15.2% average, $43,700 median, down 0.9 percentage points YoY.
  • Midwest: 13.6% average, $23,400 median, up slightly, the only region to increase.
  • South: 11.1% average, $21,100 median, down 1.2 percentage points YoY, the largest drop of any region.

That last line is the one that matters for Central Florida. We are in the region with the steepest decline, and the math on what it takes to get in has moved.

2. Why Down Payments Are Falling

Three forces moved at the same time, and they all point the same direction.

Inventory is up. National inventory has risen for 28 consecutive months per Realtor.com's April 2026 housing report. Locally, I am seeing the same shape: across the four counties, there are roughly 1,400 price-reduced active listings on any given Monday. More homes mean less competition, and buyers do not need to lead with extra cash down to win a contract.

Sellers are meeting the market. Nearly 40% of sellers nationwide now expect to offer concessions, up from 30% in 2025. That shows up here as closing-cost credits, rate buydowns, and repair credits, money that effectively offsets what a buyer would otherwise have to put down or hold in reserve.

Price growth has cooled. When prices are not climbing fast, buyers are not under the same pressure to put more down to keep the loan amount manageable. Combined with slightly easier mortgage rates than a year ago, the affordability math is moving in the buyer's favor for the first time in a while, small movement, but real.

3. The Rise of FHA and VA Loans

The shift in loan mix is the most concrete signal in this report.

  • FHA loans have held above 24% of all purchase mortgages for five consecutive quarters.
  • VA loans surged to 11.7% in early 2026, their highest share in over a decade.
  • Together, FHA and VA programs now account for more than a third of all purchase mortgages.

FHA requires as little as 3.5% down per HUD's 203(b) program guidelines. VA loans for eligible veterans and service members require zero down. These programs exist for exactly this market, and right now they are being used at levels we have not seen in years.

If you served, get your Certificate of Eligibility pulled before you start house-hunting. I see VA-eligible buyers leave six figures of leverage on the table because they assumed conventional was the only path.

4. What Renters Actually Have Saved, and Why That Matters

Realtor.com's analysis looked at the liquidity side of the equation. The median renter holds about $2,600 in liquid assets. Even adding stocks, bonds, and IRA funds available under the IRS first-time homebuyer exemption, that climbs only to roughly $2,900.

For most renters, the distance to a conventional median down payment is daunting. Saving while paying rent has been genuinely hard for a long time. But the picture changes when you change the target:

  • About 15-20% of renters have enough saved to clear the conventional median down payment of $23,400.
  • That climbs to 20-26% of renters when the target drops to a 3.5% FHA down payment: on the April 2026 median list price of $425,000, that is $14,875.

With roughly 45 million renter households in the U.S., somewhere between 9 and 11.7 million could clear the FHA threshold today. The practical takeaway: a lot of aspiring homeowners are closer than they realize. They are running the wrong math against the wrong loan product.

5. What This Means for Buyers in Orange, Seminole, Volusia, and Lake

Down payments are falling because the market has shifted, not because lenders got generous. More inventory, more concessions, and slower price growth made it easier to get in with less money down than was possible two years ago. The four-county picture mirrors the South-region data: Volusia and Lake especially are running with active listings sitting longer, which translates directly to negotiating leverage on price, concessions, or both.

If you have been waiting until you have "enough saved," it is worth checking whether the math has already moved in your favor. A few specific moves worth making:

  • Run the FHA number first. On a $300,000 Volusia or Lake County entry-level home, 3.5% down is $10,500, not $60,000. That is a different decision.
  • Ask for the concession. With sellers expecting to give them, leaving cash in your pocket via a closing-cost credit or 2-1 buydown is often more valuable than negotiating the price down by the same amount.
  • Pull your VA eligibility if it applies. Zero down on a $400,000 Seminole County home is real leverage. Do not assume you do not qualify.
  • Talk to a lender before you talk to anyone about a house. The conversation takes 20 minutes and tells you which loan type, which price ceiling, and which monthly payment actually fits your situation.

Per NAR's Profile of Home Buyers and Sellers, the typical first-time buyer has been pushing the median age of all buyers up, partly because the down payment myth has kept people out longer than the numbers required. Do not be that buyer.

Frequently Asked Questions

How much down payment do I actually need to buy a home in Central Florida?

Not 20%. Conventional loans can go to 3% down, FHA loans require 3.5%, and qualifying VA loans require nothing down. On the April 2026 national median list price of $425,000, a 3.5% FHA down payment is $14,875, well below what most buyers assume.

Why are down payments falling nationally?

Three forces moved at once: inventory has risen for 28 consecutive months, price growth has cooled, and roughly 40% of sellers now expect to offer concessions. Less competition means buyers do not need to lead with a hefty down payment to win a contract.

Are FHA and VA loans really being used more right now?

Yes. Per the Realtor.com Q1 2026 report, FHA loans have held above 24% of all purchase mortgages for five straight quarters, and VA loans surged to 11.7%, their highest share in over a decade. Together they are more than a third of purchase mortgages.

What is the typical Central Florida buyer actually putting down?

Realtor.com reports the South averaged 11.1% in Q1 2026, the largest year-over-year drop of any region, down 1.2 percentage points. In my experience working Orange, Seminole, Volusia, and Lake counties, FHA and conventional 5%-10% down deals dominate the entry-level price points. The 20% myth has not matched reality here for years.

Ready to run your actual numbers?

I will sit down with you and a lender I trust, run the FHA, VA, and conventional scenarios on real Central Florida price points, and tell you where you actually stand. No pressure, no pitch, just the math.

Schedule a 20-minute buyer call or call 407-616-9019.

Posted in Mortgage News
May 21, 2026

Zillow vs. Compass and MRED Lawsuit Explained for Orlando | Brenden Rendo

TL;DR: Zillow vs. Compass and MRED, in 60 seconds. On May 12, 2026, Zillow filed a federal antitrust suit in Chicago against the brokerage Compass and the listing service MRED (Midwest Real Estate Data). Zillow alleges the two are using control over Chicago's listing data to force a nationwide rules change that quietly decides which homes show up on public sites. At the center of the fight is the "private exclusive", a home a brokerage markets inside its own network instead of posting it for everyone to see. The case is framed as Chicago, but the ripple lands in Central Florida. For Orange, Seminole, Lake, and Volusia County buyers, the question is simple: are you seeing every home for sale, or just the slice one company is willing to show you?

1. The Fight in Plain English

Zillow has sued Compass and MRED in federal court in Chicago. The claim, in one sentence: Compass and MRED are working together to use their control over Chicago-area listing data to force a nationwide change in the rules that decide which homes appear on public sites like Zillow.

At the center of it is the "private exclusive", a home a brokerage markets quietly inside its own agent and client network instead of posting it on the MLS and the public portals. Compass has been building a national inventory of these. Zillow wants every publicly marketed home on its public site within one business day. That clash is now a federal antitrust lawsuit, and the outcome could quietly reshape how every American shops for a home, including buyers driving through Lake Mary, Winter Garden, Mount Dora, and DeLand.

2. How We Got Here: A Timeline

This did not happen overnight. The pieces were assembled over thirteen months.

  • April 2025: Zillow draws a line. Zillow rolls out its "Listing Access Standards." If a home is publicly marketed anywhere (a yard sign, a social post, a brokerage website), it must appear on Zillow within one business day. If it does not, Zillow will not display that home for the entire sale. The target is Compass's growing book of private and "coming soon" listings.
  • June 2025 to February 2026: Round one. Compass sues Zillow and loses. Compass calls the policy the "Zillow ban." A New York judge denies Compass's request to block it, ruling that Compass did not prove Zillow has monopoly power.
  • April 2026: Compass and MRED team up. MRED opens its private listing network to brokerages nationwide. Compass agrees to feed its full inventory in. Zillow's complaint alleges Compass also agreed to subsidize MRED membership for up to 100,000 of its agents, enough to potentially triple a regional Chicago listing service into a national rulemaking body.
  • Early to mid-May 2026: The pressure campaign. MRED demands Zillow reinstate previously banned Compass listings, including homes in Florida, Georgia, and California, far outside MRED's actual territory. Compass cuts off its direct listing feeds to Zillow nationwide. The tech provider that distributes MRED's feed threatens to cut Zillow off entirely.
  • May 12, 2026: Zillow files the antitrust suit. In Chicago, Zillow sues Compass and MRED, calling it an illegal "group boycott" under the Sherman Antitrust Act. It asks for an injunction, triple damages, and attorneys' fees.
  • May 18, 2026: The feed gets cut. Zillow asks the judge to block MRED from cutting it off. MRED suspends Zillow's and Trulia's feed anyway. Zillow calls it "a naked effort to kneecap Zillow's ability to compete." Tellingly, Zillow has stopped enforcing its own listing rules in Chicago (letting Compass's private listings through) to avoid losing the feed entirely.

3. The Four Players Behind Every Listing

Strip away the headlines and every home for sale has four groups fighting over it. Only one of them is built to work for the consumer.

  • The homeowner. Wants the home sold and seen by the largest possible pool of qualified buyers.
  • The brokerage. Compass and others want to keep listings inside their own networks as a competitive edge, a reason for sellers to hire them and a reason for buyers to call them.
  • The MLS. The shared database, built by independent brokerages to keep listings open to everyone in the market. In Central Florida, that is Stellar MLS. It is meant to be neutral.
  • The portals. Zillow, Trulia, Realtor.com, Redfin: the public sites where most buyers actually start looking.

The MLS is the only one of those four whose explicit job is making sure every cooperating agent in the market can show every cooperating listing to every qualified buyer. When the brokerage and the portal pick a fight over distribution, the MLS is the thing in the middle, and the homeowner and the homebuyer are the ones who pay the price.

4. Why This Matters If You're Buying or Selling

It is easy to read a story like this and treat it as inside-baseball. It is not. Here is how a Chicago courtroom decision actually lands on the kitchen table.

For buyers in Central Florida:

  • You cannot shop for a home you cannot see. When a home is a "private exclusive," the buyer scrolling Zillow at 11 p.m. does not know it exists. You end up competing for a smaller pool of homes than what is actually for sale in your school zone.
  • A two-tier market is a worse market. Hire a Compass agent and you see everything. Everyone else sees a curated slice. That is not a free, open market.
  • Inventory feels even tighter than it already is. Central Florida inventory is rebuilding in 2026, but it is still tight by historical standards. Splitting it into private clubs makes the real, shoppable supply look even smaller for the everyday buyer.

For sellers in Central Florida:

  • A private listing means fewer eyes on your home. Whoever controls distribution controls the toll booth. A smaller audience tends to mean a smaller buyer pool and less competition on price.
  • Days on market and sale price are downstream of exposure. The wider the qualified audience that sees the listing in the first 72 hours, the better the data tends to come back. A "quiet launch" makes for a slower sale on most homes, especially in suburban price bands where the buyer is shopping online before they call anyone.

For investors:

  • Off-market and pocket inventory has always existed in Central Florida. It has just been a smaller share of the total. A formalized national private-network model would shift the balance and make local broker relationships more valuable, not less. The investor edge moves further away from public portals and closer to who you know.

5. What the Court Is, and Isn't, Deciding

The court is not ruling on whether private listings are good or bad for homeowners. That is a separate, longer-running fight inside the National Association of REALTORS®, Stellar MLS, and every local board in the country.

The question in front of the Chicago judge is narrower: did two competitors (Compass the brokerage and MRED the listing service) illegally conspire to use control over Chicago's data to force a national outcome? That is the antitrust question. The answer could ripple far past Chicago, into Stellar MLS coverage and every MLS in the country.

6. Three Things I'm Watching Next

  • The October 2025 MRED rule change. MRED quietly rewrote its exclusion rules right after Zillow's policy launched. If the judge sees that as punishing a competitor, Zillow's case has teeth. If the judge calls it routine housekeeping, Zillow may walk away with nothing.
  • Whether other regions copy the MRED model. Watch whether listing services in Texas, Florida, and the Northeast adopt the same private-network structure or reject it. Reporting suggests a Compass executive has already pitched the model to a North Carolina listing service. If a major Florida MLS were ever to adopt that posture, it would matter to every Central Florida buyer.
  • The federal regulators. The FTC already sued Zillow and Redfin in September 2025 over a $100 million rental-ad deal. If federal regulators pick a side in the Compass-MRED case, this stops being a private commercial lawsuit and becomes existential for how listings work in this country.

7. What This Means in Orange, Seminole, Lake, and Volusia Counties

Here is the Central Florida-specific read. I service Orange, Seminole, Lake, and Volusia counties: the four-county footprint of the Homes In Orlando team. We are not MRED's territory. The local MLS is Stellar MLS, and as of today Stellar's rules still favor open, cooperative listings, the very model that the Chicago fight is challenging.

That does not mean Central Florida is unaffected. Three concrete points:

  • The Compass national feed cutoff already touches Florida. When Compass pulled its direct feed from Zillow in May 2026, that affected Compass-listed homes across the country, including some Central Florida inventory. Buyers searching Zillow only may have already missed homes in Winter Park, Lake Nona, and Heathrow that were marketed somewhere else.
  • Stellar MLS rules still favor consumers, for now. Stellar's cooperative model means that homes listed by participating brokerages flow to every participating agent and to the major portals. A buyer working with a Stellar MLS agent sees the same inventory whether that agent is at Compass, NextHome, RE/MAX, eXp, or a local independent. That is the system the lawsuit is, in effect, fighting over.
  • The "ask your agent for the full picture" rule applies more than ever. Even in a market where the MLS still functions the way it is supposed to, there are private exclusives, coming-soon listings, and off-market opportunities that live outside the public portals. A local agent who can pull a live MLS search and tell you what is also moving privately is the only way to see the full slice, not the slice one company decides to show you.

Where to start your search across the four counties

Orange County

Price-reduced homes in Orlando, Winter Park, Windermere, Winter Garden, and Apopka.

Browse Orange

Seminole County

Price-reduced homes in Lake Mary, Longwood, Oviedo, Heathrow, and Sanford.

Browse Seminole

Lake County

Price-reduced homes in Clermont, Mount Dora, Eustis, Tavares, and Leesburg.

Browse Lake

Volusia County

Price-reduced homes in DeLand, Deltona, DeBary, Port Orange, and New Smyrna.

Browse Volusia

8. The Bottom Line

A regional Chicago court case will quietly decide what every buyer in the United States gets to see five years from now. The headline will read "antitrust lawsuit." The practical question (the one that lands at your kitchen table) is much simpler.

If you are buying or selling in Central Florida soon, ask your agent where the homes are. All of them. Not just the ones on one company's private list.

Frequently Asked Questions

What is Zillow's lawsuit against Compass and MRED about?

Zillow filed a federal antitrust suit in Chicago on May 12, 2026, alleging that the brokerage Compass and the Chicago-area listing service MRED (Midwest Real Estate Data) are using their joint control over listing data to force a nationwide change in the rules that decide which homes appear on public sites like Zillow. Zillow calls it an illegal group boycott under the Sherman Antitrust Act. Compass and MRED dispute the claims.

What is a private exclusive or pocket listing?

A private exclusive is a home a brokerage markets quietly inside its own network (to its own agents and clients) instead of posting it for everyone to see on the MLS and public sites like Zillow and Realtor.com. Compass has built a large national inventory of these. Buyers outside that brokerage often have no idea those homes are for sale.

Does this lawsuit affect Orlando home buyers and sellers right now?

Yes. Indirectly. The Chicago feed cutoff has already caused some Compass listings in Florida, Georgia, and California to disappear from Zillow at various points, and Compass cut its direct feeds to Zillow nationwide in May 2026. In Orange, Seminole, Lake, and Volusia counties, the practical effect is that a portion of the homes for sale may not show up on the search you are running tonight, even when those homes have been actively marketed somewhere else.

How do I make sure I see every Orlando home for sale, not just the public ones?

Work with a local agent who is on the Stellar MLS, can pull a live MLS search across all participating brokerages, and will ask you directly whether you want to see private exclusives, coming-soon listings, and off-market opportunities in addition to the public portals. That is the only way today to see the full slice of inventory in Orange, Seminole, Lake, and Volusia counties, not the curated slice on any single company's website.

Want to see every home for sale in Orange, Seminole, Lake, or Volusia County, not just the ones on a single company's website?

Talk to Brenden: get the full MLS picture, including private and coming-soon listings

Brenden Rendo, REALTOR® · NextHome Neighborhood Realty · 407-616-9019

A note on sourcing: This post summarizes the public allegations in Zillow's May 12, 2026 federal antitrust complaint and related coverage. The lawsuit details are allegations Zillow has made in a pending case. They have not been proven in court, and Compass and MRED dispute them. MRED's CEO has stated that MRED's rules apply equally to every participant regardless of audience size. Verify any specific date or figure with primary reporting before relying on it.

Posted in Topic Of Interest
May 10, 2026

Central Florida Price Reductions May 2026: 1,394 Homes With Active Cuts


This week's numbers: 1,394 homes with active price reductions across Orange, Seminole, Volusia, and Lake counties, averaging 3.41% off list -- that is where the negotiation room is. Supporting context: 53.4% of those listings have been on the market 60+ days.

1. This Week's Price Reduction Snapshot

Every week, we pull fresh data from the Stellar MLS to track price reductions across four Central Florida counties. Here is where things stand as of May 10, 2026:

Orange County

522 price reductions

Average reduction: 3.2%

52.9% listed 60+ days

Browse Orange County

Seminole County

183 price reductions

Average reduction: 3.48%

47.0% listed 60+ days

Browse Seminole County

Volusia County

335 price reductions

Average reduction: 3.7%

58.8% listed 60+ days

Browse Volusia County

Lake County

354 price reductions

Average reduction: 3.25%

54.8% listed 60+ days

Browse Lake County

53.4% of all price-reduced listings have been on the market 60 days or longer. That is the number that matters most for buyers -- it signals sellers who are ready to negotiate on more than just price. Closing cost assistance, rate buydowns, and repair credits are all on the table when DOM climbs past 60.

2. Week-Over-Week Changes

Compared to last week's data:

  • **Orange County** held steady
  • **Seminole County** held steady
  • **Volusia County** held steady
  • **Lake County** held steady

These shifts reflect real buyer and seller activity -- not seasonal estimates. When listing counts drop, it typically means deals are closing. When they rise, new motivated sellers are entering the market.

3. What This Means for Buyers

Leverage is real right now. With 1,394 motivated sellers adjusting prices across four counties, buyers are not competing against the frenzy that defined 2021 and 2022. The data shows room to negotiate -- particularly on listings that have crossed the 60-day mark.

If you are pre-approved, this is the environment where a well-structured offer on a price-reduced listing can land below asking with concessions attached.

4. What This Means for Sellers

Price is a positioning decision, not a concession. The sellers who are closing right now are the ones who adjusted early and strategically. A price reduction does not mean desperation -- it means your listing re-enters buyer search alerts, gets fresh algorithmic exposure, and competes where actual demand exists.

If your listing has been sitting 45+ days without meaningful showing activity, the market is giving you a signal. We can help you read it.

5. What This Means for Investors

Price-reduced listings are where the math works. When a seller has already cut the price, your acquisition cost drops -- and with 53.4% of listings past 60 days, there is room to negotiate further. That improves your cap rate, your cash-on-cash return, and your exit strategy flexibility.

Whether you are looking at buy-and-hold rentals or fix-and-flip candidates, this week's data across 4 counties gives you a clear map of where motivated sellers are concentrated.

Frequently Asked Questions

How many price-reduced homes are available in Central Florida this week?

As of May 10, 2026, there are 1,394 homes with active price reductions across Orange, Seminole, Volusia, and Lake counties, averaging 3.41% off original list prices.

What does a price reduction mean for buyers?

A price reduction signals a motivated seller. Beyond the lower price itself, it often means faster closing timelines, openness to seller concessions, and more room to negotiate repairs or rate buydowns.

How often is this data updated?

We refresh our price reduction data weekly using direct Stellar MLS exports. New reductions are added each Sunday and sold properties are removed within 24 hours of closing.

Which county has the most price reductions right now?

Orange County currently leads with 522 active price reductions, averaging 3.2% off list prices.

Find Your Next Price-Reduced Home

Brenden Rendo and The Homes In Orlando Team track every price cut across Central Florida weekly. Whether you are buying, selling, or investing -- the data tells the story.

407-616-9019

Send Us a Message | Search Homes

May 4, 2026

Central Florida Price Reductions May 2026: 1,405 Homes With Active Cuts


This week's numbers: 1,405 homes with active price reductions across Orange, Seminole, Volusia, and Lake counties, averaging 3.26% off list -- that is where the negotiation room is. Supporting context: 50.7% of those listings have been on the market 60+ days.

1. This Week's Price Reduction Snapshot

Every week, we pull fresh data from the Stellar MLS to track price reductions across four Central Florida counties. Here is where things stand as of May 04, 2026:

Orange County

551 price reductions (-3 from last week)

Average reduction: 3.28%

45.2% listed 60+ days

Browse Orange County

Seminole County

198 price reductions (-1 from last week)

Average reduction: 3.18%

48.5% listed 60+ days

Browse Seminole County

Volusia County

312 price reductions (-1 from last week)

Average reduction: 3.24%

57.7% listed 60+ days

Browse Volusia County

Lake County

344 price reductions (-3 from last week)

Average reduction: 3.34%

51.5% listed 60+ days

Browse Lake County

50.7% of all price-reduced listings have been on the market 60 days or longer. That is the number that matters most for buyers -- it signals sellers who are ready to negotiate on more than just price. Closing cost assistance, rate buydowns, and repair credits are all on the table when DOM climbs past 60.

2. Week-Over-Week Changes

Compared to last week's data:

  • **Orange County** saw 3 fewer listings (likely absorbed by buyers)
  • **Seminole County** saw 1 fewer listings (likely absorbed by buyers)
  • **Volusia County** saw 1 fewer listings (likely absorbed by buyers)
  • **Lake County** saw 3 fewer listings (likely absorbed by buyers)

These shifts reflect real buyer and seller activity -- not seasonal estimates. When listing counts drop, it typically means deals are closing. When they rise, new motivated sellers are entering the market.

3. What This Means for Buyers

Leverage is real right now. With 1,405 motivated sellers adjusting prices across four counties, buyers are not competing against the frenzy that defined 2021 and 2022. The data shows room to negotiate -- particularly on listings that have crossed the 60-day mark.

If you are pre-approved, this is the environment where a well-structured offer on a price-reduced listing can land below asking with concessions attached.

4. What This Means for Sellers

Price is a positioning decision, not a concession. The sellers who are closing right now are the ones who adjusted early and strategically. A price reduction does not mean desperation -- it means your listing re-enters buyer search alerts, gets fresh algorithmic exposure, and competes where actual demand exists.

If your listing has been sitting 45+ days without meaningful showing activity, the market is giving you a signal. We can help you read it.

5. What This Means for Investors

Price-reduced listings are where the math works. When a seller has already cut the price, your acquisition cost drops -- and with 50.7% of listings past 60 days, there is room to negotiate further. That improves your cap rate, your cash-on-cash return, and your exit strategy flexibility.

Whether you are looking at buy-and-hold rentals or fix-and-flip candidates, this week's data across 4 counties gives you a clear map of where motivated sellers are concentrated.

Frequently Asked Questions

How many price-reduced homes are available in Central Florida this week?

As of May 04, 2026, there are 1,405 homes with active price reductions across Orange, Seminole, Volusia, and Lake counties, averaging 3.26% off original list prices.

What does a price reduction mean for buyers?

A price reduction signals a motivated seller. Beyond the lower price itself, it often means faster closing timelines, openness to seller concessions, and more room to negotiate repairs or rate buydowns.

How often is this data updated?

We refresh our price reduction data weekly using direct Stellar MLS exports. New reductions are added each Monday and sold properties are removed within 24 hours of closing.

Which county has the most price reductions right now?

Orange County currently leads with 551 active price reductions, averaging 3.28% off list prices.

Find Your Next Price-Reduced Home

Brenden Rendo and The Homes In Orlando Team track every price cut across Central Florida weekly. Whether you are buying, selling, or investing -- the data tells the story.

407-616-9019

Send Us a Message | Search Homes

April 28, 2026

Central Florida Price Reductions: 1,326 Homes With Price Cuts This Week


This week's numbers: 1,326 homes with active price reductions across Orange, Seminole, Volusia, and Lake counties. Average reduction: 3.55%. Listings sitting 60+ days: 51.4% of the total -- that is where buyers have the most leverage.

1. This Week's Price Reduction Snapshot

Every week, we pull fresh data from the Stellar MLS to track price reductions across four Central Florida counties. Here is where things stand as of April 26, 2026:

Orange County

538 price reductions (-52 from last week)

Average reduction: 3.67%

47.0% listed 60+ days

Browse Orange County

Seminole County

168 price reductions (+6 from last week)

Average reduction: 4.01%

52.4% listed 60+ days

Browse Seminole County

Volusia County

305 price reductions (-21 from last week)

Average reduction: 3.1%

49.2% listed 60+ days

Browse Volusia County

Lake County

315 price reductions (-62 from last week)

Average reduction: 3.44%

57.1% listed 60+ days

Browse Lake County

51.4% of all price-reduced listings have been on the market 60 days or longer. That is the number that matters most for buyers -- it signals sellers who are ready to negotiate on more than just price. Closing cost assistance, rate buydowns, and repair credits are all on the table when DOM climbs past 60.

2. Week-Over-Week Changes

Compared to last week's data:

  • **Orange County** saw 52 fewer listings (likely absorbed by buyers)
  • **Seminole County** added 6 new price reductions
  • **Volusia County** saw 21 fewer listings (likely absorbed by buyers)
  • **Lake County** saw 62 fewer listings (likely absorbed by buyers)

These shifts reflect real buyer and seller activity -- not seasonal estimates. When listing counts drop, it typically means deals are closing. When they rise, new motivated sellers are entering the market.

3. What This Means for Buyers

Leverage is real right now. With 1,326 motivated sellers adjusting prices across four counties, buyers are not competing against the frenzy that defined 2021 and 2022. The data shows room to negotiate -- particularly on listings that have crossed the 60-day mark.

If you are pre-approved, this is the environment where a well-structured offer on a price-reduced listing can land below asking with concessions attached.

4. What This Means for Sellers

Price is a positioning decision, not a concession. The sellers who are closing right now are the ones who adjusted early and strategically. A price reduction does not mean desperation -- it means your listing re-enters buyer search alerts, gets fresh algorithmic exposure, and competes where actual demand exists.

If your listing has been sitting 45+ days without meaningful showing activity, the market is giving you a signal. We can help you read it.

5. What This Means for Investors

Price-reduced listings are where the math works. When a seller has already cut the price, your acquisition cost drops -- and with 51.4% of listings past 60 days, there is room to negotiate further. That improves your cap rate, your cash-on-cash return, and your exit strategy flexibility.

Whether you are looking at buy-and-hold rentals or fix-and-flip candidates, this week's data across 4 counties gives you a clear map of where motivated sellers are concentrated.

Frequently Asked Questions

How many price-reduced homes are available in Central Florida this week?

As of April 26, 2026, there are 1,326 homes with active price reductions across Orange, Seminole, Volusia, and Lake counties, averaging 3.55% off original list prices.

What does a price reduction mean for buyers?

A price reduction signals a motivated seller. Beyond the lower price itself, it often means faster closing timelines, openness to seller concessions, and more room to negotiate repairs or rate buydowns.

How often is this data updated?

We refresh our price reduction data weekly using direct Stellar MLS exports. Each Tuesday, new reductions are added and sold properties are removed within 24 hours of closing.

Which county has the most price reductions right now?

Orange County currently leads with 538 active price reductions, averaging 3.67% off list prices.

Find Your Next Price-Reduced Home

Brenden Rendo and The Homes In Orlando Team track every price cut across Central Florida weekly. Whether you are buying, selling, or investing -- the data tells the story.

407-616-9019

Send Us a Message | Search Homes

April 16, 2026

Home Maintenance Budget Guide: Avoid Unexpected Repair Costs

For first-time homebuyers, the scariest part of owning often isn't the mortgage, it's the moment an ordinary day turns into unexpected home repairs. The core tension is simple: homeownership comes with ongoing home expenses that keep showing up even after move-in, and it's hard to tell which costs are normal and which ones signal trouble. When home maintenance costs feel random, every leak, rattle, or flicker can feel like a financial threat. With steady homeownership budgeting, maintenance becomes a predictable part of the plan.

TLDR:
  • Homeownership costs fall into two buckets (routine upkeep and emergency repairs) and the timing is what catches owners off guard.
  • A common baseline: the typical homeowner spends 1.02% of their home's value annually on maintenance, repair, and upkeep.
  • Inventory every major system (roof, HVAC, water heater, plumbing, appliances) with its install year, then assign each a monthly, seasonal, or annual cadence.
  • Flag aging equipment early (HVAC systems around 15 to 20 years old are a practical alert point) and build a replacement reserve before it fails.
  • Short, scheduled checks on roof, gutters, HVAC filters, the outdoor AC unit, and plumbing prevent small issues from turning into budget-wreckers.

Understanding Home Maintenance Costs

Home maintenance spending falls into two buckets: routine upkeep and emergency fixes. Routine costs are the small, planned items that keep systems running, while emergency repairs are the sudden failures that demand cash fast. The tricky part is timing, because every major system has a lifecycle, and several can reach "replacement age" around the same period.

This matters because maintenance doesn't hit your budget evenly. According to Bankrate's Hidden Costs of Homeownership Study, the average single-family homeowner now spends about $1,783 a month (roughly $21,400 a year) on hidden costs like maintenance, repairs, property taxes, insurance, and utilities. A steady set-aside helps you stay calm when something breaks and avoid using high-interest debt.

Think of your home like a car with overlapping service intervals. Filters are predictable, but a dead water heater is not, even if it was always going to happen. With the cost types clear, you can start estimating, scheduling, and projecting annual upkeep by system age.

Build a Realistic Home Maintenance Budget Plan

A simple system-by-system plan keeps routine upkeep predictable and makes surprise repairs less financially stressful. Use the steps below to estimate costs, schedule key tasks, and project what you will likely spend this year based on your home's age and major equipment.

  1. Set a baseline annual maintenance number
    Start with a rough target so you are not guessing from zero. Many budgets use a home value percentage as a starting point, and the typical homeowner spends 1.02% of their home's value annually on maintenance, repair, and upkeep. Treat this as a baseline to adjust up for older homes or down for newer, recently updated homes.

  2. Inventory your home systems and their ages
    Write down the install year or approximate age of your roof, HVAC, water heater, plumbing fixtures, appliances, and exterior items like paint and gutters. This turns "random problems" into a clear list of parts with timelines. If you are unsure, check inspection reports, permit history, model tags, or ask the prior owner.

  3. Turn the inventory into a upkeep calendar
    Assign each item a simple cadence: monthly (like HVAC filters), seasonal (like gutter cleaning), and annual (like servicing). Put tasks on your phone calendar and include a realistic cost range next to each one, even if it is just "$20 to $50." A calendar reduces the odds you skip small jobs that later trigger bigger failures.

  4. Add a replacement reserve for aging equipment
    Flag systems nearing end-of-life and start saving ahead of time, even if they still work today. The 15 to 20 years old range is a practical alert point for many HVAC system components, so you can begin building a cushion for repair spikes or replacement. Do the same for other big-ticket items based on their age, condition, and any warning signs.

  5. Build your annual projection and monthly set-aside
    Add your scheduled upkeep costs plus your replacement reserve to create one yearly total, then divide by 12 for a steady monthly transfer into a dedicated maintenance fund. Review the plan every 6 months and after any repair, then adjust categories that came in higher or lower than expected. This keeps your budget tied to real spending, not wishful thinking.

Prevent Big Repairs: Roof, HVAC, and Plumbing Mini-Checklist

Catching small problems early is one of the cheapest "repairs" you can make. Use the same calendar you built for your maintenance budget plan and plug these mini-checks into it so you're funding prevention, not panicking over emergencies.

  1. Do a roof walk-around every month (and after big storms): From the ground, look for missing/curled shingles, sagging spots along the roofline, and granules piling up in gutters or downspout outlets. Use binoculars, don't climb unless you're trained and conditions are dry. If you spot a new stain on a ceiling or damp insulation in the attic, treat it as urgent; small leaks often become expensive repairs quickly.

  2. Keep gutters and downspouts moving water away, fast: Clean gutters at least twice a year, then test them with a hose for proper flow. Confirm downspouts discharge 4-6 feet away from the foundation (extensions are an inexpensive fix) and that splash blocks aren't buried. This single habit reduces roof-edge rot, basement moisture, and siding damage, three common "mystery costs" that can wreck a maintenance budget.

  3. Seal roof penetrations and sun-exposed surfaces before they fail: Once or twice a year, check flashing and sealant around vents, chimneys, and skylights for cracks or gaps. If your roof gets intense sun exposure, consider a reflective option, some homeowners add an additional roof coating on compatible roof types to help reduce UV wear. When you budget, treat sealant, small flashing repairs, and coating touch-ups as planned line items, not surprises.

  4. Use a simple HVAC routine: filter, drain, and airflow check: Replace or clean filters on a set schedule (many homes land in the 1-3 month range depending on pets, dust, and allergies), and keep supply/return vents unblocked by furniture or rugs. During the cooling season, inspect the condensate drain line and pan for standing water, algae, or rust, early signs of a clog that can cause water damage. A checklist approach helps you identify and address small issues before they become breakdowns.

  5. Give the outdoor AC unit breathing room and a gentle clean: Clear leaves and weeds in a 2-foot radius, and keep shrubs trimmed back so the coil can shed heat properly. With the power off, rinse the fins gently from the inside out using a garden hose (no pressure washer), then straighten lightly bent fins with a fin comb if needed. Better airflow means less strain, which can extend equipment life and keep energy costs steadier.

  6. Run a quarterly plumbing "leak and pressure" sweep: Check under every sink, behind toilets, around the water heater, and near the washing machine for drips, corrosion, or soft/swollen cabinet floors. Note how quickly hot water arrives at fixtures and watch for new hammering/banging noises, both can hint at pressure or valve issues worth addressing early. If you have a water meter, do a quick "all water off" test for 30-60 minutes; any movement can signal a hidden leak that deserves follow-up.

A proactive home repair mindset works best when you document what you found, what you fixed, and what you're watching, those notes turn into clearer estimates, fewer repeat problems, and a budget that matches your home's real needs.

Home Maintenance Budget Questions, Answered

How can I accurately estimate annual home maintenance costs before buying a house?

Ask for the home's age and service history, then build a starter list by system: roof, HVAC, plumbing, electrical, appliances, exterior, and drainage. During inspection, request rough replacement timelines and 2 to 3 quotes for any flagged items so you can turn "maybe" into a dollar range. Put every quote into a one-page yearly categories list so you can see the likely annual total at a glance.

What are the key home systems I should budget for to avoid unexpected repair expenses?

Prioritize the big-ticket essentials that can cascade into damage: roof, HVAC, water heater, plumbing leaks, electrical panel, and foundation drainage. Add a small line for routine materials like filters, sealants, and caulk because home maintenance saves by preventing emergency calls.

How do I create a realistic maintenance budget that fits my financial situation?

Start with what you can comfortably auto-save monthly, then split it into "routine upkeep" and "future replacements." A running log helps you track every spend and spot patterns because tracking expenses is essential for avoiding cash crunches. Adjust quarterly based on real receipts, not guesses.

What are some practical tips for staying on top of routine home upkeep without feeling overwhelmed?

Keep tasks small and scheduled: one short check per week beats a massive weekend scramble. Use a home maintenance checklist to keep your home in good working order, then copy only the items that match your house into your calendar. Store photos and notes in the same place as your receipts so nothing gets lost.

How can a home warranty or service plan help me manage maintenance and repair costs after purchasing a home?

It can make some costs more predictable by shifting certain covered breakdowns into a known fee structure. Still, you should budget separately for exclusions, wear-and-tear items, and anything not covered, then keep a yearly categories list so you know what you truly spend. For faster budgeting, you can copy numbers from PDF quotes using a spreadsheet import or OCR tool, and paste them into your log.

What Central Florida Homes Need (That National Guides Miss)

Generic maintenance budgets miss a few realities of owning in Orange, Seminole, Volusia, or Lake County. Florida heat, humidity, hurricane season, and the state's tightening insurance market all shift which line items deserve more attention (and more dollars) in your annual plan.

  1. Plan two roof checks a year, plus one after every named storm: Florida's UV exposure ages shingles faster than national averages, and insurance carriers (including Citizens) are increasingly tying coverage decisions to roof age and condition. If your roof is 12+ years old, get a wind-mitigation inspection and a written condition report on file. Many Orange County homes built in the early 2010s are hitting that replacement window now.

  2. Treat the AC like a primary system, not an appliance: A Central Florida HVAC runs 8-9 months a year versus 4-5 in cooler states, so the 15-20 year alert window from national guides should be tightened to 12-15 years here. Schedule two service visits annually (spring tune-up, fall coil clean), and start a replacement reserve sooner than the box in step 4 above suggests. In Seminole County, where many homes were built in the late 1990s, AC system age is one of the top three issues that show up on inspection.

  3. Watch for humidity damage that doesn't show up nationally: Soft fascia, attic mold, slow plumbing leaks, and bathroom caulk failure all run faster in Florida humidity. Add quarterly bathroom and laundry-room caulk checks to the plumbing sweep in the previous section, and inspect attic insulation annually for water staining. A dehumidifier or mini-split combo in a converted garage or sunroom is often a smart spend.

  4. Budget for water heater replacement on a tighter cycle: Some Central Florida zip codes have hard water that shortens water heater life by 20-30%. If you're on well water (more common in parts of Lake County and rural Volusia), flush the tank annually and budget replacement at year 8-10 instead of year 12.

  5. Hurricane prep is a budget line, not a one-time event: Plywood, hurricane straps, generator fuel, tree trimming, and impact-resistant garage door upgrades all belong on the annual list. Many homeowners discover during their first storm that prep costs more than they budgeted because they're competing with everyone else in the region for the same supplies and contractors. Lock in pre-season service appointments and replace generator fuel additives every six months.

Building a Steady Home Maintenance Budget for Fewer Surprises

Homeownership gets stressful when routine wear turns into urgent repairs, and the cost is never convenient. A proactive maintenance mindset, backed by simple tracking and long-term home care planning, protects a home investment instead of constantly reacting to problems. When small costs are expected and organized, decisions get calmer and peace of mind in homeownership becomes the norm, not a lucky break. Proactive maintenance turns surprise repairs into planned expenses. Start today by opening a dedicated maintenance fund or scheduling the key annual checkups that fit the home's age and systems. That steady habit offers real support for homebuyers and builds resilience for whatever the house needs next.

Thinking about buying your first home in Central Florida?

A realistic maintenance budget starts with knowing what you're buying. I'll walk you through the inspection report, flag the system ages that matter most, and help you plan the first year of ownership before you close.

Visit homesinorlando.forsale or call 407-616-9019 to talk with Brenden Rendo.

Posted in Topic Of Interest