Area Real Estate News & Market Trends

You’ll find our blog to be a wealth of information, covering everything from local market statistics and home values to community happenings. That’s because we care about the community and want to help you find your place in it. Please reach out if you have any questions at all. We’d love to talk with you!

Nov. 5, 2026

Moving From Orlando to Myrtle Beach? Settle the Florida Side First

Sunrise over a Grand Strand beach with a wooden dune walkover through sea oats

The beach part of this move is easy to picture. Morning walks on the Grand Strand, no I-4 at 5:30, a slower pace. The hard part is the house you still own in Orlando. It holds most of your equity, it carries a tax break you are about to lose, and it has to sell on your timeline, not the market's.

Most people planning this move spend their research hours on the South Carolina side. That makes sense, it is the exciting part. But the money decisions that shape the whole move happen here first. Get the Florida side right and you arrive in Myrtle Beach with your proceeds in hand and no loose ends. Get it wrong and you can end up paying for a house you no longer live in, or a tax bill you did not see coming.

TLDR:
  • Your Florida Save Our Homes benefit does not follow you to South Carolina. It ends when you leave.
  • Tell the property appraiser when the Orlando home stops being your homestead. Keeping an exemption you no longer qualify for can mean back taxes, a 50% penalty, and 15% interest.
  • Selling first gives you certainty on proceeds. Buying first gives you one move. Pick based on whether you can carry two homes.
  • Keep your Orlando insurance in force until closing, and read the vacancy clause if the house will sit empty.
  • For the South Carolina side, read the Secure Home Finder Team's Myrtle Beach relocation guide.
View More
Posted in Selling Your Home
Nov. 5, 2026

Living in Lake Helen, FL: Who It Fits, and Who Should Look Elsewhere

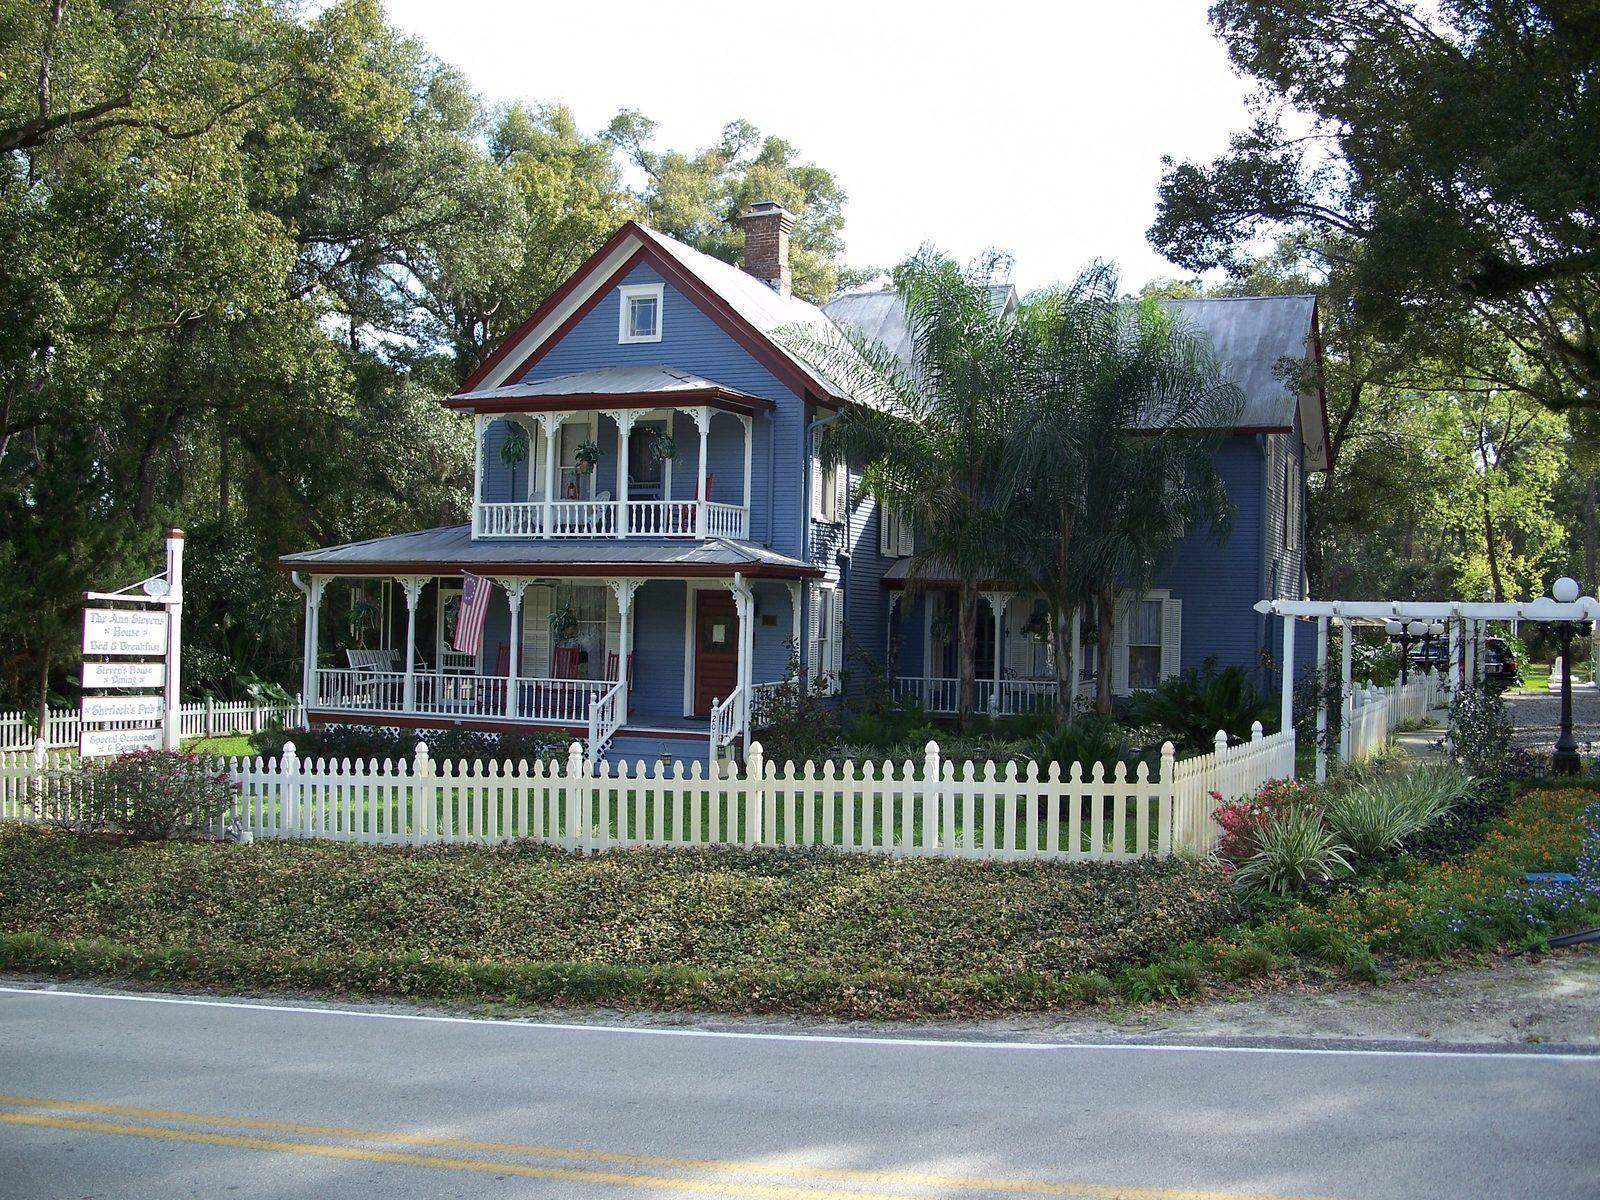
The historic Ann Stevens House in Lake Helen, Florida
Photo: Ebyabe, CC BY-SA 3.0, via Wikimedia Commons

Lake Helen is a small city in west Volusia County, founded by Henry DeLand and named after his daughter, and it is the old-town option between DeLand and Orange City. Almost no home that sells here comes with an association, a larger share of its homes were built before 1980 than in either neighbor, and every sale in the last twelve months was a single-family house. What sets the price is age: an older Lake Helen home typically closed at well under half the price of one built since 2020.

A note on scope: home sales on this page are counted by the Lake Helen mailing address, zip 32744, which reaches a little beyond the city limits; the population, income and commute figures describe the City of Lake Helen itself.

$207,500
Median Sale Price
September 2026, 2 closed sales
2,877
Population
U.S. Census ACS 2023, up 4.2% since 2019
17
Active Listings
Active residential listings in the city, October 23, 2026
28.7 min
Mean Commute
Against 25.6 minutes from DeLand

Who Lake Helen Fits, and Who It Doesn't

Strong fit: buyers who want no association, since nearly every home sold here in the last twelve months had none, against about half in DeLand; buyers who like older houses, since close to half of what sold here in the last twelve months was built before 1980; buyers who want room, since close to a quarter of sales sat on an acre or more, a larger share than in DeLand or Orange City; and buyers who want a quiet small town a short drive from DeLand.

Weaker fit: buyers who want a new subdivision with amenities, since Lake Helen has almost none and DeLand builds far more; anyone shopping for a townhome, condo or 55+ community, since none sold here; buyers who need choice, because the whole market is a small fraction of DeLand's; and anyone who wants a shorter commute, since Lake Helen's average drive is the longest of the three.

Still deciding between towns? We pulled the closed sales around a $450,000 budget and put Lake Helen side by side with its neighbors: what $450,000 actually buys in each. Square footage, bedrooms, year built, and how many came with a pool.

Where Is Lake Helen, and What Makes It Different?

Lake Helen is a city in west Volusia County, incorporated in 1888, between DeLand and Orange City. The mean commute is 28.7 minutes.

Lake Helen Housing Market Snapshot (2026)

Over the last twelve months 50 homes sold in Lake Helen at a median of $407,500, against 31 the year before, too few sales to read a direction from, so no year-over-year change is quoted here. In September 2026, 2 homes closed at a median of $207,500 and the typical one went under contract in 77 days. One month is too small a sample to read a direction from, which is why the twelve-month figure leads here. There are 17 active residential listings as of October 23, 2026, with a median asking price of $650,000, or $274 per square foot.

Wondering whether it is a buyer's or seller's market around Lake Helen? We publish that answer for Volusia County as a whole, from current MLS data: Is Volusia County a buyer's or seller's market?

Best Neighborhoods in Lake Helen, FL: Communities to Know

Lake Helen is the original town grid, a handful of newer streets and the larger lots around them.

  • The original town blocks, the streets laid out when the town was founded, filed in the MLS block by block
  • Woods of Lake Helen, the newer street of houses built from 2022 on, and nearly the only association in town; the three association sales in the last year closed at a median of about $600,000
  • The newer infill, new houses built on single lots across town, including on the Blakewood blocks and in Edgewood Estates; homes built since 2020 typically closed at about $620,000
  • The acreage, the larger lots around the edges of town, where homes on an acre or more typically closed at about $680,000

A home built before 1980 typically closed here at about $225,000, against more than $600,000 for one built since 2020, so in Lake Helen the first question to ask about any house is the year it was built.

Communities in Lake Helen with their own page:

Lake Helen vs. DeLand vs. Orange City: The Honest Comparison

 Lake HelenDeLandOrange City
Median asking price$650,000$375,000$319,900
Median $/sq ft$274$206$219
Mean commute28.7 minutes25.6 minutes24.8 minutes
Median household income$94,952$73,352$51,077
Population2,87739,83213,768

DeLand is the county seat just to the north, with a far larger market, a historic downtown and a large share of new subdivisions with associations. Orange City, to the southwest, is the more affordable and more built-up neighbor, with a shorter commute than Lake Helen. Lake Helen is the small old town between them, with almost no associations, more acreage and older houses than either, and a much smaller market.

Schools, Commute, and Day-to-Day Life

Volusia County Schools serves the city, and assignment varies by address rather than by city name, so confirm the zoning for the specific property before you buy on a school reputation.

Mean travel time to work is 28.7 minutes, against 25.6 from DeLand.

Is Lake Helen, FL Safe?

Lake Helen's reported violent crime rate is 101.3 per 100,000 residents against 280.8 for Florida as a whole, about 64% below the state figure. That is a real difference and it is one of the things buyers here are paying for. The same caveat applies in reverse though: rates are measured against resident population, so a town that few people commute into will tend to look better than a comparable one that they do.

Figures are reported offenses from the FBI Crime Data Explorer for the Lake Helen Police Department (ORI FL0640800), 2023, the most recent year that agency reported in a usable form. Reporting years differ between agencies, so this is compared to the Florida rate for the same year and is not comparable to another town's page.

Cost of Living in Lake Helen, FL

Housing is the line that moves a Central Florida budget. Lake Helen's median asking price is $650,000 against a median household income of $94,952, which puts a home at about 6.85 times household income here. That ratio, rather than the sticker price, is the number worth carrying between towns, and it is why a cheaper town is not automatically a more affordable one.

Florida charges no state income tax, so the property tax line matters more here than it would elsewhere, and a homestead exemption reduces the taxable value of a primary residence. Millage varies by taxing district, so treat any single quoted rate as an estimate until the specific parcel is checked.

Frequently Asked Questions

Is Lake Helen, FL a good place to live?

It depends on whether your income comes with you. Against the 60 places this site tracks across Orange, Seminole, Lake and Volusia counties, with that group's middle last measured on October 9, 2026, the median asking price of $650,000 is higher than most and the mean commute of 28.7 minutes is near the middle. The median household income here is $94,952, which puts housing at 6.85 times income, a heavier load than in most of those places. For remote workers and retirees who bring their income with them, that matters less. For someone earning a local wage, it is one of the harder places in the group to buy. Who it fits, and who it does not, is laid out at the top of this page.

What is the median home price in Lake Helen, FL?

The median sale price was $207,500 in September 2026 across 2 closed sales. Over the last twelve months 50 homes sold at a median of $407,500, against 31 the year before, too few sales to read a direction from, so no year-over-year change is quoted here. The median asking price across 17 active listings is $650,000, or $274 per square foot.

Is Lake Helen cheaper than DeLand?

On the asking median, no: $650,000 against $375,000. Measured against household income, Lake Helen is at 6.85 times income and DeLand at 5.11, so on that basis DeLand is the more affordable of the two. See what $450,000 buys in each town.

Is Lake Helen, FL safe?

The reported violent crime rate runs about 64% below the Florida average, though city rates are measured against resident population while the offense count includes everyone passing through.

What is the cost of living in Lake Helen, FL?

Housing is the deciding line. A median asking price of $650,000 against a median household income of $94,952 puts a home at roughly 6.85 times income, and Florida charges no state income tax, which shifts weight onto the property tax line.

What school district serves Lake Helen, FL?

Volusia County Schools. Assignment varies by address within the city, so confirm the zoning for the specific property.

Thinking About a Move to Lake Helen?

I work these four counties every week and I will tell you when a town is wrong for you. If you want the numbers for your budget before you tour anything, start with what $450,000 buys across Lake Helen and its neighbors, or call me at 407-616-9019.

You can also browse homes for sale in Lake Helen, which updates with current inventory.

Nov. 4, 2026

Are the New Condo Loan Rules Pushing Central Florida Condo Sales to Cash?

By Brenden Rendo, Realtor · Updated November 4, 2026

Since August, the conversation among lenders and agents online has run one direction: new agency condo review rules are going to turn condo buildings into cash-only markets. It is a reasonable worry, and the rule changes behind it are real. So I pulled this year's closed condominium sales in Orange, Seminole, Lake and Volusia counties out of Stellar MLS, 2,876 of them, and looked at how each one was paid for. The answer is narrower and less dramatic than the warnings: in these four counties, the cash share of closed condominium sales has not moved in any way the data can distinguish from ordinary month-to-month noise.

60.36%
Cash Share, Closed Condominium Sales
1,736 of 2,876 closings in Orange, Seminole, Lake and Volusia, Jan 1 to Nov 2, 2026 (Stellar MLS, pulled Nov 3, 2026)
1.10 points
The Entire Before-and-After Gap
59.97% cash January to July (2,031 closings) vs 61.07% August to October (840 closings)
Jan 4, 2027
The Date That Actually Matters Next
Fannie Mae and Freddie Mac raise the minimum reserve allocation from 10% to 15% of budgeted assessment income for Full Review applications dated on or after that day
80.51%
Cash Share, Condo-Hotel Subtype
157 of 195 closed Condo - Hotel sales in the same window, almost all of them in Orange and Volusia. A separate market, reported separately
TLDR:
  • The rules are real. Fannie Mae retired Limited Review and Freddie Mac retired Streamlined Review for applications dated on or after August 3, 2026, and the reserve floor rises from 10% to 15% on January 4, 2027.
  • The market effect is not visible yet in Central Florida. Across 2,876 closed condominium sales in Orange, Seminole, Lake and Volusia, cash was 59.97% of January-to-July closings and 61.07% of August-to-October closings, a gap of 1.10 points.
  • That gap is within ordinary statistical noise for samples this size, and single months from January through July ranged from 56.25% to 64.29% on their own.
  • Condominium sales in these counties were already majority cash before any of this. That is the baseline, not a new development.
  • The Florida-specific trap is a mismatch: state law only requires a structural integrity reserve study to recommend a baseline funding plan, and Freddie Mac will no longer accept baseline funding when a study is used as the reserve exception.

What actually changed, and on what dates

Two documents drive all of this. Fannie Mae issued Lender Letter LL-2026-03, Updates to Project Standards and Property Insurance Requirements, and Freddie Mac issued Bulletin 2026-C. The National Association of Realtors summarized both in its Washington Report on changes in condominium underwriting guidelines, published March 23, 2026.

Per that NAR summary, the package cuts both ways. New and established projects with 10 or fewer units may now qualify for a waiver of project review, and NAR reports that Fannie Mae and Freddie Mac eliminated the 50% investor concentration cap for established projects reviewed under Full Review. Those are loosenings. In the other direction, the Limited Review process was eliminated, so projects that used to clear it now need a Full Review unless they qualify for a waiver, and where a reserve study is used instead of the standard benchmark, the lender must rely on the highest recommended reserve amount in the study.

Three dates are worth writing down:

Date What happens Source
August 3, 2026 Freddie Mac sellers may use Streamlined Review only if the application received date is before this day. On or after it, a reserve study used as the reserve exception may not rely on the baseline funding methodology, and the study's highest recommendation applies. Freddie Mac Condominium Unit Mortgage FAQ
December 31, 2026 Outer limit for an association that paired its structural integrity reserve study with a milestone inspection. Florida law reads: "In no event may the structural integrity reserve study be completed after December 31, 2026." Florida Statutes s. 718.112(2)(g)7
January 4, 2027 For Full Review applications dated on or after this day, Fannie Mae and Freddie Mac raise the minimum replacement reserve allocation from 10% to 15% of annual budgeted assessment income. NAR summary of LL-2026-03; NAMB

The January date was contested and did not move. The National Association of Mortgage Brokers has a standing condo financing advocacy page describing its formal letter to FHFA asking for at least a twelve-month delay and a preserved streamlined pathway. As of this writing the dates stand as Fannie Mae and Freddie Mac published them. Trade coverage in late September reported that FHFA's answer was that the companies would implement on time.

On the insurance side, NAR's summary notes that master property policies may now carry per-unit deductibles of up to $50,000 provided unit owners carry supplemental coverage sufficient to cover the deductible, and that roofs must still be insured but certain wind or hail losses may be settled on an actual cash value basis rather than replacement cost. Read those two together and the practical effect is a shift of risk toward the individual unit owner's own policy. If you own a unit, that is a question for your insurance agent before renewal, not something to discover after a claim.

What 2,876 Central Florida condo closings show

Here is the pull. On November 3, 2026 I queried Stellar MLS for listings with a status of Closed, a close date between January 1 and November 2, 2026, a property type of Residential, and a property subtype of Condominium, in Orange, Seminole, Lake and Volusia counties. The query returned 2,876 sales, and every figure below describes those 2,876 records, not the condo market as a whole. I pulled the Condo - Hotel subtype in the same query and report it separately below, because it behaves nothing like a residential condominium. Leases were excluded; an earlier version of this query caught them and the medians gave the error away immediately.

Of those 2,876 closings, 2,873 record a buyer financing type. Only 3 are blank, so the denominator problem that usually ruins this kind of analysis does not apply here. The live value list in the Condominium pull, in order: Cash 1,736, Conventional 975, FHA 52, VA 43, Private 32, Seller Financing 21, and 14 records carrying combinations or one-off values such as Assumed and Lease Option / Purchase. Every cash figure below counts only the records whose financing type is exactly Cash. Ten of those 14 pair Cash with another financing type, and I have left all ten out of the cash count rather than guess which side carried the deal; folding all ten in would move the full-year share from 60.36% to 60.71%.

Cash was 60.36% of all 2,876 closed condominium sales. Split at August 1, the month the August 3 rule change took effect:

County Closed condominium sales Cash share, full year to date Cash share, Jan to Jul Cash share, Aug to Oct Median close price
Orange 1,489 58.03% 57.53% (1,062) 59.15% (426) $185,000
Seminole 493 60.65% 59.42% (345) 63.51% (148) $168,000
Lake 96 61.46% 66.18% (68) Suppressed $235,000
Volusia 798 64.41% 64.21% (556) 64.44% (239) $355,000
Four counties 2,876 60.36% 59.97% (2,031) 61.07% (840) $200,000

Source: Stellar MLS via the Bridge RESO API, pulled November 3, 2026. Closed sales only, property type Residential, property subtype Condominium, close dates January 1 to November 2, 2026. Figures in parentheses are the number of closings behind that share. Every share printed rests on 30 or more closings. Lake County's August-to-October cell is suppressed because only 27 Lake condominium sales closed in that window, below the 30-record floor I hold these to. Median close prices are the median for this subtype in this window and are a description of what sold, not a price trend.

Read the county rows and the shift story gets weaker, not stronger. Three of the four counties have a comparable before-and-after figure, and all three moved up, by 1.62 points in Orange, 4.09 points in Seminole and 0.23 points in Volusia. Lake cannot be compared at all on this split without going under the record floor. A move that ranges from a quarter of a point to four points across three counties, two of them barely moving, is not a market turning cash-only.

Now look at the monthly series, which shows how much this share moves on its own. Cash share of closed condominium sales by month, all four counties pooled, with closings in parentheses: January 56.25% (208), February 64.29% (266), March 61.57% (281), April 59.22% (309), May 63.69% (314), June 57.05% (319), July 57.49% (334), August 59.55% (309), September 62.98% (262), October 60.97% (269). Only 5 condominium sales in this pull closed in the first two days of November, far too few to report.

The January-through-July months alone span 56.25% to 64.29%, a spread of 8.04 points. Every single one of the three post-rule months sits inside that range. A 1.10-point gap between two windows is well within how much this series moved on its own in 2026, and at these sample sizes it is not a statistically meaningful difference.

Pro Move: The important number in that table is not the gap, it is the baseline. The condominium sales this pull returned in these four counties were already running about six in ten cash through July, before any of these rules applied to an application. If you are a seller pricing a condo, most of the buyers who actually closed on condos here paid cash all along, and a cash buyer prices your building's balance sheet into the offer whether or not a lender ever sees it.

The Condo - Hotel subtype is a different animal and belongs in its own row. In the same four counties and window, 195 Condo - Hotel sales closed and 157 of them were cash, 80.51%. Before and after the rule date: 79.72% of 143 closings in January through July, 82.69% of 52 closings in August through October. Condo-hotel projects are generally not eligible for agency financing in the first place, consistent with that market already running four-fifths cash and why nothing here should be mixed in with residential condominium figures.

For the supply side of the condo picture in these counties, including months of supply and the stale-listing share, I covered that separately in Central Florida condo supply and months of supply. Worth knowing in this context: as of the November 1, 2026 data pull behind that post, condo months of supply sat above six months in each of Orange, Seminole, Lake and Volusia. Buyers who can get a loan have choices, and that matters more to a seller right now than the review rules do.

The Florida wrinkle: a legal reserve study the agencies will not use

This is the part that is genuinely specific to Florida, and it is the part most of the national commentary misses.

Florida law tells an association what its structural integrity reserve study has to recommend. Section 718.112(2)(g)4.a of the Florida Statutes reads, in part, that "the structural integrity reserve study must include a recommendation for a reserve funding schedule based on a baseline funding plan that provides a reserve funding goal in which the reserve funding for each budget year is sufficient to maintain the reserve cash balance above zero. The study may recommend other types of reserve funding schedules, provided that each recommended schedule is sufficient to meet the association's maintenance obligation." You can read the full text of s. 718.112 on the Florida Legislature's site.

Baseline funding means the reserve cash balance never drops below zero. That is the floor the statute requires a study to put on the table.

Now read Freddie Mac's own answer in its Condominium Unit Mortgage FAQ, which I opened on November 3, 2026. On funding methodologies it says: "If a reserve study is used as an exception to our reserve requirements, then Sellers will not be able to use the baseline funding methodology to determine adequacy of replacement reserves for mortgages with an Application Received Date on or after August 3, 2026. Additionally, the highest recommendation in the reserve study must be used."

Put the two side by side. An association can commission a study that does exactly what Florida law requires of it, recommend baseline funding, fund to that recommendation, and still have no reserve-study route available to a Freddie Mac seller after August 3. The association then falls back to the flat budget test, which is a 10% allocation today and 15% for Full Review applications dated on or after January 4, 2027. A study that also recommends threshold or full funding is a different situation, because then the highest of its recommendations is the one that counts.

Two things this does not mean. It does not mean the unit cannot be financed. Freddie Mac's FAQ describes a Project Waiver Request path in Condo Project Advisor for established projects that do not meet the replacement reserve requirement, NAR describes the waiver of project review for projects of 10 or fewer units, and portfolio and non-agency lenders exist outside this system entirely. And it is not a statement about any particular building. I am not labeling anything here, and neither should a listing agent.

Quick Tip: If you are a unit owner or a board member, the single most useful question to ask your reserve study provider is which funding methodologies the study actually recommends. A study that recommends only baseline funding is legal in Florida and still leaves your buyers' lenders with one fewer door.

Reserve studies, milestone inspections and the document packet a buyer should be asking for are covered in more depth in my piece on Central Florida condo and HOA fees, so I am not going to repeat that checklist here.

What people are saying online, and who is saying it

I ran a thirty-day sweep of Reddit, X, TikTok, YouTube and Instagram for discussion of these rules. Two things stood out about the results, and both matter for how much weight to give them.

First, almost none of it is from Central Florida. The posts are national, or Florida-wide, or from South Florida, and I am presenting them as exactly that. No one quoted below is describing a deal in Orange, Seminole, Lake or Volusia county.

Second, the conversation is overwhelmingly practitioners explaining the rules, not consumers reporting that a deal died. In thirty days of searching I did not find a Central Florida buyer or seller posting about a condo loan that failed project review. That absence is not proof it is not happening. It does tell you that the alarm online is running ahead of the documented experience.

On X on October 7, 2026, @lenderlindsay tied deferred maintenance to financing access:

"The problem with this deferred maintenance is that if they do not get it completed, they will not be able to have any buyers finance with the agencies like Fannie Mae and Freddie Mac and FHA and VA….. after the condo collapse in Florida, these are deemed unwarrantable until the repairs are made. This is going to make it extremely hard to sell."

That is a fair description of the risk, and it is also stronger than I would put it. The waiver and portfolio paths above are the reason I would not use that label on a specific building without seeing the lender's determination in writing.

On TikTok on October 24, 2026, @movemetoparadise framed it as a building-level test: "Florida condo owners: your building now has to pass a test before a buyer can get a loan." The same post added, "Approval happens at the building level." That second sentence is the single most useful thing in the whole sweep. Buyers are used to being underwritten. The newer experience is the building being underwritten alongside them.

On TikTok on November 1, 2026, @floridamortgagelender posted the January date with the right caveats attached: "For Fannie Mae Full Review applications dated Jan. 4, 2027 or later, the minimum reserve allocation rises from 10% to 15% of annual budgeted assessment income. A qualifying reserve study can provide another route. This doesn't apply to every loan program."

A thread in r/Mortgages on October 21, 2026 titled "Fannie Mae guidelines and HOA issues" ran into the unit-count carve-outs. A commenter in that thread wrote: "Fannie Mae states that in states with statutory fidelity/crime insurance requirements, they'll accept those requirements instead of their own. There is also an exemption for condo projects with 20 units or fewer." I have not verified that commenter's unit threshold against the Selling Guide, and the carve-outs in Freddie Mac's FAQ are written around 2-to-4-unit and 5-to-10-unit projects, so treat the specific number as something to confirm with your lender rather than a rule to rely on. The general point holds: project size changes which requirements apply.

What this data cannot tell you

I would rather state the limits than let the headline number carry more than it can.

  • Closings in August through October are a mix of applications from both sides of the rule. A loan applied for in June can close in September. Stellar MLS does not carry the application received date, so this pull cannot separate pre-August-3 applications from post-August-3 ones. The post-rule window is contaminated by design, and it will be cleaner in the spring.
  • A deal that dies is invisible here. This pull is closed sales. A buyer whose conventional loan fell apart on project review and who walked away does not appear as anything at all, not as a cash sale and not as a failed one. If the rules are pushing financed buyers out of the market rather than converting them to cash, this measurement would not see it.
  • Stellar does not record which projects passed review. There is no field for it. Nothing here identifies a building, and nothing here should be read as a judgment about any building.
  • The two windows are different lengths and different seasons. Seven months against three. Shares are not affected by window length, but the two windows cover different seasons, and I have not separated any seasonal pattern out of the comparison.
  • This is a comparison, not a cause. Even if the gap had been large, nothing in this data would establish the rule change as the reason for it.
  • Financing type is reported by the agent at closing. It is a reliable field here, with 3 blanks out of 2,876, but it is self-reported.

One more thing this post is deliberately not about. Rates move condo demand too, and I am not going to muddle the two; if that is the question you came with, I covered it in mortgage rates crossing 7 percent in Central Florida.

What to check before you sign, buyer or seller

None of what follows is legal advice, and none of it is a promise about whether a particular loan will be approved. Confirm every item with your own lender and with the association.

If you are buying a condo in Orange, Seminole, Lake or Volusia county:

  1. Ask your lender, in writing, which review type this project will run under and whether the project has already been reviewed. The answer determines which requirements you are up against.
  2. Ask for the association's current budget and the replacement reserve line as a percentage of annual budgeted assessment income. That is the number the flat test is run against.
  3. Ask whether the association has a structural integrity reserve study, what funding methodologies it recommends, and whether the budget funds the highest of them.
  4. Ask about any special assessment, levied or discussed, and any outstanding critical repair. Per Freddie Mac's FAQ, a special assessment cannot be used in place of the budget reserve allocation.
  5. Get the questionnaire moving early. Freddie Mac's FAQ is explicit that the GSE condo questionnaire is optional and that when a questionnaire does not answer what the lender needs, the lender has to obtain more documentation, and if the determination cannot be made, the project is not eligible. A slow management company is a timeline risk on your contract.
  6. Have a backup financing conversation before you waive anything. Portfolio and non-agency options exist, they price differently, and that is a comparison to run on paper rather than discover late.

If you are selling a condo in these four counties:

  1. Assemble the document packet before you list: budget, reserve study, milestone inspection status, insurance declarations, minutes, assessment history. Every day your buyer's lender waits on the association is a day your contract is at risk.
  2. Price for the buyers who are actually closing. About six in ten of the closed condominium sales this pull returned in these counties this year were cash, 59.97% of the January-to-July closings and 61.07% of the August-to-October ones.
  3. If your association's budget is near the 10% line, understand what the January 4, 2027 step to 15% means for a buyer applying next year, and raise it with your board now rather than during a contract.
  4. Know your competition. Supply is long in all four counties, which I walked through in the condo supply post linked above and in the Central Florida housing market hub.

If you are an investor: the elimination of the 50% investor concentration cap for established projects under Full Review, per NAR's summary of LL-2026-03, is a real loosening and it has gone underdiscussed next to the reserve news. The reserve floor and the review requirements still apply. Underwrite the association's balance sheet, not just the unit.

Frequently asked questions

Did Central Florida condo sales actually shift toward cash after the August 2026 rule change?

Not measurably. Across 2,876 closed condominium sales in Orange, Seminole, Lake and Volusia counties pulled from Stellar MLS on November 3, 2026, cash was 59.97% of the 2,031 closings from January through July and 61.07% of the 840 closings from August through October, a gap of 1.10 points. A gap that size between samples of 2,031 and 840 closings is within ordinary statistical noise, and single months from January through July ranged from 56.25% to 64.29% on their own.

What changed in the Fannie Mae and Freddie Mac condo rules?

Fannie Mae's Lender Letter LL-2026-03 and Freddie Mac's Bulletin 2026-C revised project review. Per NAR's March 23, 2026 summary, the Limited Review process was eliminated, projects with 10 or fewer units may qualify for a waiver of project review, the 50% investor concentration cap was removed for established projects under Full Review, and where a reserve study is used the highest recommended reserve amount applies. Freddie Mac's own FAQ states that Streamlined Review may be used only if the application received date is before August 3, 2026.

What happens on January 4, 2027?

For Full Review applications dated on or after January 4, 2027, Fannie Mae and Freddie Mac raise the minimum replacement reserve allocation from 10% to 15% of the association's annual budgeted assessment income. The National Association of Mortgage Brokers asked FHFA for at least a twelve-month delay, and trade coverage in late September 2026 reported FHFA's position that the companies would implement on time. The date stands as published.

Can a Florida condo association follow state law and still fail the agency reserve test?

Yes, and this is the Florida-specific mismatch. Section 718.112(2)(g)4.a of the Florida Statutes requires a structural integrity reserve study to include, at minimum, a recommendation based on a baseline funding plan that keeps the reserve cash balance above zero. Freddie Mac's Condominium Unit Mortgage FAQ states that where a reserve study is used as the exception to its reserve requirements, sellers may not use the baseline funding methodology for applications received on or after August 3, 2026, and the study's highest recommendation must be used. An association can fund exactly to the statute's minimum recommendation and still have to meet the flat budget test instead.

Does this mean a condo in a building with low reserves cannot be financed?

No. Freddie Mac's FAQ describes a Project Waiver Request path in Condo Project Advisor for established projects that do not meet the replacement reserve requirement, NAR's summary describes the waiver of project review for projects of 10 or fewer units, and portfolio and non-agency lenders operate outside the agency framework. Eligibility is a determination your lender makes on your specific project and loan program, so get it in writing rather than relying on a general rule.

Why are condo-hotel figures reported separately?

Because they are a different market. In the same pull, 157 of 195 closed Condo - Hotel sales in these four counties were cash, 80.51%, compared with 60.36% across the 2,876 residential condominium sales. Condo-hotel projects are generally not eligible for agency financing to begin with, so mixing the two would overstate the cash share of the condominium market.

What is the single most useful question to ask before buying a Central Florida condo right now?

Ask your lender which review type the project runs under and whether it has already been reviewed, and ask the association which funding methodologies its structural integrity reserve study recommends. Those two answers tell you more about your financing risk than anything else on the document list.

Buying or selling a condo in Orange, Seminole, Lake or Volusia county and want the association's numbers read before you write an offer or set a price? That is the work, and I am happy to do it with you. Call or text me at 407-616-9019, or send me a message here. If you are weighing a sale, start with the home value estimator and we will refine it from there.

Posted in Mortgage News
Nov. 4, 2026

Wall Street Landlords Are Now Net Sellers: What Orlando Buyers and Sellers Should Know

For the last decade, the biggest single-family landlords in America were some of the most aggressive buyers in Central Florida. If you tried to buy a starter home in Orlando, Kissimmee or Deltona between 2020 and 2022, there is a good chance you lost at least one offer to a company with a fund behind it. In 2026, that picture flipped. The largest landlords are now selling more homes than they buy, and a new federal law is a big reason why.

View More
Nov. 4, 2026

Living in Chuluota, FL: Who It Fits, and Who Should Look Elsewhere

Welcome sign for Chuluota, Florida
Photo: Connor J Williams, CC BY 2.0, via Wikimedia Commons

Chuluota is an unincorporated community east of Oviedo in Seminole County, and its housing market comes in two sizes that barely overlap. On one side are the small houses on the old town plats, where homes in North Chuluota typically closed at about $336,000. On the other are acreage and lake estates: homes on an acre or more were about four in ten sales and typically closed above $850,000. Every home that sold here in the last twelve months was a single-family house; there are no condos or townhomes. The honest answer depends on which Chuluota a buyer means.

A note on scope: home sales on this page are counted by the Chuluota mailing address, zip 32766, which reaches well beyond the Census-defined Chuluota community; the population, income and commute figures describe that Census community.

$495,000
Median Sale Price
September 2026, 5 closed sales
2,179
Population
U.S. Census ACS 2023
18
Active Listings
Active residential listings in the city, October 23, 2026
39.7 min
Mean Commute
Against 26.9 minutes from Oviedo

Who Chuluota Fits, and Who It Doesn't

Strong fit: buyers who want land in Seminole County, since about four in ten homes sold here sat on an acre or more, against about one in twenty-five in Oviedo; buyers who want a smaller, older house with no association for less than Oviedo charges, since North Chuluota homes typically closed at about $336,000 against about $435,000 for resale homes without an association in Oviedo; buyers who want a lake estate, since Chuluota has them in Killaloe by the Lake, Estates on Lake Mills and Chula Vista; and anyone who wants a rural feel within a short drive of Oviedo.

Weaker fit: buyers who want new construction, since Chuluota sold fewer homes built in 2020 or later than either Oviedo or Geneva; anyone shopping for a townhome or a condo, since none sold here; buyers who need shops and restaurants close by, which means Oviedo; and anyone with a daily drive toward Orlando, since the average commute is longer than Oviedo's.

Still deciding between towns? We pulled the closed sales around a $675,000 budget and put Chuluota side by side with its neighbors: what $675,000 actually buys in each. Square footage, bedrooms, year built, and how many came with a pool.

Where Is Chuluota, and What Makes It Different?

Chuluota is an unincorporated community in eastern Seminole County, east of Oviedo. It was laid out in the 1890s by Henry Flagler's Chuluota Land Company and grew mainly after the 1950s; the local chamber describes it as working to keep its rural character. The mean commute is 39.7 minutes.

Chuluota Housing Market Snapshot (2026)

Over the last twelve months 63 homes sold in Chuluota at a median of $685,000, up 31.7% against the twelve months before. Per square foot, which strips out any change in the size of what sold, the figure rose 3.1%. In September 2026, 5 homes closed at a median of $495,000 and the typical one went under contract in 80 days. One month is too small a sample to read a direction from, which is why the twelve-month figure leads here. That twelve-month median rests on 63 sales, a small sample for a percentage, so read it as directional rather than precise. There are 18 active residential listings as of October 23, 2026, with a median asking price of $799,000, or $318 per square foot.

Wondering whether it is a buyer's or seller's market around Chuluota? We publish that answer for Seminole County as a whole, from current MLS data: Is Seminole County a buyer's or seller's market?

Best Neighborhoods in Chuluota, FL: Communities to Know

Chuluota is the old town, one large planned community and a ring of lake and acreage neighborhoods.

  • North Chuluota, the original town plats, laid out for Henry Flagler's Chuluota Land Company and mostly built up after World War II; small houses of about 1,350 square feet, typically closing at about $336,000, with no association
  • The Trails, the planned community of houses built around 2005 on quarter-acre lots, filed in the MLS under several units; the main label typically closed at about $645,000
  • Pickett Downs, houses on lots of about two acres, part of the acreage end of the market
  • The lake communities, Killaloe by the Lake on Lake Pickett, Estates on Lake Mills and Chula Vista, the lake end of the market; across Chuluota, the eight waterfront homes that sold in the last year typically closed at about $980,000

Off the old plats, homes on an acre or more typically closed at more than twice the North Chuluota price and at a higher price per square foot, so a buyer here pays for the land as well as the larger house. It is also why the twelve-month median above says more about what sold than about prices: homes on an acre or more were about three in ten sales the year before and about four in ten in the last twelve months, so more of what sold was the expensive side of the market, while the price per square foot rose only slightly.

Communities in Chuluota with their own page:

Chuluota vs. Oviedo vs. Geneva: The Honest Comparison

 ChuluotaOviedoGeneva
Median asking price$799,000$477,450$755,000
Median $/sq ft$318$243$344
Mean commute39.7 minutes26.9 minutes45.9 minutes
Median household income$85,804$114,092$142,188
Population2,17939,9903,520

Oviedo is the large suburban city to the west, with a far bigger market, new subdivisions, townhomes and shopping close by. Geneva, to the north, is almost all acreage, with no association on most of it and a long drive. Chuluota sits between the two: a small older town with Oviedo's prices at the top end and Geneva's land, but only part of the time.

Schools, Commute, and Day-to-Day Life

Seminole County Public Schools serves the city, and assignment varies by address rather than by city name, so confirm the zoning for the specific property before you buy on a school reputation.

Mean travel time to work is 39.7 minutes, against 26.9 from Oviedo.

Is Chuluota, FL Safe?

Chuluota is unincorporated and policed by the Seminole County Sheriff's Office, so there is no town-level crime rate to publish here. The Seminole County Sheriff's Office reported a violent crime rate of 182.2 per 100,000 residents against 280.8 for Florida as a whole. That rate covers everything the Sheriff's Office polices, Chuluota included, so read it as context for the wider area and not as a measurement of this town.

Figures are reported offenses from the FBI Crime Data Explorer for the Seminole County Sheriff's Office (ORI FL0590000), 2023, the most recent year that agency reported in a usable form. Reporting years differ between agencies, so this is compared to the Florida rate for the same year and is not comparable to another town's page.

Cost of Living in Chuluota, FL

Housing is the line that moves a Central Florida budget. Chuluota's median asking price is $799,000 against a median household income of $85,804, which puts a home at about 9.31 times household income here. That ratio, rather than the sticker price, is the number worth carrying between towns, and it is why a cheaper town is not automatically a more affordable one.

Florida charges no state income tax, so the property tax line matters more here than it would elsewhere, and a homestead exemption reduces the taxable value of a primary residence. Millage varies by taxing district, so treat any single quoted rate as an estimate until the specific parcel is checked.

Frequently Asked Questions

Is Chuluota, FL a good place to live?

It depends on whether your income comes with you. Against the 60 places this site tracks across Orange, Seminole, Lake and Volusia counties, with that group's middle last measured on October 9, 2026, the median asking price of $799,000 is higher than most and the mean commute of 39.7 minutes is longer than most. The median household income here is $85,804, which puts housing at 9.31 times income, a heavier load than in most of those places. For remote workers and retirees who bring their income with them, that matters less. For someone earning a local wage, it is one of the harder places in the group to buy. Who it fits, and who it does not, is laid out at the top of this page.

What is the median home price in Chuluota, FL?

The median sale price was $495,000 in September 2026 across 5 closed sales. Over the last twelve months 63 homes sold at a median of $685,000, up 31.7% against the twelve months before. The median asking price across 18 active listings is $799,000, or $318 per square foot.

Is Chuluota cheaper than Oviedo?

On the asking median, no: $799,000 against $477,450. Measured against household income, Chuluota is at 9.31 times income and Oviedo at 4.18, so on that basis Oviedo is the more affordable of the two. See what $675,000 buys in each town.

Is Chuluota, FL safe?

Chuluota is unincorporated and policed by the Seminole County Sheriff's Office, so there is no town-level crime rate to publish here. The nearest measure is the rate reported by the Seminole County Sheriff's Office, which covers Chuluota along with the rest of its territory, so it is not specific to this town.

What is the cost of living in Chuluota, FL?

Housing is the deciding line. A median asking price of $799,000 against a median household income of $85,804 puts a home at roughly 9.31 times income, and Florida charges no state income tax, which shifts weight onto the property tax line.

What school district serves Chuluota, FL?

Seminole County Public Schools. Assignment varies by address within the city, so confirm the zoning for the specific property.

Thinking About a Move to Chuluota?

I work these four counties every week and I will tell you when a town is wrong for you. If you want the numbers for your budget before you tour anything, start with what $675,000 buys across Chuluota and its neighbors, or call me at 407-616-9019.

You can also browse homes for sale in Chuluota, which updates with current inventory.

Nov. 3, 2026

Living in Okahumpka, FL: Who It Fits, and Who Should Look Elsewhere

The historic Campbell House in Okahumpka, Florida
Photo: Ebyabe, CC BY 2.5, via Wikimedia Commons

Okahumpka is a small unincorporated crossroads in western Lake County, a few miles south of Leesburg, and almost everything that sells here is newer than people expect. About six in ten homes sold in the last twelve months were built in 2020 or later, nearly all of them in two communities: Spring Creek and the gated 55+ Cottages of Sanders Grove. That is a far newer market than Leesburg's, about the same as Groveland's, at a much smaller scale. The honest answer depends on whether a buyer wants a near-new house without a big subdivision around it, or wants the shops, choice and shorter drive that come with a real town.

A note on scope: the Census-defined Okahumpka community is only a few hundred people, so this page uses the Okahumpka mailing address, zip 34762, for population, income and commute; home sales are counted by the Okahumpka mailing address too.

$279,000
Median Sale Price
September 2026, 1 closed sales
580
Population
U.S. Census ACS 2023
11
Active Listings
Active residential listings in the city, October 23, 2026
38.7 min
Mean Commute
Against 24.8 minutes from Leesburg

Who Okahumpka Fits, and Who It Doesn't

Strong fit: buyers who want a house only a few years old, since most of what sells here was built since 2020 and is now changing hands as a resale; buyers 55 and over who want a small gated community, since the Cottages of Sanders Grove homes closed at about $285,000; buyers who drive Florida's Turnpike, which has an interchange about three miles west on County Road 470; and anyone who wants a quiet place a short drive from Leesburg.

Weaker fit: buyers who need choice, because the whole market is a small fraction of Leesburg's or Groveland's; anyone with a daily commute toward Orlando, since Okahumpka has the longest average commute of the three; buyers who want shops, restaurants and a downtown close by, which means Leesburg; and buyers who want a builder's new house with incentives, since Groveland sells far more of them.

Still deciding between towns? We pulled the closed sales around a $350,000 budget and put Okahumpka side by side with its neighbors: what $350,000 actually buys in each. Square footage, bedrooms, year built, and how many came with a pool.

Where Is Okahumpka, and What Makes It Different?

Okahumpka is an unincorporated community in western Lake County. County Road 33 runs through it to US 27 and Leesburg, and County Road 470 reaches Florida's Turnpike about three miles to the west. The mean commute in the 34762 zip is 38.7 minutes.

Okahumpka Housing Market Snapshot (2026)

Over the last twelve months 15 homes sold in Okahumpka at a median of $325,000, against 8 the year before, too few sales to read a direction from, so no year-over-year change is quoted here. In September 2026, 1 homes closed at a median of $279,000 and the typical one went under contract in 41 days. One month is too small a sample to read a direction from, which is why the twelve-month figure leads here. There are 11 active residential listings as of October 23, 2026, with a median asking price of $335,990, or $195 per square foot.

Wondering whether it is a buyer's or seller's market around Okahumpka? We publish that answer for Lake County as a whole, from current MLS data: Is Lake County a buyer's or seller's market?

Best Neighborhoods in Okahumpka, FL: Communities to Know

Okahumpka is two newer communities, a few acreage homes and the old crossroads itself.

  • Spring Creek, the community of houses built in 2022 and 2023, filed in the MLS under four spellings and phases; across Okahumpka, homes built since 2020 closed at a median of about $345,000
  • The Cottages of Sanders Grove, the gated 55+ community of single-story homes, where the builder is still selling new homes alongside resales
  • Banana Point, the larger houses on lots of an acre and a half to two acres, one sale in the last year, at about $825,000
  • The old crossroads, the few older homes and rural lots around the original crossroads, where the Historic Campbell House is listed on the National Register of Historic Places

Okahumpka is also where the civil rights attorney Virgil D. Hawkins was born. For a buyer, the practical point is simpler: outside the two newer communities, only a few homes a year come up for sale here.

Communities in Okahumpka with their own page:

Okahumpka vs. Leesburg vs. Groveland: The Honest Comparison

 OkahumpkaLeesburgGroveland
Median asking price$335,990$284,900$413,300
Median $/sq ft$195$165$199
Mean commute38.7 minutes24.8 minutes33.8 minutes
Median household income$80,601$47,506$92,258
Population58028,46120,621

Leesburg is the established city just to the north, with a much larger market, a 55+ segment of its own and a downtown on the lakes. Groveland is the fast-growing town farther south in Lake County, where builders sell new houses every week. Okahumpka is the small crossroads between them, where most of what sells is a near-new house in one of two communities, at the cost of choice and a longer drive.

Schools, Commute, and Day-to-Day Life

Lake County Schools serves the city, and assignment varies by address rather than by city name, so confirm the zoning for the specific property before you buy on a school reputation.

Mean travel time to work is 38.7 minutes, against 24.8 from Leesburg.

How Much of Okahumpka Is New Construction?

Okahumpka is unincorporated and policed by the Lake County Sheriff's Office, which has not reported usable annual figures to the FBI in the years checked, so there is no honest crime rate to publish here, and a number that cannot be sourced is worse than none. What can be measured is the age and type of what is for sale, which is the other question relocation buyers ask.

Across 11 active residential listings, the median asking price is $335,990, or $195 per square foot. Where a town is still building, the per square foot figure runs closer to replacement cost; where it is built out, it reflects land and location instead.

Cost of Living in Okahumpka, FL

Housing is the line that moves a Central Florida budget. Okahumpka's median asking price is $335,990 against a median household income of $80,601, which puts a home at about 4.17 times household income here. That ratio, rather than the sticker price, is the number worth carrying between towns, and it is why a cheaper town is not automatically a more affordable one.

Florida charges no state income tax, so the property tax line matters more here than it would elsewhere, and a homestead exemption reduces the taxable value of a primary residence. Millage varies by taxing district, so treat any single quoted rate as an estimate until the specific parcel is checked.

Frequently Asked Questions

Is Okahumpka, FL a good place to live?

Start with the numbers. Against the 60 places this site tracks across Orange, Seminole, Lake and Volusia counties, with that group's middle last measured on October 9, 2026, the median asking price of $335,990 is lower than most and the mean commute of 38.7 minutes is longer than most. The median household income here is $80,601, which puts housing at 4.17 times income, a lighter load than in most of those places. On local incomes, that makes buying here easier than in most of the group. Who it fits, and who it does not, is laid out at the top of this page.

What is the median home price in Okahumpka, FL?

The median sale price was $279,000 in September 2026 across 1 closed sales. Over the last twelve months 15 homes sold at a median of $325,000, against 8 the year before, too few sales to read a direction from, so no year-over-year change is quoted here. The median asking price across 11 active listings is $335,990, or $195 per square foot.

Is Okahumpka cheaper than Leesburg?

On the asking median, no: $335,990 against $284,900. Measured against household income, Okahumpka is at 4.17 times income and Leesburg at 6.00, so on that basis Okahumpka is the more affordable of the two. See what $350,000 buys in each town.

What is the cost of living in Okahumpka, FL?

Housing is the deciding line. A median asking price of $335,990 against a median household income of $80,601 puts a home at roughly 4.17 times income, and Florida charges no state income tax, which shifts weight onto the property tax line.

What school district serves Okahumpka, FL?

Lake County Schools. Assignment varies by address within the city, so confirm the zoning for the specific property.

Thinking About a Move to Okahumpka?

I work these four counties every week and I will tell you when a town is wrong for you. If you want the numbers for your budget before you tour anything, start with what $350,000 buys across Okahumpka and its neighbors, or call me at 407-616-9019.

You can also browse homes for sale in Okahumpka, which updates with current inventory.

Nov. 2, 2026

Living in Bella Collina: What It Costs, What You Get, and Who It Fits

Bella Collina is the guard-gated golf community on the south side of Montverde, on Lake Apopka and its own spring-fed Lake Siena, and it is really three markets behind one gate. The estate sections, where houses on lots of about an acre typically closed at close to $3 million; Bella Collina West, with houses on much smaller lots at about $1.4 million; and the Siena condominiums at about $420,000. It is also still being built: new homes were a far larger share of what sold here in the last twelve months than in Windermere or Dr. Phillips.

A note on scope: this is a deep dive on Bella Collina alone. Home sales are every sale labeled Bella Collina or Siena in zip 34756, whether the MLS filed it under Montverde or Bella Collina. Bella Collina is not a Census place, so the population, income and commute figures describe the whole 34756 zip, which is all of Montverde. For the rest of the town, see Living in Montverde.

$1,900,000
Median Sale Price
September 2026, 4 closed sales
4,280
Population
U.S. Census ACS 2023
80
Active Listings
Active residential listings in the city, October 23, 2026
34.9 min
Mean Commute
Against 30.9 minutes from Windermere

Who Bella Collina Fits, and Who It Doesn't

Strong fit: buyers who want a new luxury house in a guarded golf community, since about half the estate sections' sales were new houses; buyers who want acreage inside a gate, since an acre or more here closed at about $3 million; buyers who want a Bella Collina address for less, through Bella Collina West at about $1.4 million or a Siena condo at about $420,000; and families drawn to Montverde Academy just north of the gates.

Weaker fit: anyone shopping on price per square foot, since new houses here closed for far more per square foot than new houses in Windermere or Dr. Phillips; buyers who expect golf and the club to come with the house, since they are a separate club membership; buyers who need to resell quickly, since resales here took about two and a half months to go under contract, against five to seven weeks in Windermere and Dr. Phillips; and anyone who wants an established neighborhood with mature trees, which is what Windermere's older communities offer.

Still deciding between towns? We pulled the closed sales around a $2,250,000 budget and put Bella Collina side by side with its neighbors: what $2,250,000 actually buys in each. Square footage, bedrooms, year built, and how many came with a pool.

Where Is Bella Collina, and What Makes It Different?

Bella Collina is a 1,900-acre guard-gated community in the Town of Montverde in south Lake County, on Lake Apopka and Lake Siena, with a Sir Nick Faldo golf course and a 75,000 square foot clubhouse, with County Road 455 running past its gates. Montverde Academy sits just north. The mean commute is 34.9 minutes.

Bella Collina Housing Market Snapshot (2026)

Over the last twelve months 83 homes sold in Bella Collina at a median of $1,700,000. New construction was 70% of sales in the twelve months before and 36% in the last twelve, so the two medians describe different homes and no year-over-year change is quoted here. In September 2026, 4 homes closed at a median of $1,900,000 and the typical one went under contract in 125 days. One month is too small a sample to read a direction from, which is why the twelve-month figure leads here. There are 80 active residential listings as of October 23, 2026, with a median asking price of $1,825,000, or $474 per square foot.

Wondering whether it is a buyer's or seller's market around Bella Collina? We publish that answer for Lake County as a whole, from current MLS data: Is Lake County a buyer's or seller's market?

New Construction and Resale Are Not the Same Market

Every price figure quoted for Bella Collina mixes brand new homes with existing ones. Split apart, the last twelve months looked like this.

What soldMedian, prior 12 monthsMedian, last 12 monthsChangeSales
New construction$1,400,000$2,450,000+75.0%30
Existing homes (resale)$1,120,000$1,270,000+13.4%53
All sales combined$1,350,000$1,700,000+25.9%83

Read the new-construction row carefully. It rests on fewer than 50 sales in at least one of the two years. The median new-construction home sold in Bella Collina went from 3,535 square feet to 4,366, 23.5% larger, while the price per square foot moved +44.2%. That is too few to say whether the change is a price move or a change in which homes sold.

The new construction and existing homes rows rest on fewer than 50 sales in at least one of the two years, so read those changes as noise rather than a trend.

Best Neighborhoods in Bella Collina, FL: Communities to Know

Bella Collina sorts into its estate sections, its smaller-lot west side and its condominiums.

  • The estate sections, the main Bella Collina plats around the golf course, where houses of about 5,000 square feet on lots of about an acre closed at close to $3 million, roughly $580 a square foot, and about half were new
  • Bella Collina East, the smaller section toward Lake Apopka, where most sales were on the water, at about $2.2 million
  • Bella Collina West, the west side of the community on lots of about a sixth of an acre, where houses of about 3,150 square feet closed at about $1.4 million, around $397 a square foot
  • Siena at Bella Collina, the condominiums on Lake Siena, at about $420,000 for about 1,550 square feet
  • The Lake Apopka shore, the rare houses on the big lake itself, a handful of large lakefront sales in a year

Against the rival communities on the same window, the estate sections now sell for more per square foot than Keene's Pointe or Bay Hill, and for less than Isleworth.

Bella Collina vs. Windermere vs. Dr. Phillips: The Honest Comparison

 Bella CollinaWindermereDr. Phillips
Median asking price$1,825,000$1,220,000$625,000
Median $/sq ft$474$350$313
Mean commute34.9 minutes30.9 minutes24.2 minutes
Median household income$124,495$156,042$101,540
Population4,2803,03412,458

Windermere is the established luxury town, with Isleworth and Keene's Pointe, far more resale, faster sales and new houses at a much lower price per square foot. Dr. Phillips has Bay Hill, the shortest commute of the three and very little new construction. Bella Collina is the gated golf community where the new luxury building is still happening, at the highest price per square foot for new homes of the three.

Schools, Commute, and Day-to-Day Life

Lake County Schools serves the city, and assignment varies by address rather than by city name, so confirm the zoning for the specific property before you buy on a school reputation.

Mean travel time to work is 34.9 minutes, against 30.9 from Windermere.

How Much of Bella Collina Is New Construction?

Bella Collina has no municipal police agency reporting usable figures to the FBI, so there is no honest city-level crime comparison to publish here, and a number that cannot be sourced is worse than none. What can be measured is the age and type of what is for sale, which is the other question relocation buyers ask.

Across 80 active residential listings, the median asking price is $1,825,000, or $474 per square foot. Where a town is still building, the per square foot figure runs closer to replacement cost; where it is built out, it reflects land and location instead.

Cost of Living in Bella Collina, FL

Housing is the line that moves a Central Florida budget. Bella Collina's median asking price is $1,825,000 against a median household income of $124,495, which puts a home at about 14.66 times household income here. That ratio, rather than the sticker price, is the number worth carrying between towns, and it is why a cheaper town is not automatically a more affordable one. The income figure covers the whole Montverde zip, not Bella Collina's own households, so read this ratio as a rough marker rather than a measure of who buys here.

Florida charges no state income tax, so the property tax line matters more here than it would elsewhere, and a homestead exemption reduces the taxable value of a primary residence. Millage varies by taxing district, so treat any single quoted rate as an estimate until the specific parcel is checked.

Frequently Asked Questions

Is Bella Collina, FL a good place to live?

It depends on whether your income comes with you. Against the 60 places this site tracks across Orange, Seminole, Lake and Volusia counties, with that group's middle last measured on October 9, 2026, the median asking price of $1,825,000 is higher than most and the mean commute of 34.9 minutes is longer than most. The median household income for the whole surrounding zip, not this community alone, is $124,495, which puts housing at 14.66 times income, a heavier load than in most of those places. For remote workers and retirees who bring their income with them, that matters less. For someone earning a local wage, it is one of the harder places in the group to buy. Who it fits, and who it does not, is laid out at the top of this page.

What is the median home price in Bella Collina, FL?

The median sale price was $1,900,000 in September 2026 across 4 closed sales. Over the last twelve months 83 homes sold at a median of $1,700,000. New construction was 70% of sales in the twelve months before and 36% in the last twelve, so the two medians describe different homes and no year-over-year change is quoted here. The median asking price across 80 active listings is $1,825,000, or $474 per square foot.

Is Bella Collina cheaper than Windermere?

On the asking median, no: $1,825,000 against $1,220,000. Measured against household income, Bella Collina is at 14.66 times income and Windermere at 7.82, so on that basis Windermere is the more affordable of the two. See what $2,250,000 buys in each town.

What is the cost of living in Bella Collina, FL?

Housing is the deciding line. A median asking price of $1,825,000 against a median household income of $124,495 puts a home at roughly 14.66 times income, and Florida charges no state income tax, which shifts weight onto the property tax line.

What school district serves Bella Collina, FL?

Lake County Schools. Assignment varies by address within the city, so confirm the zoning for the specific property.

Thinking About a Move to Bella Collina?

I work these four counties every week and I will tell you when a town is wrong for you. If you want the numbers for your budget before you tour anything, start with what $2,250,000 buys across Bella Collina and its neighbors, or call me at 407-616-9019.

You can also browse homes for sale in Bella Collina, which updates with current inventory.

Nov. 1, 2026

Living in Howey-in-the-Hills, FL: Who It Fits, and Who Should Look Elsewhere

Dock on Little Lake Harris at Howey-in-the-Hills, Florida
Photo: Magglefuzz, CC BY-SA 4.0, via Wikimedia Commons

Howey-in-the-Hills is a small lake town in central Lake County, best known for the Mission Inn resort and its golf, and its market has turned toward new construction. A third of the homes sold under its address in the last twelve months were brand new, a larger share than in Tavares or Clermont, and those new houses came in at the lowest price per square foot of the three. The catch is pace: they were also the slowest to sell. Beyond the subdivisions, acreage and homes with no association make up a larger share of sales here than in either rival.

A note on scope: home sales on this page are counted by the Howey-in-the-Hills mailing address, zip 34737, which reaches well beyond the town limits; the population, income and commute figures describe the town itself.

$370,000
Median Sale Price
September 2026, 15 closed sales
2,279
Population
U.S. Census ACS 2023, up 42.7% since 2019
58
Active Listings
Active residential listings in the city, October 23, 2026
30.2 min
Mean Commute
Against 26.0 minutes from Tavares

Who Howey-in-the-Hills Fits, and Who It Doesn't

Strong fit: buyers who want a large new house for the money, since a new house here cost less per square foot than one in Tavares and far less than one in Clermont; buyers who can take their time with a builder, since new houses here took about three months to go under contract; buyers who want land or no association, since both are a larger share here than in Tavares or Clermont, with an acre or more closing at about $662,000; and golfers drawn to the Mission Inn.

Weaker fit: anyone who wants a big market with lots of choice, which means Clermont; buyers who want shopping and restaurants in town, since Howey is a small town and most errands mean a drive; buyers who need to resell quickly, since resale homes here were the slowest of the three to go under contract; and buyers who assume a Howey address means the town itself, since most homes with this address sit outside the town limits.

Still deciding between towns? We pulled the closed sales around a $400,000 budget and put Howey-in-the-Hills side by side with its neighbors: what $400,000 actually buys in each. Square footage, bedrooms, year built, and how many came with a pool.

Where Is Howey-in-the-Hills, and What Makes It Different?

Howey-in-the-Hills is a small town in central Lake County on Little Lake Harris, south of Tavares and north of Clermont, home of the Mission Inn resort, with its own police department. The mean commute is 30.2 minutes.

Howey-in-the-Hills Housing Market Snapshot (2026)

Over the last twelve months 118 homes sold in Howey-in-the-Hills at a median of $382,499, about the same as the twelve months before. Per square foot, which strips out any change in the size of what sold, the figure rose 8.4%. In September 2026, 15 homes closed at a median of $370,000 and the typical one went under contract in 85 days. One month is too small a sample to read a direction from, which is why the twelve-month figure leads here. That twelve-month median rests on 118 sales, a small sample for a percentage, so read it as directional rather than precise. There are 58 active residential listings as of October 23, 2026, with a median asking price of $402,495, or $195 per square foot.

Wondering whether it is a buyer's or seller's market around Howey-in-the-Hills? We publish that answer for Lake County as a whole, from current MLS data: Is Lake County a buyer's or seller's market?

New Construction and Resale Are Not the Same Market

Every price figure quoted for Howey-in-the-Hills mixes brand new homes with existing ones. Split apart, the last twelve months looked like this.

What soldMedian, prior 12 monthsMedian, last 12 monthsChangeSales
New construction$332,292$366,490+10.3%40
Existing homes (resale)$455,000$417,500-8.2%78
All sales combined$380,000$382,499+0.7%118

Read the new-construction row carefully. It rests on fewer than 50 sales in at least one of the two years. The median new-construction home sold in Howey-in-the-Hills went from 1,758 square feet to 2,105, 19.7% larger, while the price per square foot moved +0.6%. That is too few to say whether the change is a price move or a change in which homes sold.

The new construction row rests on fewer than 50 sales in at least one of the two years, so read that change as noise rather than a trend.

Best Neighborhoods in Howey-in-the-Hills, FL: Communities to Know

Howey-in-the-Hills is a small historic town surrounded by new subdivisions and rural land that share its address.

  • Eagletail Landing, the largest new subdivision with a Howey address, where new houses of about 2,200 square feet closed at about $375,000
  • Hodges Reserve, another new subdivision, at about $359,000, though its houses typically took more than five months to go under contract
  • Las Colinas and Venezia, the established subdivisions built in the 2000s and 2010s, at about $395,000 in Venezia South and about $541,000 in Las Colinas, which sold in about seven weeks
  • The old town and the lakes, the original streets near Little Lake Harris, including Howey Emery Heights and Howey Palm Gardens, where the town's older houses stand; across the zip, homes built before 1980 closed at about $280,000, and the few lakefront sales went much higher
  • The acreage, rural parcels around town, where an acre or more typically closed at about $662,000

If you want to live inside the town itself rather than in a subdivision that shares its address, check the parcel, because most Howey-address homes are outside the town limits.

The 15 communities in Howey-in-the-Hills where the most homes have sold over the last twelve months, each with its own page:

Another 11 Howey-in-the-Hills communities have their own page too. You can also browse every Howey-in-the-Hills listing in one place.

Howey-in-the-Hills vs. Tavares vs. Clermont: The Honest Comparison

 Howey-in-the-HillsTavaresClermont
Median asking price$402,495$329,949$455,000
Median $/sq ft$195$188$228
Mean commute30.2 minutes26.0 minutes32.6 minutes
Median household income$93,403$57,644$79,789
Population2,27919,73844,984

Tavares is the county seat next door, with more choice, a downtown on Lake Dora and slightly smaller new houses that sell faster. Clermont is the large market to the south, with the most new construction by volume, the quickest sales and the highest price per square foot. Howey-in-the-Hills is the small town with the largest share of new homes and of acreage, and the lowest price per square foot for a new house of the three, if you can wait for the right one.

Schools, Commute, and Day-to-Day Life

Lake County Schools serves the city, and assignment varies by address rather than by city name, so confirm the zoning for the specific property before you buy on a school reputation.

Mean travel time to work is 30.2 minutes, against 26.0 from Tavares.

How Much of Howey-in-the-Hills Is New Construction?

Howey-in-the-Hills has its own police department, but the FBI's crime data holds no usable annual figure for it in the years checked, so there is no honest town-level crime comparison to publish here, and a number that cannot be sourced is worse than none. What can be measured is the age and type of what is for sale, which is the other question relocation buyers ask.

Across 58 active residential listings, the median asking price is $402,495, or $195 per square foot. Where a town is still building, the per square foot figure runs closer to replacement cost; where it is built out, it reflects land and location instead.

Cost of Living in Howey-in-the-Hills, FL

Housing is the line that moves a Central Florida budget. Howey-in-the-Hills' median asking price is $402,495 against a median household income of $93,403, which puts a home at about 4.31 times household income here. That ratio, rather than the sticker price, is the number worth carrying between towns, and it is why a cheaper town is not automatically a more affordable one.

Florida charges no state income tax, so the property tax line matters more here than it would elsewhere, and a homestead exemption reduces the taxable value of a primary residence. Millage varies by taxing district, so treat any single quoted rate as an estimate until the specific parcel is checked.

Frequently Asked Questions

Is Howey-in-the-Hills, FL a good place to live?

Start with the numbers. Against the 60 places this site tracks across Orange, Seminole, Lake and Volusia counties, with that group's middle last measured on October 9, 2026, the median asking price of $402,495 is near the middle and the mean commute of 30.2 minutes is longer than most. The median household income here is $93,403, which puts housing at 4.31 times income, a lighter load than in most of those places. On local incomes, that makes buying here easier than in most of the group. Who it fits, and who it does not, is laid out at the top of this page.

What is the median home price in Howey-in-the-Hills, FL?

The median sale price was $370,000 in September 2026 across 15 closed sales. Over the last twelve months 118 homes sold at a median of $382,499, about the same as the twelve months before. The median asking price across 58 active listings is $402,495, or $195 per square foot.

Is Howey-in-the-Hills cheaper than Tavares?

On the asking median, no: $402,495 against $329,949. Measured against household income, Howey-in-the-Hills is at 4.31 times income and Tavares at 5.72, so on that basis Howey-in-the-Hills is the more affordable of the two. See what $400,000 buys in each town.

What is the cost of living in Howey-in-the-Hills, FL?

Housing is the deciding line. A median asking price of $402,495 against a median household income of $93,403 puts a home at roughly 4.31 times income, and Florida charges no state income tax, which shifts weight onto the property tax line.

What school district serves Howey-in-the-Hills, FL?

Lake County Schools. Assignment varies by address within the city, so confirm the zoning for the specific property.

Thinking About a Move to Howey-in-the-Hills?

I work these four counties every week and I will tell you when a town is wrong for you. If you want the numbers for your budget before you tour anything, start with what $400,000 buys across Howey-in-the-Hills and its neighbors, or call me at 407-616-9019.

You can also browse homes for sale in Howey-in-the-Hills, which updates with current inventory.

Nov. 1, 2026

Orange County Shed 117 Price Cuts This Week While Lake and Volusia Added Them

By Brenden Rendo, Realtor · Updated November 1, 2026

There are 1,247 listings on this week's price-cut list across Orange, Seminole, Volusia and Lake counties as of November 1, 2026, at an average 3.31% off list. That total is not the interesting part. Orange County came in with 117 fewer homes on this week's price-cut list than the week before, by far the largest county move on the board, while Volusia County had 21 more and Lake County had 11 more. The two counties that grew are also the two where the longest-sitting inventory is concentrated.

1,247
Homes on This Week's List
Orange, Seminole, Volusia and Lake counties, Stellar MLS, November 1, 2026.
3.31%
Average Cut Off List
Counties run from 3.03% in Orange to 3.51% in Seminole.
57.74%
Listed 60 Days or Longer
Share of this week's reduced listings. This is the tier where sellers start negotiating terms.
117
Fewer Homes in Orange County
On this week's list than the week before. Orange still holds the largest pool at 516.
TLDR:
  • 1,247 listings across the four counties are on this week's price-cut list, at an average 3.31% off list.
  • Orange County came in with 117 fewer homes than the week before. Seminole County had 10 fewer, Volusia County 21 more, Lake County 11 more.
  • 57.74% of the reduced listings have been on the market 60 days or longer. That is the tier where negotiation moves from price to terms.
  • Lake County and Volusia County both grew this week and both run the highest 60-day shares, at 61.86% and 60.32%.
  • Realtor.com's September 2026 county series puts all four counties above the 20.1% Florida price-cut share and above the 20.8% national share.

What actually changed this week

Two counties added homes to the price-cut list and two came in with fewer. Volusia County had 21 more than the week before and Lake County had 11 more. Seminole County had 10 fewer, which is noise in a pool of 188. Orange County had 117 fewer, which is not noise in any pool.

Before anyone reads a story into that Orange number, here is exactly what the list is. Each list counts homes still for sale on the pull date whose latest price change, within the 7-day window ending that day, was a cut. A longer list means more listed homes took a cut in that window; a shorter one means fewer did. Neither means homes sold.

That distinction is the whole reason I publish the definition every week. A list that comes in 117 shorter is not evidence that Orange County inventory cleared, and it is not evidence that sellers stopped discounting either. It means that in the seven days ending November 1, fewer Orange County listings recorded a price cut as their most recent price change than did in the seven days before. Where those homes went, under contract, withdrawn, or simply sitting at an unchanged price, is a question this report cannot answer. The closed-sales data answers it a month later.

What the list does tell you, right now, is where sellers have publicly moved. 1,247 of them have, at an average 3.31% off list.

County by county

County On this week's list Change vs. last week Average cut Listed 60+ days
Orange516117 fewer3.03%54.65%
Lake29111 more3.50%61.86%
Volusia25221 more3.49%60.32%
Seminole18810 fewer3.51%56.38%

Orange County still holds the largest pool at 516 listings and the shallowest average cut at 3.03% off list. It also runs the lowest share of long-sitting inventory of the four, at 54.65% past 60 days. If you are shopping the metro core, you are shopping the biggest selection and the thinnest discounts at the same time. See the current Orange County price-reduced listings.

Lake County is the one I would look at hardest this week. It holds 291 listings at an average 3.50% off list, and 61.86% of them have been on the market 60 days or longer, the highest share of any county here. A deep average cut paired with the highest stale share is the combination that produces concessions rather than another price drop. Browse Lake County price-reduced homes.

Volusia County holds 252 listings at 3.49% off list with 60.32% past 60 days, and it added 21 homes to the list this week. The coastal submarkets carry most of that weight. See Volusia County price reductions.

Seminole County is the smallest pool at 188 listings and carries the deepest average cut at 3.51% off list. Fewer choices, bigger adjustments on the ones that are there. Its 56.38% stale share sits between Orange and the two outer counties. Check Seminole County homes with a price reduction.

Quick Tip: A county average is a poor guide to any single house. Inside a county the spread between cities is wider than the spread between the counties themselves. Ask for the city-level pull before you anchor on a number.

How the four counties compare nationally

The weekly list above is a 7-day window. To see whether Central Florida is unusual or just normal, you need a measure that runs the same way everywhere, and Realtor.com publishes one: a monthly count of listings that took a price reduction, on a single definition, for every county, state and the nation. September 2026 is the latest month.

Realtor.com price-cut share, September 2026

Area Listings with a price cut Active listings Share with a price cut Share vs. a year ago
Orange County2,0245,55422.3%-0.4 pp
Seminole County7381,65226.3%-3.9 pp
Lake County9762,51323.1%+0.4 pp
Volusia County1,4304,17122.8%-0.1 pp
Florida45,882146,47820.1%-0.4 pp
United States407,0281,161,61520.8%+0.9 pp

Source: Realtor.com Residential Listings Database, monthly inventory metrics, September 2026. The share is Realtor.com's published price-reduced share for the month. It is not the count divided by active listings, and this report does not derive it. The weekly list at the top of this post is a 7-day window from Stellar MLS and is a different measure, so the two should not be compared directly.

Read on the same definition, Realtor.com shows all four counties running above the Florida share of 20.1% and all four running above the national share of 20.8%, with Seminole County highest at 26.3% and Orange County lowest at 22.3%. Central Florida is a market where price cuts are more common than the state or national baseline, which is the structural fact underneath every weekly number in this report.

The 60-day line is where leverage lives

57.74% of this week's reduced listings have been on the market 60 days or longer. That is the single number I watch most closely, and it is the one that separates a list of discounts from a list of actual opportunities.

A price cut tells you a seller adjusted once. Time on market tells you how much conviction they have left. By day 60 a seller has watched two months of showings fail to produce an offer, has probably already taken one reduction, and is running out of appetite for another. What tends to open up at that point is not a third price drop. It is closing cost assistance, a temporary rate buydown, a repair credit, or a closing date that lets them sequence their own move without carrying two payments.

The county spread on that measure is what makes this week worth reading twice. Lake County sits at 61.86% and Volusia County at 60.32%, against 54.65% in Orange County. The two counties with the most long-sitting inventory are the same two that added homes to the list this week. Concessions rarely show up in list-price data, which is exactly why the 60-day share is more useful to a buyer than the discount percentage. With Freddie Mac's Primary Mortgage Market Survey still the number most buyers anchor on, a seller-funded buydown on a stale listing can be worth more per month than another trim off the price.

Pro Move: On a listing past 60 days, ask what the seller's next move is before you send a number. A seller who has already scheduled their own closing elsewhere will trade terms far more readily than one who is still deciding whether to sell at all. The listing data will not tell you which one you are dealing with. A phone call to the listing agent will.

What this means for buyers, sellers and investors

If you are buying: you have 1,247 sellers across four counties who have publicly signaled flexibility, and 57.74% of them have been waiting more than two months. Filter for time on market first and discount depth second. In Lake County, where 61.86% of the reduced listings are past 60 days, you are more likely to find a seller ready to talk terms than in Orange County at 54.65%, even though Orange offers the larger selection at 516 listings.

If you are selling: Realtor.com's September read puts your county above both the state and national price-cut share, so the buyer you are courting has more discounted options than the average American buyer does. The homes that sell here are the ones priced against what is actually moving, not against what a neighbor listed for in the spring. If your listing is approaching day 45 without meaningful showing activity, the market is giving you a signal. Start with a realistic read on value from the home value estimator, then let us pressure-test it against what has actually closed nearby.

If you are investing: Lake County at 3.50% average off list with 61.86% past 60 days is the most interesting pairing in the table, because the deepest discounting sits alongside the longest waiting. Seminole County carries the deepest average cut at 3.51% but the smallest pool at 188 listings, so sourcing there takes patience. The National Association of Realtors research library is a useful cross-check on where national demand is trending before you commit to a submarket.

All weekly figures in this report come from Stellar MLS data pulled November 1, 2026, covering homes still for sale whose latest price change in the preceding 7 days was a cut, in Orange, Seminole, Volusia and Lake counties. Osceola County is not included. For the running four-county picture, see the Central Florida housing market report.

Frequently asked questions

How many Central Florida homes are on this week's price-cut list?
As of November 1, 2026, 1,247 listings across Orange, Seminole, Volusia and Lake counties are on this week's price-cut list, at an average 3.31% off list, per Stellar MLS data.

Which county moved the most this week?
Orange County. Its list holds 516 homes, which is 117 fewer homes on this week's price-cut list than the week before. Seminole County came in with 10 fewer, while Volusia County had 21 more and Lake County had 11 more.

Which Central Florida county has the deepest average price cut?
Seminole County, at an average 3.51% off list across 188 listings. Orange County runs the shallowest at 3.03% across 516 listings, with Lake County at 3.50% and Volusia County at 3.49%.

Why does days on market matter more than the size of the price cut?
A price cut tells you a seller adjusted once. Days on market tells you how long they have been waiting. 57.74% of this week's reduced listings have been on the market 60 days or longer, and Lake County runs highest at 61.86%. By that point a seller has usually run out of patience for another price drop and starts weighing concessions instead, such as closing cost assistance, a rate buydown, or a repair credit.

Which counties does this report cover?
Orange, Seminole, Volusia and Lake counties. Osceola County is not included.

Want the city-level breakdown for the county you are shopping? Call or text me at 407-616-9019 and tell me which one. I will pull the current list, including how long each home has been sitting, and we can work out which sellers are actually in a position to move on terms.

Oct. 31, 2026

NAR Says Home Prices Rose, Redfin Says They Fell. Here Is What Central Florida Shows.

By Brenden Rendo, Realtor · Updated October 31, 2026

Two housing reports landed on the same day, October 29, and they sound like opposites. The National Association of REALTORS said home prices rose in 78% of U.S. metro areas in the third quarter. Redfin's headline said U.S. home-sale prices had just fallen for the first time in three years. If you are buying or selling in Orange, Seminole, Lake or Volusia County, which headline is yours? I pulled the closed sales for July, August and September to find out.

+1.7%
NAR: U.S. Median Price, Q3 Year Over Year
Existing single-family median of $432,900 (NAR, October 29, 2026)
-0.1%
Redfin: U.S. Median Sale Price, Year Over Year
Median of $389,601, four weeks ending Oct. 25 (Redfin, October 29, 2026)
5 up, 4 down, 3 flat
Local Median Price Readings, Jul to Sep
4 counties x 3 months, year over year (Stellar MLS closed sales)
3.76 to 4.48
Months of Supply, July to September
Four-county total, Stellar MLS
TLDR:
  • NAR reported a 1.7% national gain in the third-quarter median price. Redfin reported a 0.1% national dip. Both are close to flat.
  • In Orange, Seminole, Lake and Volusia, median closed prices moved between -2.55% and +5.96% from a year earlier, with no steady direction. Of 12 monthly readings, 5 were up, 4 were down and 3 were flat.
  • Prices held about even while the market slowed: months of supply rose from 3.76 in July to 4.48 in September, and September closed sales across the four counties were 5.42% below a year earlier.
  • For buyers, that means more time to compare and decide. For sellers, it means the asking price matters more than it did in July.

Two headlines, one quarter

NAR's third-quarter report put the national median single-family existing-home price at $432,900, up 1.7% from a year earlier, with prices rising in 78% of metro areas. For the South region, NAR showed $374,900, up 1.0%. NAR Chief Economist Lawrence Yun said that homes in nearly all Florida markets are showing price gains this quarter after a year in which prices declined in many of them. You can read the full release on the NAR newsroom.

Redfin's October 29 update measured something different. It put the U.S. median sale price at $389,601, down 0.1% from a year earlier, and headlined it as the first fall in three years. Redfin's figure covers the four weeks ending October 25, after the quarter closed, and it was the second straight weekly dip, after -0.2% the week before.

Read side by side, the gap is smaller than the headlines suggest. One report shows a gain of 1.7% and the other a drop of about 0.1%. Neither describes a surge or a slide. They also measure different things: NAR tracks single-family existing homes by quarter, while Redfin reports homes sold in a rolling four-week window across 900+ metro areas. That is a good reason to look at actual closed sales near you.

What Central Florida closed sales show

I pulled every closed residential sale (single-family homes, condos and townhomes) in Orange, Seminole, Lake and Volusia counties from Stellar MLS for July, August and September 2026, and compared each month's median closed price with the same month a year earlier. Osceola County is not included.

County July median (YoY) August median (YoY) September median (YoY)
Orange $440,000 (-1.35%) $425,000 (0.00%) $444,995 (+2.00%)
Seminole $439,727 (+5.96%) $420,000 (0.00%) $393,500 (-2.55%)
Lake $365,000 (-2.52%) $375,000 (0.00%) $370,000 (+0.15%)
Volusia $345,000 (+2.99%) $340,000 (+2.65%) $340,000 (-0.98%)
All four counties $399,994 $390,000 $390,000

Source: Stellar MLS closed residential sales, July through September 2026. Year-over-year change compares each month with the same month in 2025. The all-county row is one pooled median across all four counties, not an average of the county medians.

Three of the twelve readings landed at exactly 0.00%. In August the Orange, Seminole and Lake medians were each identical to the year-earlier median: $425,000, $420,000 and $375,000. Median prices tend to cluster at round numbers, so that is not unusual, but it shows how little movement there was.

Quick Tip: A single month's median can swing several points because of which homes happened to close. Look at three months and compare the same month a year apart before you decide a market is rising or falling.

County by county

  • Orange: The median ended the quarter up 2.00% in September to $444,995, but closed sales were down 5.19% (1,280 against 1,350 a year earlier). Higher prices on fewer sales is not the same as a hot market.
  • Seminole: The strongest month was July, up 5.96% to $439,727. August was flat and September was down 2.55% to $393,500. The year-over-year reading weakened each month.
  • Lake: The steadiest county. Medians sat within 2.52% of last year in every month and finished September at $370,000, up 0.15%.
  • Volusia: Up in July and August, down 0.98% in September to $340,000. Closed sales fell 14.13% in September (626 against 729), the sharpest drop of the four counties.

Why the two reports do not match

Three differences matter when you compare any national report with local sales:

  • Different homes. NAR reports single-family existing homes. My table counts all closed residential sales, so condos and townhomes pull the median down. In September the four-county median for single-family homes alone was $430,000, against $390,000 for everything.
  • Different footprints. NAR reports by metropolitan area. The Orlando-Kissimmee-Sanford metro includes Osceola County, and Volusia sits in the separate Deltona-Daytona Beach-Ormond Beach metro. Our four counties are not one NAR metro.
  • Different timing. A third-quarter median and a rolling four-week one from late October can point in different directions when prices are close to flat.

Because of that, I am not claiming that either national report is wrong. I am saying that a 1.7% national gain or a 0.1% national dip tells you very little about your street. The local numbers above are the better guide, and they say the market is holding steady rather than rebounding.

What this means for buyers

Prices did not run away from buyers this quarter, and sales slowed. Across the four counties, months of supply rose from 3.76 in July to 4.11 in August and 4.48 in September, while the average time from listing to contract went from 67.9 days in July to 72.1 days in September. Total closed sales fell from 3,568 in July to 3,034 in September, 5.42% below September 2025, while inventory held near 13,400 to 13,600 homes. That gives you more time to compare and decide, but it does not mean every home is discounted. Homes priced well still sell, and homes priced high sit.

If you are shopping, the practical move is to look at homes that have already cut their price. I track those weekly for each county: Orange, Seminole, Lake and Volusia.

What this means for sellers

A flat market with slower sales rewards accurate pricing. With closed sales down in three of four counties in September and homes taking about four days longer to go under contract than in July, a price set off last spring's sales deserves a second look before you list. Prices in your neighborhood may be moving differently from the county median, so start with comparable sales close to your home, not a headline.

Pro Move: Before you list, ask for the sold prices and days to contract on the three or four closest comparable homes from the last 90 days. Those tell you more than any county or national median.

For the broader picture, see the Central Florida housing market page, or find out what your own home is worth with the home value estimator.

Thinking about buying or selling in Orange, Seminole, Lake or Volusia County? Call or text Brenden Rendo at 407-616-9019, or send a message, and I will pull the comparable sales for your street.

Local figures are from Stellar MLS closed residential sales for July through September 2026 (Orange, Seminole, Lake and Volusia counties), pulled between August 27 and October 8, 2026. National figures are from the National Association of REALTORS (October 29, 2026) and Redfin (October 29, 2026). Past sales do not predict future prices.