Area Real Estate News & Market Trends

You’ll find our blog to be a wealth of information, covering everything from local market statistics and home values to community happenings. That’s because we care about the community and want to help you find your place in it. Please reach out if you have any questions at all. We’d love to talk with you!

Oct. 9, 2026

Living in Lady Lake, FL: Who It Fits, and Who Should Look Elsewhere

Lady Lake is the town The Villages grew out of, and the two are hard to separate on a map or in a listing search. The largest single block of homes that sold with a Lady Lake address in the last twelve months was Orange Blossom Gardens, the original section of The Villages, at about $205,000. Around it is a general-market town with its own new subdivisions near $320,000 and a gated golf community on Lake Griffin near $475,000. Which of those three a buyer means by Lady Lake decides everything else on this page.

$304,900
Median Sale Price
August 2026, 40 closed sales
16,337
Population
U.S. Census ACS 2023, up 5.9% since 2019
157
Active Listings
Active residential listings in the city, October 9, 2026
17.5 min
Mean Commute
Against 20.9 minutes from The Villages

Who Lady Lake Fits, and Who It Doesn't

Strong fit: buyers over 55 who want The Villages at the low end of its prices, because Orange Blossom Gardens closed 73 homes at $205,000 and the age-restricted market as a whole 106 at $225,000; buyers of any age who want a new house in the low $300,000s without an age limit, since Green Key Village and the Reserves at Hammock Oaks closed 66 between them at about $313,000 to $330,000 and went under contract in about a month; golf and lake buyers who want a gated community that is not The Villages, with Harbor Hills at 60 closings and about $475,000; and anyone who wants the shopping and medical offices of the US-27 and 441 corridor a few minutes away.

Weaker fit: buyers under 55 who do not filter for age restrictions, because more than a quarter of what sells here is not available to them; anyone expecting a new home to resell at a premium, since new construction closed at $173 per square foot against $187 for resale and the builders are still active; buyers of the smallest new homes at Hammock Oaks, townhomes included, which took about four months to go under contract; working commuters to Orlando, because the short commute figure here reflects a largely retired population and not a short drive; and anyone who wants a traditional downtown, which Lady Lake does not really have.

Still deciding between towns? We pulled the closed sales around a $325,000 budget and put Lady Lake side by side with its neighbors: what $325,000 actually buys in each. Square footage, bedrooms, year built, and how many came with a pool.

Where Is Lady Lake, and What Makes It Different?

Lady Lake sits in the northwest corner of Lake County where US-27 and US-441 run together, directly against The Villages, with Lake Griffin to its east and Leesburg to the south. The commercial strip along the highway serves both communities. The mean commute is 17.5 minutes, the shortest of any town in this series, and that describes who lives here more than it describes the roads: a large share of residents are retired.

Lady Lake Housing Market Snapshot (2026)

Over the last twelve months 384 homes sold in Lady Lake at a median of $304,990. New construction was 5% of sales in the twelve months before and 27% in the last twelve, so the two medians describe different homes and no year-over-year change is quoted here. In August 2026, 40 homes closed at a median of $304,900 and the typical one went under contract in 71 days. One month is too small a sample to read a direction from, which is why the twelve-month figure leads here. There are 157 active residential listings as of October 9, 2026, with a median asking price of $358,400, or $205 per square foot.

Wondering whether it is a buyer's or seller's market around Lady Lake? We publish that answer for Lake County as a whole, from current MLS data: Is Lake County a buyer's or seller's market?

New Construction and Resale Are Not the Same Market

Every price figure quoted for Lady Lake mixes brand new homes with existing ones. Split apart, the last twelve months looked like this.

What soldMedian, prior 12 monthsMedian, last 12 monthsChangeSales
New construction$320,000$319,9900.0%105
Existing homes (resale)$298,750$280,000-6.3%279
All sales combined$299,500$304,990+1.8%384

Neither row rose, yet the combined figure rose 1.8%. A combined median can do that when the mix of what sold changes: new construction was 27% of sales against 5% the year before. Read the two rows separately here; the combined figure is describing which homes sold, not what they cost.

Best Neighborhoods in Lady Lake, FL: Communities to Know

Lady Lake is three markets, and one of them is really The Villages.

  • Orange Blossom Gardens and The Villages addresses, the original section of The Villages on the east side of US-27 and 441, age-restricted, a mix of manufactured and small site-built homes mostly from the 1980s: 73 closings at $205,000, with another 16 labeled simply The Villages at $255,000
  • The new subdivisions, Green Key Village and the Reserves at Hammock Oaks, both south of the town center: Green Key closed 29 at $329,990 and Hammock Oaks 37 at $312,990, each in about a month, while the smaller homes sold as The Reserve at Hammock Oaks, 16 at $247,392, took about four months
  • Harbor Hills, the gated golf and boating community on Lake Griffin east of town: 60 closings at about $475,000, mostly houses from the 2000s on about 2,400 square feet, taking about two months to go under contract; the 10 waterfront sales citywide closed at $592,500
  • The older town and the acreage, general-market resale outside the gates: Carlton Village closed 15 at $250,000 with no association, and the 37 homes on an acre or more closed at $429,900 after about three and a half months

If The Villages is the goal, know that the Lady Lake address covers only its oldest corner. If it is not, filter the age-restricted listings out, and the town that remains is a new-construction market with one golf community attached.

The 15 communities in Lady Lake where the most homes have sold over the last twelve months, each with its own page:

Another 19 Lady Lake communities have their own page too. You can also browse every Lady Lake listing in one place.

Lady Lake vs. The Villages vs. Leesburg: The Honest Comparison

 Lady LakeThe VillagesLeesburg
Median asking price$358,400$352,829$289,900
Median $/sq ft$205$239$169
Mean commute17.5 minutes20.9 minutes24.8 minutes
Median household income$47,260$76,523$47,506
Population16,33782,10828,461

The Villages is the reason Lady Lake looks the way it does. Its Lake County homes cost more per square foot and come with the age restriction and the amenity fee, which Lady Lake's own subdivisions do not have. Leesburg is the larger town to the south, with the lowest price per square foot of the three and more than half its sales age-restricted. Lady Lake is the one of the three with the shortest commute, and the one where new construction is the largest share of what sells.

Schools, Commute, and Day-to-Day Life

Lake County Schools serves the city, and assignment varies by address rather than by city name, so confirm the zoning for the specific property before you buy on a school reputation.

Mean travel time to work is 17.5 minutes, against 20.9 from The Villages.

How Much of Lady Lake Is New Construction?

Lady Lake has no municipal police agency reporting usable figures to the FBI, so there is no honest city-level crime comparison to publish here, and a number that cannot be sourced is worse than none. What can be measured is the age and type of what is for sale, which is the other question relocation buyers ask.

Across 157 active residential listings, the median asking price is $358,400, or $205 per square foot. Where a town is still building, the per square foot figure runs closer to replacement cost; where it is built out, it reflects land and location instead.

Cost of Living in Lady Lake, FL

Housing is the line that moves a Central Florida budget. Lady Lake's median asking price is $358,400 against a median household income of $47,260, which puts a home at about 7.58 times household income here. That ratio, rather than the sticker price, is the number worth carrying between towns, and it is why a cheaper town is not automatically a more affordable one. In Lady Lake that ratio needs a caveat, because more than a quarter of this market is age-restricted and The Villages is next door, so many buyers arrive with cash from selling a house somewhere else rather than qualifying on local wages. Read the ratio as a description of the resident population, not of what a buyer can afford.

Florida charges no state income tax, so the property tax line matters more here than it would elsewhere, and a homestead exemption reduces the taxable value of a primary residence. Millage varies by taxing district, so treat any single quoted rate as an estimate until the specific parcel is checked.

Frequently Asked Questions

Is Lady Lake, FL a good place to live?

It depends on whether your income comes with you. Against the 60 places this site tracks across Orange, Seminole, Lake and Volusia counties, the median asking price of $358,400 is lower than most and the mean commute of 17.5 minutes is shorter than most. The median household income here is $47,260, which puts housing at 7.58 times income, a heavier load than in most of those places. For remote workers and retirees who bring their income with them, that matters less. For someone earning a local wage, it is tighter than the sticker price suggests. Who it fits, and who it does not, is laid out at the top of this page.

What is the median home price in Lady Lake, FL?

The median sale price was $304,900 in August 2026 across 40 closed sales. Over the last twelve months 384 homes sold at a median of $304,990. New construction was 5% of sales in the twelve months before and 27% in the last twelve, so the two medians describe different homes and no year-over-year change is quoted here. The median asking price across 157 active listings is $358,400, or $205 per square foot.

Is Lady Lake cheaper than The Villages?

On the asking median, about the same: $358,400 against $352,829. Measured against household income, Lady Lake is at 7.58 times income and The Villages at 4.61, so on that basis The Villages is the more affordable of the two. See what $325,000 buys in each town.

What is the cost of living in Lady Lake, FL?

Housing is the deciding line. A median asking price of $358,400 against a median household income of $47,260 puts a home at roughly 7.58 times income, and Florida charges no state income tax, which shifts weight onto the property tax line.

What school district serves Lady Lake, FL?

Lake County Schools. Assignment varies by address within the city, so confirm the zoning for the specific property.

Thinking About a Move to Lady Lake?

I work these four counties every week and I will tell you when a town is wrong for you. If you want the numbers for your budget before you tour anything, start with what $325,000 buys across Lady Lake and its neighbors, or call me at 407-616-9019.

You can also browse homes for sale in Lady Lake, which updates with current inventory.
Oct. 8, 2026

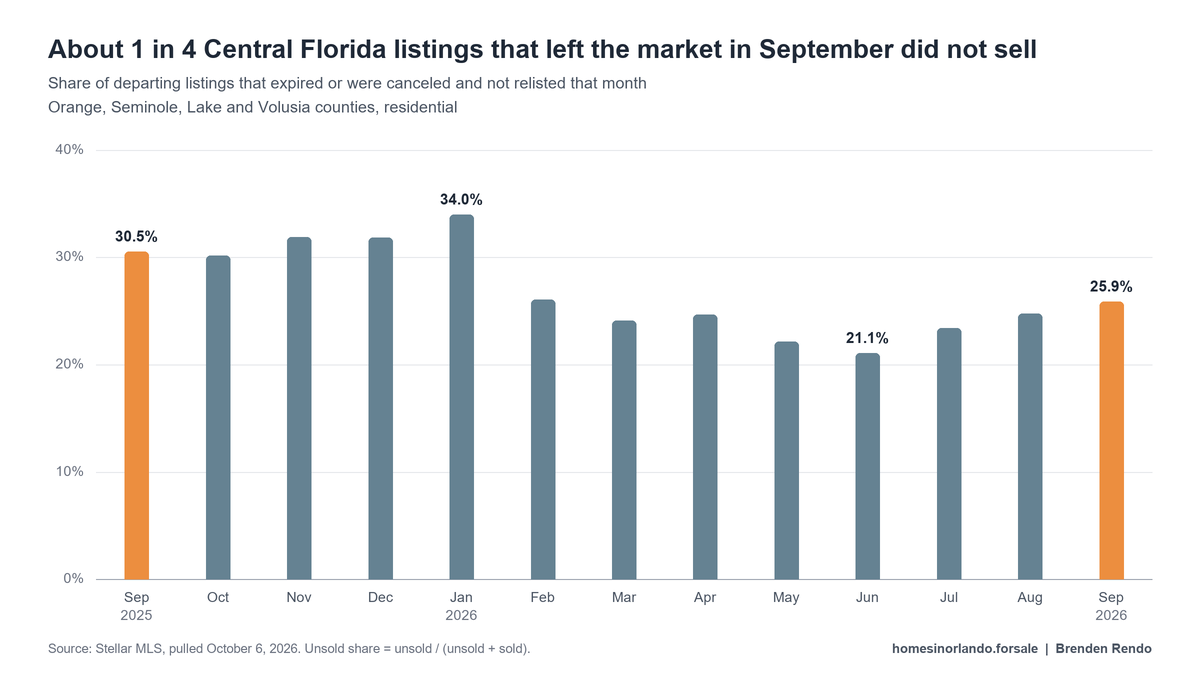
About 1 in 4 Central Florida listings that left the market in September did not sell. A year ago it was about 3 in 10

By Brenden Rendo, Realtor · Updated October 8, 2026

In September, 1,038 Central Florida sellers took the sign out of the yard without a sale. Some listings expired. More were canceled early. It is easy to blame the market. But 2,975 homes did sell in the same four counties in September, in that same market. I pulled every residential listing in Orange, Seminole, Lake, and Volusia that expired or was canceled in September 2026 and was not put back on the market by September 30, and lined it up against every home that closed. About 1 in 4 of the listings that left the market in September left without a sale.

1,038
Listings That Left Unsold in September
393 expired, 645 canceled, none relisted by September 30. Orange, Seminole, Lake, Volusia
2,975
Homes Sold in September
Closed residential sales, same four counties
25.87%
Share of Departing Listings That Did Not Sell
About 1 in 4. September 2025: 30.54%
35.55%
Of the Unsold Never Cut Their Price
Homes that sold closed at a median 95.95% of original asking price
TLDR:
  • 1,038 listings expired or were canceled in September 2026 and were not relisted that month (393 expired, 645 canceled), against 2,975 closed sales. That is 25.87% of the listings that left the market, about 1 in 4.
  • A year earlier, in September 2025, the share was 30.54%. September 2026 is down 4.68 percentage points, and the 7th lowest of the last 13 months.
  • Seminole had the lowest unsold share at 19.67%; Volusia the highest at 27.71%.
  • Condos, townhomes and villas failed at 51.5 per 100 sales, against 30 for houses. By price, $1,000,000 and up was worst at 56.3 per 100.
  • 35.55% of the unsold listings never cut their price. Homes that sold closed at a median 95.95% of their original asking price.

1. September County by County

Here is September by county. "Unsold" means the listing expired or was canceled during the month and the property was not relisted for sale by September 30.

CountyExpiredCanceledUnsold totalSoldShare that left unsoldUnsold per 100 sales
Orange1563114671,26526.96%36.9
Seminole376910643319.67%24.5
Lake8914323266925.75%34.7
Volusia11112223360827.71%38.3
4-county total3936451,0382,97525.87%34.9

Source: Stellar MLS residential listings, Orange, Seminole, Lake, and Volusia counties, September 2026, pulled October 6, 2026. Sold = closings recorded with a September close date as of that day.

Seminole is the best place to be a seller right now by this measure. 19.67% of its departing listings left unsold, 24.5 for every 100 sales. Volusia is the hardest, at 27.71% and 38.3 per 100.

Canceled listings outnumber expired ones 645 to 393. Most sellers who leave unsold do not wait for the agreement to run out.

How I counted: A listing counts as unsold if it expired or was canceled during September, based on the date it actually came off the market, and the property did not get a new for-sale listing by September 30. 114 listings came off and went right back on within the month, and they are left out. Withdrawn listings, which are paused rather than ended, are not counted (119 in September). Listings whose sellers opted out of internet display are excluded. Every month in this report uses the same rules.

2. Is 1 in 4 High? The Last 13 Months

One month is not a market, so here are the same numbers, counted the same way, for every month back to September 2025.

Bar chart: share of Central Florida listings that left the market unsold each month, September 2025 to September 2026. September 2025 30.54%, September 2026 25.87%, high 33.98% in January 2026, low 21.09% in June 2026.

MonthExpiredCanceledUnsold totalSoldShare that left unsold
September 20254918961,3873,15430.54%
October 20255038401,3433,10730.18%
November 20254048231,2272,61931.90%
December 20256738001,4733,15031.86%
January 20263887611,1492,23233.98%
February 20263495899382,66426.04%
March 20263587071,0653,35424.10%
April 20263847081,0923,33424.67%
May 20263466621,0083,54722.13%
June 20263256749993,73721.09%
July 20263617141,0753,51523.42%
August 20263577041,0613,22524.76%
September 20263936451,0382,97525.87%

Source: Stellar MLS, same four counties and the same definitions each month. Each month's relist check runs to the last day of that month.

September 2026's 25.87% is down 4.68 percentage points from September 2025's 30.54%. Over the 12 months before it, the share ran from 21.09% in June 2026 to 33.98% in January 2026, with a median of 25.40%. September 2026 is the 7th lowest of the 13, 0.47 percentage points above that median, and up 1.11 percentage points from August 2026's 24.76%. The year-over-year drop is real, and so is the rise since the June 2026 low. By county, year over year: Orange 30.15% to 26.96%, Seminole 26.45% to 19.67%, Lake 29.26% to 25.75%, Volusia 34.56% to 27.71%.

For a national yardstick, Realtor.com's September 2026 housing report puts delistings at about 5.6% of homes on the market nationally in September, in line with a year earlier. That is a different measure, a share of all active listings rather than of listings that left, so it does not line up with the table above number for number.

3. Where Listings Fail Most: Property Type and Price

Condos and houses are different decisions, so they are counted separately.

Property typeUnsoldSoldShare that left unsoldUnsold per 100 sales
Houses6822,27623.06%30
Condos, townhomes and villas30158434.01%51.5
Condo-hotels, manufactured and other5511532.35%47.8
Original asking priceUnsoldSoldShare that left unsoldUnsold per 100 sales
Under $300,00030870430.43%43.8
$300,000 to $499,9993531,27821.64%27.6
$500,000 to $749,99920059925.03%33.4
$750,000 to $999,9997421125.96%35.1
$1,000,000 and up10318336.01%56.3

Source: Stellar MLS, September 2026. Price bands use each listing's original asking price, so sold and unsold homes are grouped by where they started.

Condos, townhomes and villas fail most often. 51.5 left unsold for every 100 that sold, against 30 for houses. For condos, association dues, insurance, and building inspection requirements all add to a buyer's monthly cost, which narrows the pool of buyers who can say yes.

By price, the $300,000 to $499,999 band works best, at 27.6 unsold per 100 sales. $1,000,000 and up is the hardest, at 56.3 per 100.

4. What the Homes That Sold Did Differently

Here are the 1,038 unsold listings next to the 2,975 sales on the same measures.

Left unsold (1,038)Sold (2,975)
Median original asking price$400,000$409,990
Median original asking price per sq ft$235$234
Reduced the price at least once64.45%75.33% closed below original
Median reduction, those that reduced5.38%closed at 95.95% of original
Median days on the market146 (until it came off)41 (until under contract)

Source: Stellar MLS, September 2026. Price per square foot excludes listings under 200 sq ft or without a size. Days for unsold listings run from going live to coming off; days for sold homes run from going live to going under contract.

The clearest difference is movement. 35.55% of the sellers who left unsold never reduced their price at all. The homes that sold mostly did give ground: 75.33% closed below their original asking price, at a median of 95.95% of it. They went under contract in a median 41 days. The unsold listings had sat a median 146.

What the data does not clearly show, and I checked: that the unsold homes started at much higher prices per square foot. Across all four counties, the median unsold house started 2.94% above the median sold house per square foot, and for condos the gap was 0.35% below. County by county it ranges from -9.94% for Lake condos to +10.98% for Volusia condos. That comparison mixes neighborhoods, so it is a blunt tool. The cleaner signal is the one above: the sellers who sold adjusted, and 35.55% of the ones who quit never did.

5. Expired, Canceled, and the Relist Rule

Two different endings, one result. An expired listing reached the end of its listing agreement unsold. A canceled listing ended early, which can mean the seller switched agents, changed plans, or decided to wait for a better market.

Before the relist rule, 1,152 listings expired or were canceled in September (418 expired, 734 canceled). 114 of them were back on the market for sale by September 30, 89 of those after a cancellation. That is the cancel-and-relist move: same house, new listing. I left those out because those sellers did not stop selling. Another 38 of the unsold properties showed up as rentals in September instead.

6. What Sellers and Buyers Should Do With This

Sellers. The homes that sold in September did not sell at their first price; most closed below it. The sellers who left unsold often never adjusted at all. If your listing expired or you canceled, the next listing has to change something the buyers already told you about: price, condition, or how the home is presented. A new sign on the same house at the same number asks the same buyers the same question. Start with a value estimate, then let me check it against what actually closed near you in the last 90 days.

Buyers. A home that came off the market unsold has an owner who already tried to sell. Some come back later, sometimes at a different price. If you saw a home earlier this year that disappeared from the search, ask me to check its history.

For listings still on the market that have cut their price, see the price-reduced pages for Orange, Seminole, Lake, and Volusia counties, and the Central Florida housing market hub for the monthly picture.

7. Frequently Asked Questions

How many Central Florida listings expired or were canceled in September 2026?

1,038 residential listings in Orange, Seminole, Lake, and Volusia counties expired or were canceled in September 2026 and were not relisted for sale by September 30: 393 expired and 645 canceled. Another 114 came off the market and were relisted within the month, so they are not counted.

What share of listings sold in September?

2,975 homes closed in September 2026 against 1,038 that left the market unsold. Of the listings that left the market either way, 74.13% sold and 25.87% did not, about 1 in 4.

What is the difference between an expired and a canceled listing?

An expired listing reached the end of its listing agreement without selling. A canceled listing ended early, before the agreement ran out, which can mean the seller changed agents, changed plans, or decided to wait. Both left the market without a sale, so this report counts both.

Is that more or less than a year ago?

In September 2025, 30.54% of listings that left the market did so unsold (1,387 unsold against 3,154 sales). In September 2026 it was 25.87%, down 4.68 percentage points.

What did the homes that sold do differently?

The homes that sold closed at a median 95.95% of their original asking price, and 75.33% sold below it. Among the listings that left unsold, 35.55% never reduced their price at all. The sold homes went under contract in a median 41 days; the unsold listings had been on the market a median 146 days when they came off.

Did your listing expire or get canceled?

I will pull your listing's full history, the price changes, the listings it competed against, and what actually sold near you, and tell you plainly what a buyer saw. No listing pitch unless you ask. Call or text Brenden at 407-616-9019.

Contact The Homes In Orlando Team

Oct. 8, 2026

Living in Tavares, FL: Who It Fits, and Who Should Look Elsewhere

Tavares calls itself America's Seaplane City, and the waterfront downtown on Lake Dora earns the name. The housing market behind it is something else. A third of what sold here in the last twelve months was in an age-restricted community, a fifth was a manufactured or mobile home, and more than a quarter was brand new construction. Each of those is a different price and a different buyer, and the citywide median describes the overlap between them, which is small.

$305,000
Median Sale Price
August 2026, 42 closed sales
19,738
Population
U.S. Census ACS 2023, up 17.8% since 2019
246
Active Listings
Active residential listings in the city, October 9, 2026
26.0 min
Mean Commute
Against 24.8 minutes from Leesburg

Who Tavares Fits, and Who It Doesn't

Strong fit: buyers over 55 who want the lakes at a low entry price, because 203 age-restricted homes closed at a median of $205,000, with Lake Frances Estates at $155,000 and Royal Harbor at $330,000 for a site-built house on Lake Harris; buyers who want a new house in the low to mid $300,000s, since Avalon Park Tavares closed more than 100 homes, townhomes included, at about $333,000; boaters and anyone who wants water, with 106 waterfront sales at $418,750, a sixth of the market; and buyers who want room to negotiate, because the typical home here took 62 days to go under contract and some new communities took far longer.

Weaker fit: buyers under 55 who do not filter for it, because a third of what sells here is not available to them; anyone who needs to resell quickly, since Tavares is the slowest of the three Golden Triangle towns and the Seasons communities took from six months to more than a year to put their new homes under contract; buyers shopping under $250,000, where much of the choice is a manufactured or mobile home, which is a different loan and a different resale; and daily commuters to Orlando, for whom Mount Dora's parkway access or Clermont's turnpike is the better starting point.

Still deciding between towns? We pulled the closed sales around a $350,000 budget and put Tavares side by side with its neighbors: what $350,000 actually buys in each. Square footage, bedrooms, year built, and how many came with a pool.

Where Is Tavares, and What Makes It Different?

Tavares is the Lake County seat, on the land between Lake Dora, Lake Eustis and Lake Harris, with US-441 running through it to Mount Dora on one side and Leesburg on the other. The downtown waterfront has the seaplane base, the marina and the county government. The mean commute is 26.0 minutes, close to both of the towns compared here.

Tavares Housing Market Snapshot (2026)

Over the last twelve months 625 homes sold in Tavares at a median of $315,990, down 0.5% against the twelve months before. Per square foot, which strips out any change in the size of what sold, the figure fell 3.2%. In August 2026, 42 homes closed at a median of $305,000 and the typical one went under contract in 85 days. One month is too small a sample to read a direction from, which is why the twelve-month figure leads here. There are 246 active residential listings as of October 9, 2026, with a median asking price of $329,999, or $189 per square foot.

Wondering whether it is a buyer's or seller's market around Tavares? We publish that answer for Lake County as a whole, from current MLS data: Is Lake County a buyer's or seller's market?

New Construction and Resale Are Not the Same Market

Every price figure quoted for Tavares mixes brand new homes with existing ones. Split apart, the last twelve months looked like this.

What soldMedian, prior 12 monthsMedian, last 12 monthsChangeSales
New construction$380,990$360,000-5.5%178
Existing homes (resale)$289,000$290,000+0.3%447
All sales combined$317,500$315,990-0.5%625

Those two rows move in opposite directions. The combined figure is the one every portal quotes for Tavares, and it describes neither half of this market.

Best Neighborhoods in Tavares, FL: Communities to Know

Tavares sorts by who is allowed to buy and by what the house is built of, before it sorts by location.

  • The 55-plus communities, a third of the market, 203 closings at $205,000: Lake Frances Estates closed 47 at $155,000, Fox Run 32 at $197,500 and Imperial Mobile Terrace 30 at $170,000, all manufactured or mobile homes, while Royal Harbor's site-built houses on Lake Harris closed 42 at $330,000 and Baytree 18 at about $241,000
  • The new subdivisions, Avalon Park Tavares, Seaport Village and the Seasons communities: Avalon Park closed more than 100 at about $333,000 and Seaport Village 21 at $354,990, while Seasons at Lakeside Forest, 24 at $399,975, and Seasons at Waterstone, 12 at $429,930, took from six months to more than a year to go under contract
  • The waterfront and the downtown, homes on Lake Dora, Lake Eustis, Lake Harris and the canals between them: 106 waterfront closings at $418,750, and the 32 on an acre or more at $729,000 after more than three months
  • The older general-market neighborhoods, the resale that is not age-restricted, where the 102 homes with no association closed at $347,500 and went under contract in 43 days, well ahead of the city as a whole

Ask two questions of any Tavares listing before the price: is it age-restricted, and is it site-built. Those two answers move the number more than the address does.

The 15 communities in Tavares where the most homes have sold over the last twelve months, each with its own page:

Another 66 Tavares communities have their own page too. You can also browse every Tavares listing in one place.

Tavares vs. Leesburg vs. Eustis: The Honest Comparison

 TavaresLeesburgEustis
Median asking price$329,999$289,900$370,000
Median $/sq ft$189$169$193
Mean commute26.0 minutes24.8 minutes26.8 minutes
Median household income$57,644$47,506$62,475
Population19,73828,46123,567

Leesburg is the same kind of market one town west, with more than half its sales age-restricted and a lower price per square foot. Eustis is the neighbor to the north, with very little 55-plus housing, more acreage and faster sales. Tavares is the one of the three where waterfront is the largest share of what sells, about one sale in six.

Schools, Commute, and Day-to-Day Life

Lake County Schools serves the city, and assignment varies by address rather than by city name, so confirm the zoning for the specific property before you buy on a school reputation.

Mean travel time to work is 26.0 minutes, against 24.8 from Leesburg.

Is Tavares, FL Safe?

Tavares' reported violent crime rate is 66.4 per 100,000 residents against 280.8 for Florida as a whole, about 76% below the state figure. That is a real difference. The same caveat applies in reverse though: rates are measured against resident population, so a town that few people commute into will tend to look better than a comparable one that they do.

Figures are reported offenses from the FBI Crime Data Explorer for the Tavares Police Department (ORI FL0351100), 2023, the most recent year that agency reported in a usable form. Reporting years differ between agencies, so this is compared to the Florida rate for the same year and is not comparable to another town's page.

Cost of Living in Tavares, FL

Housing is the line that moves a Central Florida budget. Tavares' median asking price is $329,999 against a median household income of $57,644, which puts a home at about 5.72 times household income here. That ratio, rather than the sticker price, is the number worth carrying between towns, and it is why a cheaper town is not automatically a more affordable one. In Tavares that ratio needs a caveat, because a third of this market is age-restricted, and many of those buyers arrive with cash from selling a house somewhere else rather than qualifying on local wages. Read the ratio as a description of the resident population, not of what a buyer can afford.

Florida charges no state income tax, so the property tax line matters more here than it would elsewhere, and a homestead exemption reduces the taxable value of a primary residence. Millage varies by taxing district, so treat any single quoted rate as an estimate until the specific parcel is checked.

Frequently Asked Questions

Is Tavares, FL a good place to live?

It depends on whether your income comes with you. Against the 60 places this site tracks across Orange, Seminole, Lake and Volusia counties, the median asking price of $329,999 is lower than most and the mean commute of 26.0 minutes is shorter than most. The median household income here is $57,644, which puts housing at 5.72 times income, a heavier load than in most of those places. For remote workers and retirees who bring their income with them, that matters less. For someone earning a local wage, it is tighter than the sticker price suggests. Who it fits, and who it does not, is laid out at the top of this page.

What is the median home price in Tavares, FL?

The median sale price was $305,000 in August 2026 across 42 closed sales. Over the last twelve months 625 homes sold at a median of $315,990, down 0.5% against the twelve months before. The median asking price across 246 active listings is $329,999, or $189 per square foot.

Is Tavares cheaper than Leesburg?

On the asking median, no: $329,999 against $289,900. Measured against household income, Tavares is at 5.72 times income and Leesburg at 6.10, so on that basis Tavares is the more affordable of the two. See what $350,000 buys in each town.

Is Tavares, FL safe?

The reported violent crime rate runs about 76% below the Florida average, though city rates are measured against resident population while the offense count includes everyone passing through.

What is the cost of living in Tavares, FL?

Housing is the deciding line. A median asking price of $329,999 against a median household income of $57,644 puts a home at roughly 5.72 times income, and Florida charges no state income tax, which shifts weight onto the property tax line.

What school district serves Tavares, FL?

Lake County Schools. Assignment varies by address within the city, so confirm the zoning for the specific property.

Thinking About a Move to Tavares?

I work these four counties every week and I will tell you when a town is wrong for you. If you want the numbers for your budget before you tour anything, start with what $350,000 buys across Tavares and its neighbors, or call me at 407-616-9019.

You can also browse homes for sale in Tavares, which updates with current inventory.
Oct. 7, 2026

750 Central Florida homes have been for sale more than a year. Here is where they are and how far their sellers have moved

By Brenden Rendo, Realtor · Updated October 7, 2026

Most buyers scroll right past a listing once it has been up for a year. They figure something must be wrong with it, or that the seller will never budge. In Central Florida right now that habit skips 750 homes, and the numbers say the sellers behind them have already moved further than anyone else on the market. I pulled every active listing in Orange, Seminole, Lake, and Volusia counties that had been available 365 days or more as of October 6, 2026, counted by its true time on the market including relists, and broke the list apart by county, property type, and price.

750
Active Listings Past One Year
Orange, Seminole, Lake, Volusia. 5.55% of 13,512 active listings, about 1 in 18. Stellar MLS, October 6, 2026
78.10%
Already Below Original Asking Price
585 of the 749 with a usable original price
9.64%
Median Asking-Price Cut, Reduced Listings Only
Counting the 164 that never cut, the median across all is 7.14%
482
Median Days on Market
73 of the 750 have been available two years or more
TLDR:
  • 750 active listings across Orange, Seminole, Lake, and Volusia had been on the market 365+ days as of October 6, 2026: Orange 349, Seminole 61, Lake 158, Volusia 182. That is 5.55% of all active listings.
  • 78.10% have cut their asking price, at a median cut of 9.64%. Listings at 90 to 179 days have cut a median 5.23%.
  • The longer a listing sits, the deeper the typical cut: 6.90% at 180 to 364 days, 9.23% at one to two years, 15.15% past two years.
  • Houses are 386 of the 750, condos, townhomes and villas 277, and condo-hotels, manufactured homes and other types 87. That last group has the deepest median cut, 13.53%.
  • These are asking-price reductions on homes that have not sold. They are not sale prices.

1. Where the 750 Sit, County by County

Orange holds the most year-plus listings because it is the biggest market. The better lens is the share of each county's active inventory, and on that measure Volusia and Orange lead at 6.08% and 6.05%, while Seminole sits well below the rest at 3.62%.

CountyListings past 1 yearShare of all activesShare reducedMedian cut (reduced only)Median days on marketPast 2 yearsFull list
Orange3496.05%76.72%10.00%48037See the map
Seminole613.62%75.41%9.37%4684See the map
Lake1585.16%73.42%8.74%4789See the map
Volusia1826.08%85.71%9.93%503.523See the map
4-county total7505.55%78.10%9.64%48273

Source: Stellar MLS active residential listings with 365+ days on market, pulled October 6, 2026. Share of all actives divides by a same-day Stellar count of 13,512 active residential listings (Orange 5,769, Seminole 1,685, Lake 3,064, Volusia 2,994) taken later that day, so treat that column as approximate.

Volusia sellers have moved the most. 85.71% of Volusia's year-plus listings are below their original price, the highest share of the four, with a median cut of 9.93% among them.

Lake sellers have moved the least. Only 73.42% have cut, and 13 Lake listings are asking more today than when they first listed.

The list turns over. On September 29 the same count was 764. In the week since, 68 of those listings left the active market and 54 new ones crossed the one-year mark, for a net of 750. Orange lost 30 and gained 30, so its count of 349 did not move at all. "Left" means sold, went under contract, was withdrawn, or expired; this data does not say which. One week is not a trend, and these are the only two weekly pulls on this exact measure so far. Earlier pulls used a narrower days-on-market count that missed relists, so they are not comparable.

For scale, Realtor.com data published through FRED at the Federal Reserve Bank of St. Louis puts the median active listing at 77 days on market in the Orlando-Kissimmee-Sanford metro in September 2026, against 81 for Florida and 61 nationally. That metro includes Osceola and leaves out Volusia, and it measures the typical listing. The 750 here are the long tail, with a median of 482 days.

How I counted: Days on market is the larger of Stellar's cumulative days on market, which carries a home's earlier listings when it is withdrawn and relisted, and the days since the current listing went live. A home relisted last month after two years on and off the market counts as two years here, not one month. "Reduced" means the current asking price is below the original list price. One Orange listing carries an obvious typo in its original price ($13,000,000 on a $1,250,000 house); it is counted but left out of every price-cut figure, so those figures use 749 listings. Listings whose sellers opted out of internet display are not included.

2. The Longer It Sits, the Deeper the Cut

Here is the pattern that makes this list worth a buyer's time. Line up every active listing past 90 days by how long it has been on the market, and the typical price cut gets deeper at every step.

Days on marketActive listingsShare reducedMedian cut (reduced only)Median cut (all)Median asking price
90 to 179 days3,44972.19%5.23%3.48%$405,000
180 to 364 days2,09372.38%6.90%4.63%$390,000
365 to 729 days67777.37%9.23%6.62%$365,900
730 days or more7384.93%15.15%12.06%$299,000

Source: Stellar MLS, all 6,292 active residential listings past 90 days in the four counties, October 6, 2026.

A seller at four months has cut a median 5.23%. A seller still on the market past two years has cut a median 15.15%, roughly three times as far. The share who have cut at all climbs too, from 72.19% to 84.93%.

Two cautions. This compares different homes on the same day, not one home over time, and the sellers who cut early and sold are no longer in it. And not everyone on the year-plus list has moved: 131 are still at their original price and 33 are asking more than they started at. The list is full of motivated sellers. It is not only motivated sellers.

3. Houses: 386 Listings

386 of the 750 are single-family houses, at a median asking price of $499,990. 77.66% have cut, at a median of 8.93% among those that did.

CountyListings past 1 yearMedian asking priceShare reducedMedian cut (reduced only)Median days on market
Orange141$650,00077.86%9.21%466
Seminole30$484,50070.00%6.23%470
Lake118$443,50075.42%8.36%466.5
Volusia97$450,00082.47%10.39%497
Current asking priceListings past 1 yearShare reducedMedian cut (reduced only)Median cut (all)Median days on market
Under $300,0005782.46%14.71%11.56%495
$300,000 to $499,99913775.91%8.44%6.04%452
$500,000 to $749,9996680.30%5.33%4.55%470.5
$750,000 to $999,9994182.93%9.21%6.22%462
$1,000,000 and up8572.62%9.38%7.01%499

Source: Stellar MLS, single-family residence listings past 365 days, October 6, 2026. One $1,000,000+ house is left out of the cut columns for the price typo noted above.

Luxury sellers hold out. 85 of the 386 year-plus houses, 22.02%, are asking $1,000,000 or more, and that band has the lowest share of sellers who have cut, 72.62%.

The bottom of the range cuts deepest. The 57 houses under $300,000 carry a median cut of 14.71% among reduced listings. That band includes homes sold as-is that need a full rehab, three of which appear in the standouts below.

4. Condos, Townhomes and Villas: 277 Listings

Condos are a different decision from a house, so they get their own count. 277 year-plus listings are attached homes: 238 condominiums, 34 townhouses, and 5 villas and half-duplexes. The median asking price is $235,000, and 79.42% have cut.

CountyListings past 1 yearMedian asking priceShare reducedMedian cut (reduced only)Median days on market
Orange161$199,90077.02%9.76%482
Seminole29$189,78679.31%10.00%453
Lake12$315,00050.00%12.87%517
Volusia75$410,00089.33%9.28%518

185 of them, two out of three, are asking under $300,000, at a median cut of 10.40% among reduced listings. Volusia's year-plus condos are a different animal: a median asking price of $410,000, and 89.33% of those sellers have already cut.

Quick Tip: On any condo that has been sitting, ask for the association's budget, its reserve study, any special assessments in the last two years, and any milestone inspection report before you write an offer. A long-listed condo is sometimes priced fine and stuck on the building, not the unit.

5. Condo-Hotels, Manufactured Homes and Other Types: 87 Listings

The smallest group cuts the deepest. 87 year-plus listings are 48 condo-hotel units, 27 manufactured homes, 9 mobile homes, 2 modular homes, and 1 farm. Their median asking price is $204,900, the median time on market is 507 days, and the median cut among reduced listings is 13.53%, the deepest of the three groups.

Part of the reason is who can buy them. Condo-hotel units are generally not eligible for conventional loans sold to Fannie Mae, and some manufactured homes face narrower loan options, so a smaller pool of buyers, many paying cash, sets the price. If you are looking in this group, settle how you will pay for it before you fall for one.

6. All 750 by Price Band

All 750 together, by current asking price:

Current asking priceListings past 1 yearShare reducedMedian cut (reduced only)Median cut (all)Median days on market
Under $300,00031179.42%11.56%9.30%491
$300,000 to $499,99920375.86%8.29%5.34%461
$500,000 to $749,9999681.25%6.49%4.94%480.5
$750,000 to $999,9994885.42%9.18%6.87%472
$1,000,000 and up9271.43%9.81%6.88%512
All bands75078.10%9.64%7.14%482

Source: Stellar MLS active residential listings past 365 days, October 6, 2026. The $1,000,000+ cut columns use 91 of 92 listings.

311 of the 750, 41.47%, are asking under $300,000, and only 57 of those are houses. The $500,000 to $749,999 band has the shallowest median cut at 6.49%. The $1,000,000+ band has the lowest share of sellers who have cut, 71.43%, and the longest median time on market, 512 days.

7. 12 Standout Houses, Three per County

Three houses per county: the biggest cut from original price, the lowest asking price, and the longest time on the market. I left out short sales, bank-owned homes, auctions, and anything marketed as land, a development site, multiple units, or commercial property, and re-checked every one against Stellar MLS on October 6, 2026. These are examples of what is on the list, not recommendations, and any of them can go under contract tomorrow. Each address links to its full listing.

Orange County

HomeAsking priceDays on marketWhy it stands out
Biggest cut from original
808 Edgewater Drive, Orlando
3 bed, 2,413 sq ft, built 1918. MLS O6332752
Listing courtesy of Amanda Brown, THE HIGH TIDE GROUP
$999,999
from $1,600,000, down 37.50%
439Lakefront on Lake Concord, built 1918 and renovated per the listing, which also notes it is back on the market.
Lowest asking price
4022 Shellman Street, Orlando
2 bed, 1,500 sq ft, built 1958. MLS O6127683
Listing courtesy of Adriana Montes, FLORIDA DREAMS REALTY GRP INC
$149,999
from $199,999, down 25.00%
1,168Sold as-is. The listing describes it as a shell that needs significant work.
Longest on the market
2627 Ambergate Road, Winter Park
4 bed, 1,745 sq ft, built 1959. MLS O6433352
Listing courtesy of Steven Thetford, KELLER WILLIAMS WINTER PARK
$575,000
unchanged from this listing's original price
1,258A relist. This listing went live 54 days ago, but the home's cumulative time on the market goes back to March 2023.

See every Orange County listing past 90 days on the Orange County 90+ days map, or the newest cuts on Orange County price-reduced homes.

Seminole County

HomeAsking priceDays on marketWhy it stands out
Biggest cut from original
808 Sweetwater Club Boulevard, Longwood
7 bed, 14,801 sq ft, built 1977. MLS O6339805
Listing courtesy of Christopher Christensen, ONE LUXURY INTERNATIONAL LLC
$3,499,000
from $4,695,000, down 25.47%
375Gated Sweetwater Club estate on 3.12 acres, remodeled per the listing.
Lowest asking price
2075 Dixie Avenue, Sanford
3 bed, 896 sq ft, built 1985. MLS O6323429
Listing courtesy of Scott Banta, BLACKFIN REALTY LLC
$246,750
from $226,750, up 8.82%
788Asking $20,000 more than it started at. Remodeled per the listing, with a new roof and A/C.
Longest on the market
1469 Grace Lake Circle, Longwood
4 bed, 2,174 sq ft, built 1982. MLS O6355680
Listing courtesy of Alvin Moore, MOREHOUSE REALTY INC
$535,000
from $560,000, down 4.46%
693Pool home. The current listing is 344 days old; the rest of its time on market is earlier listings.

See every Seminole County listing past 90 days on the Seminole County 90+ days map, or the newest cuts on Seminole County price-reduced homes.

Lake County

HomeAsking priceDays on marketWhy it stands out
Biggest cut from original
611 Old Eustis Road, Mount Dora
3 bed, 1,792 sq ft, built 1987. MLS P4936416
Listing courtesy of John Constant, CENTURY 21 MYERS REALTY
$536,400
from $747,400, down 28.23%
376Pool home on 0.6 acres near Lake Gertrude, with solar panels the listing says are paid off.
Lowest asking price
1605 Rose Lane, Eustis
2 bed, 720 sq ft, built 1963. MLS G5083721
Listing courtesy of Laurie Laventhall, FLORIDA REALTY INVESTMENTS
$64,900
from $89,900, down 27.81%
837Needs a total rehab per the listing. Not a move-in home.
Longest on the market
1241 W Lakeshore Drive, Clermont
2 bed, 3,116 sq ft, built 1948. MLS G5075759
Listing courtesy of Mendy Bacon, BONJORN REAL ESTATE
$1,149,000
from $1,399,000, down 17.87%
1,048Converted from four bedrooms to two by the owner, per the listing.

See every Lake County listing past 90 days on the Lake County 90+ days map, or the newest cuts on Lake County price-reduced homes.

Volusia County

HomeAsking priceDays on marketWhy it stands out
Biggest cut from original
724 N Oleander Avenue, Daytona Beach
6 bed, 4,105 sq ft, built 1926. MLS V4937615
Listing courtesy of Doris Yount, DINARDO PROPERTY MANAGEMENT
$475,000
from $799,000, down 40.55%
797Main house plus a two-bedroom in-law suite in the Seabreeze area, built 1926. The listing pitches it as a restoration project.
Lowest asking price
921 S Salisbury Avenue, DeLand
3 bed, 934 sq ft, built 1957. MLS V4950749
Listing courtesy of Jennifer Clark, GLORY INTL. REAL ESTATE CO
$58,500
from $69,900, down 16.31%
416Concrete block, interior taken down to the framing per the listing. A relist: the current listing is 52 days old.
Longest on the market
910 Lake Avenue, Edgewater
4 bed, 1,480 sq ft, built 1956. MLS O6081908
Listing courtesy of Paula Kegelman, COLLADO REAL ESTATE
$299,000
from $365,000, down 18.08%
1,368Lakefront, renovated per the listing.

See every Volusia County listing past 90 days on the Volusia County 90+ days map, or the newest cuts on Volusia County price-reduced homes.

8. What Buyers, Sellers, and Investors Should Do With This

Buyers. A year-plus listing is where your offer gets read instead of ignored. The typical seller at this stage is already 9.64% below where they started and has carried the house for more than a year. Before you offer, get the full listing history, every prior listing and price change and not just the current one, and find out why it has been sitting: price, condition, the association, or the financing on that property type. Then offer on what it is worth, not on what it is listed at.

Sellers. This is the cost of starting too high, in plain numbers. The sellers still here after a year have given up a median 9.64% and still have not sold. Sellers at four months had given up 5.23%. The first weeks on the market get the most attention a listing will ever have, and every one of these sellers spent them at a price buyers passed on. If you are thinking about selling, start with a number the market supports. Get a home value estimate, then let me check it against what is actually closing near you.

Investors. The deepest cuts are at the bottom: 311 listings under $300,000 at a median cut of 11.56% among reduced listings. Some of these are shells and full rehabs. Run your numbers on after-repair value and holding costs, never on the asking price, and assume a home that has sat for a year has a reason you will find in the inspection.

For the broader monthly picture across all four counties, see our Central Florida housing market hub.

9. Frequently Asked Questions

How many homes have been on the market over a year in Central Florida?

As of October 6, 2026, Stellar MLS showed 750 active listings on the market 365 days or more across Orange, Seminole, Lake, and Volusia counties: 349 in Orange, 61 in Seminole, 158 in Lake, and 182 in Volusia. That is 5.55% of the 13,512 active residential listings in the four counties, about 1 in 18.

Have the sellers of year-old listings cut their price?

Most have. 585 of the 749 listings with a usable original price, 78.10%, are asking less than they started at, and the median cut among them is 9.64%. Another 131 are still at their original price and 33 are asking more than they started at.

Do listings that sit longer cut their price deeper?

In the October 6, 2026 snapshot, yes. The median cut among reduced listings is 5.23% at 90 to 179 days, 6.90% at 180 to 364 days, 9.23% at one to two years, and 15.15% past two years. That compares different homes on one date, not one home over time.

How is days on market counted in this report?

Days on market is the larger of Stellar MLS cumulative days on market, which carries a home's earlier listings when it is withdrawn and relisted, and the days since the current listing went live. A home relisted last month after two years on and off the market counts as two years, not one month.

Does a listing past a year mean something is wrong with the house?

Usually it means the price started ahead of the market, which is why most of these sellers have already reduced. It can also point to condition, an association issue, a financing limit on the property type, or a seller who is not motivated. Treat it as a reason to ask questions and inspect, not as a verdict on the house.

Found a home that has been sitting?

I will pull its full listing history, every prior listing and price change, plus the recent closed sales around it, before you write an offer. Call or text Brenden at 407-616-9019.

Contact The Homes In Orlando Team

Oct. 7, 2026

Living in Eustis, FL: Who It Fits, and Who Should Look Elsewhere

Eustis is an old lakefront town with a new town being built around it. More than a quarter of the homes that sold here in the last twelve months were brand new, in subdivisions on the edges of town, while the original streets near Lake Eustis are 1950s houses that close around $275,000. The fact a buyer needs first is that new construction here sells for less per square foot than resale, which means the builders are setting the price.

$358,000
Median Sale Price
August 2026, 51 closed sales
23,567
Population
U.S. Census ACS 2023, up 13.9% since 2019
195
Active Listings
Active residential listings in the city, October 9, 2026
26.8 min
Mean Commute
Against 28.8 minutes from Mount Dora

Who Eustis Fits, and Who It Doesn't

Strong fit: buyers who want a new single-family house under $350,000, because the Pine Meadows sections closed 38 at about $325,000 and Hidden Cove 28 at $348,340; buyers who like Mount Dora and not its price, since Eustis sits on the same chain of lakes, has its own waterfront downtown, and sells a new house for far less than Mount Dora does; anyone who wants acreage, because 113 homes on an acre or more closed at a median of $570,000, a fifth of the whole market; and buyers who want an older house with no association, with 258 no-HOA sales at $295,000.

Weaker fit: anyone expecting the new subdivisions to hold a premium, because new construction closed at $178 per square foot against $196 for resale, and the buyer of a two-year-old house is competing with the builder next door; buyers who need to sell quickly on the water or on land, since waterfront took a median of 96 days to go under contract and acre-plus 61; daily commuters to Orlando, because the trip is long and the parkway connection is on the Mount Dora side; and anyone who wants the busiest downtown of the three, which is Mount Dora.

Still deciding between towns? We pulled the closed sales around a $350,000 budget and put Eustis side by side with its neighbors: what $350,000 actually buys in each. Square footage, bedrooms, year built, and how many came with a pool.

Where Is Eustis, and What Makes It Different?

Eustis sits on the east shore of Lake Eustis in north-central Lake County. US-441 ties it to Mount Dora and Tavares, the three towns locals call the Golden Triangle, and State Road 19 runs north toward the Ocala National Forest. The downtown faces the lake. The mean commute is 26.8 minutes, shorter than Mount Dora and about the same as Tavares.

Eustis Housing Market Snapshot (2026)

Over the last twelve months 567 homes sold in Eustis at a median of $339,900, up 1.6% against the twelve months before. Per square foot, which strips out any change in the size of what sold, the figure fell 8.7%. In August 2026, 51 homes closed at a median of $358,000 and the typical one went under contract in 45 days. One month is too small a sample to read a direction from, which is why the twelve-month figure leads here. There are 195 active residential listings as of October 9, 2026, with a median asking price of $370,000, or $193 per square foot.

Wondering whether it is a buyer's or seller's market around Eustis? We publish that answer for Lake County as a whole, from current MLS data: Is Lake County a buyer's or seller's market?

New Construction and Resale Are Not the Same Market

Every price figure quoted for Eustis mixes brand new homes with existing ones. Split apart, the last twelve months looked like this.

What soldMedian, prior 12 monthsMedian, last 12 monthsChangeSales
New construction$379,990$346,990-8.7%153
Existing homes (resale)$324,499$329,450+1.5%414
All sales combined$334,490$339,900+1.6%567

Read the resale row carefully. Its direction comes from the size of the homes that sold, not from prices. The median resale home sold in Eustis went from 1,573 square feet to 1,766, 12.3% larger, while the price per square foot moved -6.2%. The median rose because larger homes sold, while the price per square foot went the other way. The price per square foot is the honest comparison here and the median is not.

Measured per square foot, which is the comparison that holds here, new construction moved -14.4% and resale -6.2%.

Best Neighborhoods in Eustis, FL: Communities to Know

Eustis is four different purchases, and they are spread from the lake outward.

  • The old town and the lakefront, the original plat near downtown and Lake Eustis, mostly 1950s houses: the Eustis plat closed 14 at $275,000 in three weeks, and the 135 homes built before 1980 closed at $260,000 citywide; the 49 waterfront sales closed at a median of $540,000 and took about three months to go under contract
  • The new subdivisions, Pine Meadows, Hidden Cove and the Connors Cove townhomes: the Pine Meadows sections closed 38 at about $325,000 in about a month, Hidden Cove 28 at $348,340, and Connors Cove 12 townhomes at $269,152; Pine Meadows Reserve, at the top of the range near $378,000, took more than four months
  • The acreage, homes on an acre or more: 113 closings at $570,000, with Royal Trails, well northeast of town, at 44 closings and $500,000, most of them new builds
  • The 2000s subdivisions and the manufactured-home parks, the 2000 to 2019 neighborhoods closed 115 at $435,000 on about 2,300 square feet, with the Black Bear communities at $416,000 to $498,000; at the other end, Eustis Country Club Manor's age-restricted manufactured homes closed 14 at $111,500

Decide whether you are buying the lake town or the new subdivision. They share a zip code and almost nothing else, and the resale risk sits with whichever one the builders are still adding to.

The 15 communities in Eustis where the most homes have sold over the last twelve months, each with its own page:

Another 90 Eustis communities have their own page too. You can also browse every Eustis listing in one place.

Eustis vs. Mount Dora vs. Tavares: The Honest Comparison

 EustisMount DoraTavares
Median asking price$370,000$468,950$329,999
Median $/sq ft$193$227$189
Mean commute26.8 minutes28.8 minutes26.0 minutes
Median household income$62,475$69,931$57,644
Population23,56716,81219,738

Mount Dora is the town people came to the area for, with the higher price, the larger downtown and the parkway connection. Tavares is the county seat next door, with a third of its market age-restricted, far more manufactured homes and slower sales. Eustis is the one of the three where a new house costs the least and the old lakefront core still sells under $300,000.

Schools, Commute, and Day-to-Day Life

Lake County Schools serves the city, and assignment varies by address rather than by city name, so confirm the zoning for the specific property before you buy on a school reputation.

Mean travel time to work is 26.8 minutes, against 28.8 from Mount Dora.

How Much of Eustis Is New Construction?

Eustis has no municipal police agency reporting usable figures to the FBI, so there is no honest city-level crime comparison to publish here, and a number that cannot be sourced is worse than none. What can be measured is the age and type of what is for sale, which is the other question relocation buyers ask.

Across 195 active residential listings, the median asking price is $370,000, or $193 per square foot. Where a town is still building, the per square foot figure runs closer to replacement cost; where it is built out, it reflects land and location instead.

Cost of Living in Eustis, FL

Housing is the line that moves a Central Florida budget. Eustis' median asking price is $370,000 against a median household income of $62,475, which puts a home at about 5.92 times household income here. That ratio, rather than the sticker price, is the number worth carrying between towns, and it is why a cheaper town is not automatically a more affordable one.

Florida charges no state income tax, so the property tax line matters more here than it would elsewhere, and a homestead exemption reduces the taxable value of a primary residence. Millage varies by taxing district, so treat any single quoted rate as an estimate until the specific parcel is checked.

Frequently Asked Questions

Is Eustis, FL a good place to live?

It depends on whether your income comes with you. Against the 60 places this site tracks across Orange, Seminole, Lake and Volusia counties, the median asking price of $370,000 is lower than most and the mean commute of 26.8 minutes is shorter than most. The median household income here is $62,475, which puts housing at 5.92 times income, a heavier load than in most of those places. For remote workers and retirees who bring their income with them, that matters less. For someone earning a local wage, it is tighter than the sticker price suggests. Who it fits, and who it does not, is laid out at the top of this page.

What is the median home price in Eustis, FL?

The median sale price was $358,000 in August 2026 across 51 closed sales. Over the last twelve months 567 homes sold at a median of $339,900, up 1.6% against the twelve months before. The median asking price across 195 active listings is $370,000, or $193 per square foot.

Is Eustis cheaper than Mount Dora?

On the asking median, yes: $370,000 against $468,950. Measured against household income, Eustis is at 5.92 times income and Mount Dora at 6.71, so on that basis Eustis is the more affordable of the two. See what $350,000 buys in each town.

What is the cost of living in Eustis, FL?

Housing is the deciding line. A median asking price of $370,000 against a median household income of $62,475 puts a home at roughly 5.92 times income, and Florida charges no state income tax, which shifts weight onto the property tax line.

What school district serves Eustis, FL?

Lake County Schools. Assignment varies by address within the city, so confirm the zoning for the specific property.

Thinking About a Move to Eustis?

I work these four counties every week and I will tell you when a town is wrong for you. If you want the numbers for your budget before you tour anything, start with what $350,000 buys across Eustis and its neighbors, or call me at 407-616-9019.

You can also browse homes for sale in Eustis, which updates with current inventory.
Oct. 6, 2026

The Lock-In Effect Is Back: Why Your Neighbors Are Renovating Instead of Selling

By Brenden Rendo, Realtor · Updated October 6, 2026

In January I told you the handcuffs were slowly loosening. The share of mortgages above 6% had just passed the share below 3%, and an owner with a 4.8% rate was no longer stuck on the rate, only on the total payment. Nine months later the 30-year fixed rate is 7.28%, the highest it has been all year, and the move I would have priced for a typical Orange County family in January now costs them about $278 more every month than it did then. So the kitchen is getting redone, the roof is getting replaced, the lanai is getting screened, and the house is not getting listed. Here is what people are saying about being locked in, what the Central Florida numbers actually show, and the math I would run before deciding whether your house is the one you renovate or the one you sell.

49.1%
Of US Mortgages Under 4%
FHFA National Mortgage Database, second quarter of 2026. Down from a 65.2% peak in early 2022.
7.28%
30-Year Fixed, Market Rate
Freddie Mac PMMS, October 1, 2026. The 2026 high, up from 6.06% in mid-January.
19.1%
Fewer Four-County Closings Than 2018-19
38,025 closed sales from October 2025 to September 2026, against 47,003 from October 2018 to September 2019. Stellar MLS.
$1,088
Added Monthly Cost of a Typical Move-Up
My estimate: a $300,000 loan at 3.00% traded for a $343,920 loan at 7.28%, principal and interest only. It was $810 at January's rate.
TLDR:
  • In January I wrote that lock-in was breaking. Since then the 30-year rate climbed from 6.06% to 7.28% (Freddie Mac, October 1), and the same move-up now costs about $1,088 a month more instead of $810, my estimate.
  • Nationally, 49.1% of outstanding mortgages are under 4% (FHFA, second quarter of 2026). Fed Governor Michael Barr said on September 23 that lock-in "reduces both demand and supply and thus housing market dynamism."
  • Locally it shows up in turnover: 38,025 closings across Orange, Seminole, Lake, and Volusia in the last 12 months, 19.1% fewer than in 2018-19. Counting resale homes only, closings fell 33.8% in Seminole, 32.1% in Orange, and 12.8% in Lake, where builders doubled their sales and kept the county total up 3.5%.
  • That is not a frozen market: 13,524 active listings, 1,396 price cuts in seven days, and 54.5% of actives priced below their original list (Stellar MLS, October 1).
  • The MOVE Act is still a bill that has not moved past introduction. Florida's Save Our Homes portability is law today and carries up to $500,000 of your assessment difference to a new homestead, which softens the reset but does not erase it.

1. I Said the Handcuffs Were Loosening. Here Is What Changed

In my January 15 market update I argued the lock-in effect was finally breaking. The reason was real: for the first time, more mortgages carried rates above 6% than below 3%. Someone sitting on a 4.8% loan was no longer paralyzed by the rate itself, only by the payment shock of the total package.

That trend has kept going, slowly. Per FHFA National Mortgage Database figures for the second quarter of 2026, as charted by CalculatedRisk on October 1, the share of outstanding loans under 4% has fallen to 49.1% from a 65.2% peak in early 2022, and the share above 6% has climbed to 22.5% from a low of 7.3%. Every year, more owners refinance, move, or pay off, and the low-rate pool shrinks.

What I did not expect was how fast the other side of the gap would move. Freddie Mac had the 30-year fixed at 6.06% the week of my January post. It bottomed at 5.98% in late February, then climbed through the summer to 7.28% on October 1, the highest reading of 2026. For the half of the country still holding a loan under 4%, the penalty for moving got bigger, not smaller. Time is eroding lock-in. Rates just outran it.

2. What People Are Saying About Being Locked In

I read a month of the conversation, September 2 through October 2, across Reddit, YouTube, TikTok, and X. Two years ago the complaint was rates. Now it is a standoff, and people are naming who is stuck in it.

The clearest version is one family's decision, out loud. On September 29 a Redditor in r/RealEstate, u/NonVeganRibeye, laid it out: a first home bought in 2018, refinanced around 3% during COVID, two kids, a home office split with a crib, and a plan to move out of state for more room. On rates: "I think 6% is reasonable combined with current pricing but as we push closer to 8, that scares me." It is a national forum and the poster never says where they live, but the thread is the renovate-or-sell debate in miniature. Asked about building on, OP answered: "Addition isn't viable unfortunately." Others kept looking for a way to stay: "Could you remodel a basement or garage?" asked u/Any-Alternative2667, and u/FormerUsenetUser asked, "Can you close in a porch and use that as your home office?"

The rate is treated as an asset. u/sweetrobna ran the numbers and concluded "you are saving hundreds in interest every month you stay," then added the line that decides most of these: "If you need more space, you need more space." And u/Gollum69, half of a couple in their 70s with a 2.5% loan on a 1,400 square foot townhouse, put it bluntly: "you'll have to pry it outta our cold dead hands."

Video has made it a genre. Bloomberg Opinion captioned a September 30 TikTok featuring Justin Fox with "Millions of homeowners are locked in to 3% or 4%," and the clip walks through how that thins out the homes for sale. A September 29 YouTube video from Jackie Baker went further: "Your 3% mortgage rate is crippling the housing market." The shortest version came from @ratioledger on October 1: "Below 3% locked in. At 7% today, that's $1,000+/month more. So nobody moves." And the lending side is selling the escape hatch, with one September 28 clip pitching it as "Don't refinance and lose your low rate. Use a HELOC instead."

The Fed sees the same thing. In a September 23 speech on housing, Federal Reserve Governor Michael Barr said about half of all mortgages still carry rates of 4% or lower and nearly 80% are below 6%, and that lock-in "reduces both demand and supply and thus housing market dynamism."

Most of that is nationally accurate. The question for anyone reading this from Lake Mary or DeLand is how it plays out here, and the answer is more uneven than the headlines.

3. The Math That Keeps Your Neighbor Home

Take a family that bought in east Orange County in 2021 with a $300,000 loan at 3.00%. Their principal and interest payment is about $1,265 a month. Now move them to a similar house at the Orange County median asking price of $429,900 (active listings, Stellar MLS, October 1, 2026). With 20% down, the new loan is $343,920. At 7.28%, the payment is about $2,353. These are my estimates, principal and interest only, before taxes and insurance.

That is about $1,088 more every month, an 86% jump, to live in a comparable house. At January's 6.06% the same move cost about $810 more. Run it the other way and it gets starker: at 7.28%, their current $1,265 payment finances a loan of only about $185,000. The rate gap removes roughly 38% of their buying power the moment they hand back the old mortgage.

And that is before the part my January post focused on. Taxes and insurance get repriced on the new house too, which is why owners with 4% and 5% loans still feel stuck: it is the total payment, not the rate, that moves. Against all of that, a $75,000 kitchen and primary bath remodel looks like the conservative choice even at today's borrowing costs. The lock-in effect is not sentimental attachment to a house. It is a correct reading of an amortization table, and any advice that ignores the table will lose to it.

4. What Lock-In Looks Like in Central Florida's Numbers

Lock-in describes seller behavior. The place it should show up is turnover: fewer owners selling means fewer closings. So I pulled every residential closing in the four counties for the last 12 months and for the same 12 months before the pandemic, October 2018 through September 2019, when the 30-year rate averaged 4.21% (Freddie Mac).

County Closings, Oct 2018 to Sep 2019 Closings, Oct 2025 to Sep 2026 Change New construction share of last 12 months' closings
Seminole8,4435,628-33.3%7.3%
Orange22,43516,072-28.4%15.0%
Volusia8,0928,011-1.0%13.5%
Lake8,0338,314+3.5%27.4%
Four counties47,00338,025-19.1%16.2%

Take the builders out and resale carries the drop everywhere I can measure. Seminole, where only 7.3% of the last year's sales were new construction, closed a third fewer homes than in 2018-19, and Orange is down 28.4%. Lake closed more homes than before the pandemic, but that is the builders. Counting resale homes only, the sales existing owners control, Seminole fell 33.8% (7,883 to 5,219), Orange 32.1% (20,106 to 13,657), and Lake 12.8% (6,926 to 6,039). Lake's total rose only because new construction closings more than doubled, from 1,104 to 2,275, and builders have no 3% mortgage to protect. Volusia I cannot split cleanly: about a quarter of its 2018-19 closings carry no new construction flag, and coastal Volusia runs its own MLS that this feed does not see. Its total is nearly flat, and I am showing that row rather than hiding it, because one tidy explanation rarely covers four different markets.

Against the nation, the four-county total has held up better, but not every county has. The NAR existing-home sales report for August 2026, released September 10, put national sales at a 3.98 million annual pace, down 2.0% from July and about 25% below the 5.34 million homes NAR counted for 2019. The four counties together are 19.1% below their pre-pandemic year on a trailing 12-month basis, but Lake and Volusia carry that total: Seminole (-33.3%) and Orange (-28.4%) fell further than the nation. The windows differ, one month at an annual rate against a full year, but the scale is comparable.

And the last year has been flat, not frozen. Compared with the 12 months before it, four-county closings rose 2.3%, from 37,172 to 38,025, led by Lake (+7.7%) and Volusia (+3.2%), while Orange was flat (+0.7%) and Seminole fell 1.7%. New listings slipped 2.8%, from 55,392 to 53,864. Statewide, Florida Realtors reported 21,497 closings of existing single-family homes in August 2026, down 1.4% from a year earlier after 11 straight months of year-over-year gains, with condo and townhouse sales down 1.8%. The four counties' August closings, all residential types, were 3,288 against 3,298 a year earlier, down 0.3%. One month is not a trend, but on the same month the four counties and the state are moving together. Lock-in set a lower floor for turnover years ago. It has not pushed it meaningfully lower this year, at least not yet; September's rate climb has not had time to show up in a full year of closings.

What is for sale right now. As of the October 1, 2026 Stellar MLS snapshot there are 13,524 active listings across the four counties. In the prior seven days, 881 new listings came on and 1,396 sellers cut their price. 7,366 of those actives, 54.5%, are priced below their original list, and 8,152, or 60.3%, have been on the market 60 days or more. Median asking prices: Orange $429,900, Seminole $389,900, Lake $389,900, Volusia $368,900. Those are asking prices on unsold homes, not what buyers paid.

My read, from the listings and sellers I work with every week: the discretionary move-up seller, the one with the 3% rate and the renovated kitchen, is the one I see least. More of what comes to market is builders, relocations, estates, investors repositioning, and owners whose insurance, HOA, or life circumstances made the decision for them. That would explain plenty of inventory and soft pricing alongside a thin supply of updated, well-located resale homes.

How I counted: Closings are every Residential record in Stellar MLS (via the Bridge RESO API) with status Closed and a close date in the window, Orange, Seminole, Lake, and Volusia only. New listings are Residential listings whose on-market date falls in the window, whatever their status now. The 2018-19 comparison uses closings only, because the feed does not carry on-market dates for listings that old. New construction and resale are split on the listing's new construction flag; about a quarter of Volusia's 2018-19 closings leave that flag blank, so Volusia is left out of the resale comparison. September 2026 closings can still tick up as late entries post. Active-listing counts include only listings cleared for internet display, and median asking prices include condos and townhomes as well as houses. Coastal Volusia also has its own MLS through the Daytona Beach Area Association of Realtors, which this feed does not see, so Volusia figures undercount that county. Days on market is the larger of cumulative days on market and days since the on-market date, a measurement I adopted September 27, so the 60-day share above should not be compared with figures I published before then.

5. The MOVE Act Is Still a Bill. Florida's Portability Is Already Law

The portable mortgage idea keeps resurfacing, and it traces to a real bill: H.R. 10028, the MOVE Act, introduced in the House on August 3, 2026. It would require Fannie Mae and Freddie Mac to purchase portable mortgages, so an eligible owner could carry their rate, balance, and remaining term to a new home. As of October 1, the bill has not moved past introduction. Even a passed version would need rulemaking, lender adoption, and an answer to what happens when the new home costs more than the old balance. Watch it, but do not put a 2026 decision on hold for it.

Florida already has a portability program, and it is law today: Save Our Homes portability. If you have a homestead exemption, the Seminole County Property Appraiser and Orange County's appraiser both explain that you can transfer up to $500,000 of the gap between your home's market value and its capped assessed value to a new Florida homestead. Per the Florida Department of Revenue, you must establish the new homestead within three years of January 1 of the year you left the old one, not three years after the sale.

Here is how that squares with my January warning that a move-up can double or triple a tax bill even with portability. Both are true. Portability carries the savings you built, but the new home's higher value still gets taxed, so the bill resets upward on the difference. It softens the reset. It does not erase it. For a long-tenured owner in Winter Park or Altamonte Springs whose assessed value sits far below market, it is real money the renovate-or-sell math should include, and your county property appraiser will estimate it for free.

6. Renovate or Sell: How I Would Actually Decide

I have worked this decision from the lending side, the hard money side, the flipping side, and the listing side. The right answer is different depending on which of these you are.

If you are staying put and renovating: keep the rate, but underwrite the project like a lender would. Pull the permits, because unpermitted work surfaces at the worst time, during your eventual sale or your next insurance renewal. On older homes, Florida carriers often require a 4-Point inspection of the roof, wiring, plumbing, and air conditioning, and a roof past 15 years draws its own scrutiny, regardless of your new quartz counters, so do the unglamorous systems before the kitchen. And check the ceiling: a $150,000 renovation in a neighborhood of $400,000 homes does not come back as $150,000 of value. Renovate for the house you will live in, not the appraisal you hope for.

If you are weighing a move: price the whole ledger, not just the rate. In my example the rate gap costs about $1,088 a month. Against that, count the Save Our Homes benefit you can carry, the insurance difference between a 20-year-old roof and a newer home, the renovation you will not have to live through, and the fact that 1,396 price cuts in a week means the house you would buy is negotiable too. Start with a real number for your current home from my home value estimator, then have the payment conversation with actual quotes, not the rate you remember from 2021.

If you are a buyer: lock-in is quietly working for you. In my experience the sellers listing now are more often the ones who need to, and 54.5% of active listings have already come down from their original price at least once. Look hard at listings past 60 days, where the seller has met the market, and ask for closing cost credits or a rate buydown rather than only a lower price. The payment is the number that actually limits you, so negotiate on the payment.

If you are an investor: owner renovation is both a comp problem and a pipeline. Owner-occupants spending on kitchens raise the finish bar for flips in established neighborhoods, so budget your rehabs up. Harvard's Joint Center for Housing Studies, in its July 23 remodeling outlook, projects $519 billion in homeowner improvement and repair spending through mid-2027, but expects growth to slow to 0.5% and says spending likely stays at that pace until home sales rebound. JCHS ties that slowdown to low home sales, so lock-in is not producing a national remodeling boom. But lock-in also means the dated, never-updated house increasingly reaches the market through estates and tired landlords, which is exactly the acquisition pipeline a patient local investor wants.

7. Frequently Asked Questions

What is the mortgage rate lock-in effect?

It is the gap between the rate homeowners have and the rate they would get if they moved. Per FHFA National Mortgage Database figures for the second quarter of 2026, 49.1% of outstanding US mortgages carry a rate under 4%, while Freddie Mac put the 30-year fixed at 7.28% on October 1, 2026. Selling means trading a payment built on the old rate for one built on the new rate, so many owners stay put. Federal Reserve Governor Michael Barr said in September that lock-in reduces both demand and supply.

Is the lock-in effect getting better or worse in 2026?

Both, depending on which side you measure. The pool of low-rate loans keeps shrinking: the share under 4% fell to 49.1% in mid-2026 from 65.2% in early 2022. But the market rate rose from 6.06% in mid-January to 7.28% on October 1, so for owners who still hold a low rate, the cost of moving went up. In my example, a typical move-up went from about $810 a month more in January to about $1,088 more now.

Can I keep my 3% mortgage if I move under the MOVE Act?

Not today. The MOVE Act, H.R. 10028, was introduced in the House on August 3, 2026 and would require Fannie Mae and Freddie Mac to purchase portable mortgages. As of October 1, 2026 it has not moved past introduction. It is worth watching, but no one can port a mortgage under it, and I would not build a moving plan around a bill that has not passed either chamber.

Can I take my Florida property tax savings with me when I move?

Partly. Save Our Homes portability lets a homesteaded owner transfer up to $500,000 of the difference between their home's market value and its capped assessed value to a new Florida homestead, established within three years of January 1 of the year they left the old one. That softens the tax reset on a move-up, but the new home's higher value is still taxed, so the bill usually rises. Ask your county property appraiser for a portability estimate before you decide you are stuck.

Is it better to renovate or sell in Central Florida right now?

Run both ledgers before deciding. Renovating keeps a low rate and your Save Our Homes cap, though improvements that add value, like an addition, can raise your assessed value, and a major remodel brings permits, insurance scrutiny on older systems, and months of disruption, and it will not add a bedroom the lot cannot fit. Selling costs you the rate gap, about $1,088 a month on a typical move-up in my estimate, but you can carry up to $500,000 of your Save Our Homes assessment difference to a new homestead, a newer house can cost less to insure, and more than half of active listings have already cut their price. The right answer depends on your rate, your equity, and what the house cannot become.

Orange County

589 price cuts in the last 7 days. Median asking price $429,900.

Browse Price Reductions

Seminole County

214 price cuts in the last 7 days. Median asking price $389,900.

Browse Price Reductions

Lake County

306 price cuts in the last 7 days. Median asking price $389,900.

Browse Price Reductions

Volusia County

287 price cuts in the last 7 days. Median asking price $368,900.

Browse Price Reductions

For the broader picture, my Central Florida market hub tracks inventory, cuts, and days on market weekly. If you are on the buying side of the rate jump, my breakdown of what September's move past 7% cost a Central Florida buyer runs the numbers, and my builder incentives breakdown covers the other way around the rate gap, the buydown.

Stuck between the renovation and the sign in the yard?

Send me your address and your current rate. I will pull what your home would actually list for, your Save Our Homes portability estimate, and the real payment on the move you are considering, side by side with the renovation you are pricing, so you are deciding with the whole ledger instead of the rate alone. Call or text 407-616-9019 or start with the home value estimator.

Brenden Rendo, Realtor, The Homes In Orlando Team. 890 Northern Way, Suite D-1, Winter Springs, FL 32708.

Oct. 6, 2026

Living in Casselberry, FL: Who It Fits, and Who Should Look Elsewhere

Casselberry is the entry point to the Seminole County school district for a house buyer who wants to stay close to Orlando. The typical one is a 1,700 square foot house from around 1980, it closes near $400,000, and it is under contract in 19 days. Almost nothing new is being built, six homes in a year, so what a buyer gets is an older house, often near one of the city's lakes, and usually a fast decision.

$325,000
Median Sale Price
August 2026, 48 closed sales
29,473
Population
U.S. Census ACS 2023, up 5.4% since 2019
114
Active Listings
Active residential listings in the city, October 9, 2026
26.7 min
Mean Commute
Against 30.4 minutes from Winter Springs

Who Casselberry Fits, and Who It Doesn't

Strong fit: first-time and move-up buyers who want Seminole County schools at an entry price, because the 165 homes built before 1980 closed at a median of $325,000 and the 1980s and 1990s tier at $360,000; buyers who can move fast, since the median house went under contract in 19 days and Summerset North, Carriage Hill and Seminole Sites sold in five to eight; anyone who wants a lake nearby without a lakefront premium, because the 36 waterfront sales closed at $411,500, barely above the typical house; and buyers who do not want an association, with 164 no-HOA sales at $358,500.

Weaker fit: buyers who want new construction, because there is effectively none; anyone who wants a larger or newer house, since most of the homes built since 2000 are in Legacy Park, Lost Lake Estates and Oakhurst Reserve, and they close from about $460,000 to $490,000; condo buyers who need a quick resale, because the 51 condos that sold took a median of 61 days to go under contract at $155,000; and anyone looking for a downtown, because Casselberry is organized around 17-92 and State Road 436 rather than a center.

Still deciding between towns? We pulled the closed sales around a $400,000 budget and put Casselberry side by side with its neighbors: what $400,000 actually buys in each. Square footage, bedrooms, year built, and how many came with a pool.

Where Is Casselberry, and What Makes It Different?

Casselberry sits in south Seminole County between Altamonte Springs and Winter Springs, along 17-92 and State Road 436, with Red Bug Lake Road on its southeast side and lakes scattered through its neighborhoods. Most of it was built between the 1960s and the 1990s and little land has been left since. The mean commute is 26.7 minutes, about the same as Altamonte Springs and shorter than Winter Springs.

Casselberry Housing Market Snapshot (2026)

Over the last twelve months 419 homes sold in Casselberry at a median of $360,000, up 5.0% against the twelve months before. In August 2026, 48 homes closed at a median of $325,000 and the typical one went under contract in 13 days. One month is too small a sample to read a direction from, which is why the twelve-month figure leads here. There are 114 active residential listings as of October 9, 2026, with a median asking price of $287,200, or $214 per square foot.

Wondering whether it is a buyer's or seller's market around Casselberry? We publish that answer for Seminole County as a whole, from current MLS data: Is Seminole County a buyer's or seller's market?

Best Neighborhoods in Casselberry, FL: Communities to Know

Casselberry prices by decade, and a handful of communities carry most of the sales.

  • The 1960s and 1970s neighborhoods, where the entry price is: Camelot closed 15 at $387,000, Carriage Hill 9 at $396,000 in 7 days, Summerset North 9 at $329,900 in 8 days, Seminole Sites 7 at $310,000 in 5 days and Queens Mirror South 8 at about $300,000
  • Deer Run and Sterling Park, the two largest communities by sales, both with an association and a mix of houses and townhomes: Deer Run closed 33 at $335,000 and Sterling Park 28 at about $363,000, each in under four weeks
  • Legacy Park, Lost Lake Estates and Oakhurst Reserve, the homes built since 2000 and the top of the market: Legacy Park closed 32 across its sections at about $480,000, townhomes included, Lost Lake Estates 9 at $475,000 and Oakhurst Reserve 10 at $462,500 in about two weeks
  • Townhomes and condos, 57 townhomes at $282,500, with Summerhill at $275,000, and 51 condos at $155,000, with Summit Village and Cabana Key both at that figure; the townhomes sell at nearly the pace of the houses and the condos take about two months

If the budget is under $375,000, shop the 1960s and 1970s neighborhoods and expect to compete. If it is $460,000 and up, three communities hold most of what was built this century.

The 15 communities in Casselberry where the most homes have sold over the last twelve months, each with its own page:

Another 58 Casselberry communities have their own page too. You can also browse every Casselberry listing in one place.

Casselberry vs. Winter Springs vs. Altamonte Springs: The Honest Comparison

 CasselberryWinter SpringsAltamonte Springs
Median asking price$287,200$392,450$195,000
Median $/sq ft$214$237$175
Mean commute26.7 minutes30.4 minutes26.8 minutes
Median household income$57,816$86,332$64,106
Population29,47338,44845,657

Winter Springs is the neighbor to the north and the step up: a higher household income, Tuscawilla at the top, a median single-family sale of $475,000 and a longer commute. Altamonte Springs is the neighbor to the west, with five times the condo sales and a median single-family sale of $420,000. Casselberry is the one of the three with the lowest price for a single-family house and the fewest moving parts: mostly houses, mostly older, mostly under contract in three weeks. The asking medians in the table mix condos with houses, which is why Altamonte Springs shows a lower number there.

Schools, Commute, and Day-to-Day Life

Seminole County Public Schools serves the city, and assignment varies by address rather than by city name, so confirm the zoning for the specific property before you buy on a school reputation.

Mean travel time to work is 26.7 minutes, against 30.4 from Winter Springs.

Is Casselberry, FL Safe?

Casselberry's reported violent crime rate is 342.2 per 100,000 residents against 280.8 for Florida as a whole, so it runs above the state figure, and the context matters more than the number. Rates are calculated against resident population while the offense count includes everyone passing through, so a town that draws more workers, shoppers or visitors each day than it has residents will read higher than its residents' own risk.

Figures are reported offenses from the FBI Crime Data Explorer for the Casselberry Police Department (ORI FL0590200), 2023, the most recent year that agency reported in a usable form. Reporting years differ between agencies, so this is compared to the Florida rate for the same year and is not comparable to another town's page.

Cost of Living in Casselberry, FL

Housing is the line that moves a Central Florida budget. Casselberry's median asking price is $287,200 against a median household income of $57,816, which puts a home at about 4.97 times household income here. That ratio, rather than the sticker price, is the number worth carrying between towns, and it is why a cheaper town is not automatically a more affordable one.

Florida charges no state income tax, so the property tax line matters more here than it would elsewhere, and a homestead exemption reduces the taxable value of a primary residence. Millage varies by taxing district, so treat any single quoted rate as an estimate until the specific parcel is checked.

Frequently Asked Questions

Is Casselberry, FL a good place to live?

Start with the numbers. Against the 60 places this site tracks across Orange, Seminole, Lake and Volusia counties, the median asking price of $287,200 is lower than most and the mean commute of 26.7 minutes is shorter than most. The median household income here is $57,816, which puts housing at 4.97 times income, a lighter load than in most of those places. On local incomes, that makes buying here easier than in most of the group. Who it fits, and who it does not, is laid out at the top of this page.

What is the median home price in Casselberry, FL?

The median sale price was $325,000 in August 2026 across 48 closed sales. Over the last twelve months 419 homes sold at a median of $360,000, up 5.0% against the twelve months before. The median asking price across 114 active listings is $287,200, or $214 per square foot.

Is Casselberry cheaper than Winter Springs?

On the asking median, yes: $287,200 against $392,450. Measured against household income, Casselberry is at 4.97 times income and Winter Springs at 4.55, so on that basis Winter Springs is the more affordable of the two. See what $400,000 buys in each town.

Is Casselberry, FL safe?

The reported violent crime rate runs above the Florida average, though city rates are measured against resident population while the offense count includes everyone passing through.

What is the cost of living in Casselberry, FL?

Housing is the deciding line. A median asking price of $287,200 against a median household income of $57,816 puts a home at roughly 4.97 times income, and Florida charges no state income tax, which shifts weight onto the property tax line.

What school district serves Casselberry, FL?

Seminole County Public Schools. Assignment varies by address within the city, so confirm the zoning for the specific property.

Thinking About a Move to Casselberry?

I work these four counties every week and I will tell you when a town is wrong for you. If you want the numbers for your budget before you tour anything, start with what $400,000 buys across Casselberry and its neighbors, or call me at 407-616-9019.

You can also browse homes for sale in Casselberry, which updates with current inventory.

Oct. 5, 2026

Living in Longwood, FL: Who It Fits, and Who Should Look Elsewhere

Longwood is the Seminole County suburb for people who want a house and the ground it sits on. Five of every six sales here are single-family homes, the median one is a 2,200 square foot house from the late 1970s, and it goes under contract in 23 days. A tenth of the market sits on an acre or more and closes near $900,000. And the Longwood address covers two different places: the 32750 zip that holds the city itself, where the median house closed at $425,000, and the unincorporated Wekiva and Markham Woods side in 32779, west of I-4, where it closed at $650,000.

$500,000
Median Sale Price
August 2026, 57 closed sales
15,952
Population
U.S. Census ACS 2023, up 6.8% since 2019
185
Active Listings
Active residential listings in the city, October 9, 2026
27.0 min
Mean Commute
Against 24.6 minutes from Lake Mary

Who Longwood Fits, and Who It Doesn't

Strong fit: families who want a 1970s or 1980s house with real square footage in the Seminole County school district, because that is nearly the whole market and it sells near $515,000; buyers who want land, since 81 homes on an acre or more closed at a median of $892,000, nine in ten of them on the 32779 side; anyone who wants the Wekiva side, where Sweetwater Oaks closed 66 at $652,500 and went under contract in 15 days and the Wekiva Hunt Club Fox Hunt sections sold in one to two weeks; and buyers who do not want an association, because 233 homes with no HOA closed at about $410,000.

Weaker fit: buyers who want new construction, because about a dozen new homes closed in a year; anyone who wants a condo or townhome market with choice, since the two together are about 110 sales and most are 1980s communities; buyers under about $350,000 who want a house, who will be looking at the oldest and smallest plats, the original Longwood plat, Longwood Park and Sky Lark, and not much else; and anyone who assumes a Longwood address means the City of Longwood, because more than half of the sales with that address were in 32779, which is unincorporated county with different services and a different tax bill.

Still deciding between towns? We pulled the closed sales around a $500,000 budget and put Longwood side by side with its neighbors: what $500,000 actually buys in each. Square footage, bedrooms, year built, and how many came with a pool.

Where Is Longwood, and What Makes It Different?

Longwood sits in south-central Seminole County along I-4 between Altamonte Springs and Lake Mary, with State Road 434 as its main street, a small historic district and a SunRail station. The mailing address reaches well west of the interstate into the Wekiva and Sweetwater neighborhoods, which are unincorporated county. The mean commute is 27.0 minutes, a little longer than Lake Mary and shorter than Winter Springs.

Longwood Housing Market Snapshot (2026)

Over the last twelve months 747 homes sold in Longwood at a median of $479,900, up 3.2% against the twelve months before. Per square foot, which strips out any change in the size of what sold, the figure rose 1.7%. In August 2026, 57 homes closed at a median of $500,000 and the typical one went under contract in 27 days. One month is too small a sample to read a direction from, which is why the twelve-month figure leads here. There are 185 active residential listings as of October 9, 2026, with a median asking price of $450,000, or $240 per square foot.

Wondering whether it is a buyer's or seller's market around Longwood? We publish that answer for Seminole County as a whole, from current MLS data: Is Seminole County a buyer's or seller's market?

New Construction and Resale Are Not the Same Market

Every price figure quoted for Longwood mixes brand new homes with existing ones. Split apart, the last twelve months looked like this.

What soldMedian, prior 12 monthsMedian, last 12 monthsChangeSales
New construction$490,000$565,000+15.3%11
Existing homes (resale)$465,000$475,000+2.1%736
All sales combined$465,000$479,900+3.2%747

Both halves moved the same way here, so the combined figure is a fair summary of Longwood, which is not true everywhere.

Best Neighborhoods in Longwood, FL: Communities to Know

Longwood splits by zip code, and the two are different products at different prices.

  • 32779: Sweetwater Oaks, Wekiva and Markham Woods, the unincorporated side west of I-4 and the more expensive one, with a median house at $650,000: Sweetwater Oaks closed 66 at $652,500 in 15 days, Wekiva Hills 19 at $489,000 and the Wekiva Hunt Club Fox Hunt sections at $415,000 to $469,450; the gated top tier, Alaqua Lakes and Sweetwater Club, closed 33 at about $1.2 million
  • 32750: the city and the 1970s subdivisions, the less expensive side, with a median house at $425,000: Sanlando Springs closed 29 at $470,000, Woodlands 18 at $449,750 in 9 days and Winsor Manor 11 at $434,500 in 10 days
  • The oldest plats, the smallest and least expensive houses: the original Longwood plat near the SunRail station closed 13 at $290,000 with a 1964 median build year, Longwood Park 10 at $334,000 and Sky Lark 9 at $342,000
  • The acreage and the lakes, 81 homes on an acre or more at a median of $892,000 on about 3,400 square feet, nearly all in 32779, and 44 waterfront sales at $720,000
  • Townhomes and condos, 54 townhomes at $324,500, with Governors Point and Danbury Mill near $300,000 to $310,000, and 57 condos at $185,000; Springwood Village closed 9 at $136,000

Decide which zip you are shopping before you compare prices. The same search shows a 1,000 square foot house near the old downtown and a 3,400 square foot house on an acre west of I-4, and the school zone, the services and the tax bill change with the address.

The 15 communities in Longwood where the most homes have sold over the last twelve months, each with its own page:

Another 114 Longwood communities have their own page too. You can also browse every Longwood listing in one place.

Longwood vs. Lake Mary vs. Winter Springs: The Honest Comparison

 LongwoodLake MaryWinter Springs
Median asking price$450,000$482,499$392,450
Median $/sq ft$240$242$237
Mean commute27.0 minutes24.6 minutes30.4 minutes
Median household income$77,214$116,944$86,332
Population15,95216,72438,448

Lake Mary is the town to the north with the higher household income, the corporate offices and the shorter commute; its median single-family sale closed at $585,000 on a house built in the 1990s, against the late 1970s here. Winter Springs is the comparison to the east, with Tuscawilla as its top tier, a median single-family sale of $475,000 and a longer commute. Longwood is the one of the three where the lot is the reason to buy.

Schools, Commute, and Day-to-Day Life

Seminole County Public Schools serves the city, and assignment varies by address rather than by city name, so confirm the zoning for the specific property before you buy on a school reputation.

Mean travel time to work is 27.0 minutes, against 24.6 from Lake Mary.

Is Longwood, FL Safe?

Longwood's reported violent crime rate is 198.6 per 100,000 residents against 280.8 for Florida as a whole, about 29% below the state figure. That is a real difference and it is one of the things buyers here are paying for. The same caveat applies in reverse though: rates are measured against resident population, so a town that few people commute into will tend to look better than a comparable one that they do.

Figures are reported offenses from the FBI Crime Data Explorer for the Longwood Police Department (ORI FL0590300), 2023, the most recent year that agency reported in a usable form. Reporting years differ between agencies, so this is compared to the Florida rate for the same year and is not comparable to another town's page.

Cost of Living in Longwood, FL

Housing is the line that moves a Central Florida budget. Longwood's median asking price is $450,000 against a median household income of $77,214, which puts a home at about 5.83 times household income here. That ratio, rather than the sticker price, is the number worth carrying between towns, and it is why a cheaper town is not automatically a more affordable one.

Florida charges no state income tax, so the property tax line matters more here than it would elsewhere, and a homestead exemption reduces the taxable value of a primary residence. Millage varies by taxing district, so treat any single quoted rate as an estimate until the specific parcel is checked.

Frequently Asked Questions

Is Longwood, FL a good place to live?

It depends on whether your income comes with you. Against the 60 places this site tracks across Orange, Seminole, Lake and Volusia counties, the median asking price of $450,000 is higher than most and the mean commute of 27.0 minutes is near the middle. The median household income here is $77,214, which puts housing at 5.83 times income, a heavier load than in most of those places. For remote workers and retirees who bring their income with them, that matters less. For someone earning a local wage, it is one of the harder places in the group to buy. Who it fits, and who it does not, is laid out at the top of this page.

What is the median home price in Longwood, FL?

The median sale price was $500,000 in August 2026 across 57 closed sales. Over the last twelve months 747 homes sold at a median of $479,900, up 3.2% against the twelve months before. The median asking price across 185 active listings is $450,000, or $240 per square foot.

Is Longwood cheaper than Lake Mary?

On the asking median, yes: $450,000 against $482,499. Measured against household income, Longwood is at 5.83 times income and Lake Mary at 4.13, so on that basis Lake Mary is the more affordable of the two. See what $500,000 buys in each town.

Is Longwood, FL safe?

The reported violent crime rate runs about 29% below the Florida average, though city rates are measured against resident population while the offense count includes everyone passing through.

What is the cost of living in Longwood, FL?

Housing is the deciding line. A median asking price of $450,000 against a median household income of $77,214 puts a home at roughly 5.83 times income, and Florida charges no state income tax, which shifts weight onto the property tax line.

What school district serves Longwood, FL?

Seminole County Public Schools. Assignment varies by address within the city, so confirm the zoning for the specific property.

Thinking About a Move to Longwood?

I work these four counties every week and I will tell you when a town is wrong for you. If you want the numbers for your budget before you tour anything, start with what $500,000 buys across Longwood and its neighbors, or call me at 407-616-9019.

You can also browse homes for sale in Longwood, which updates with current inventory.

Oct. 4, 2026

Living in Altamonte Springs, FL: Who It Fits, and Who Should Look Elsewhere

Altamonte Springs is two markets that barely touch. Four in ten homes that sell here are condos, most of them built in the 1970s and 1980s, and they close at about $160,000 after eleven weeks on the market. Just over half are single-family houses from the 1960s and 1970s that close at $420,000 and go under contract in 25 days. The citywide median falls between the two, too high for a condo and far too low for a house, so this page prices them separately.

$324,500
Median Sale Price
August 2026, 48 closed sales
45,657
Population
U.S. Census ACS 2023, up 4.2% since 2019
301
Active Listings
Active residential listings in the city, October 9, 2026
26.8 min
Mean Commute
Against 26.7 minutes from Casselberry

Who Altamonte Springs Fits, and Who It Doesn't

Strong fit: buyers who want a Seminole County house inside the beltway for less than Longwood or Lake Mary, because the 1970s neighborhoods here closed at about $430,000, Spring Oaks on 34 sales and Sanlando on 26, and went under contract in three to four weeks; condo buyers who want a low entry price to ownership near I-4, since 264 condos closed at a median of $159,750 and the smallest units at Cranes Roost traded near $80,000; anyone who wants Uptown Altamonte, the mall, the hospital and the SunRail station within a short drive; and buyers who do not want an association, because the 240 homes that sold with no HOA were mostly the older houses and went under contract in 27 days.

Weaker fit: anyone who wants new construction, because 18 new homes closed here in a year at a median near $930,000, ten of them in one subdivision, Eden Preserve; condo buyers who expect a quick resale, since condos took a median of 78 days to go under contract against 25 for houses, and an older Florida condo building now comes with reserve and special-assessment questions a buyer has to ask; buyers who want a quiet town with a main street, because this is a commercial corridor city built around State Road 436 and I-4; and anyone who reads the city median as a house price, because the median house closed at $420,000 and the median condo under $160,000, and the citywide figure describes neither.

Still deciding between towns? We pulled the closed sales around a $425,000 budget and put Altamonte Springs side by side with its neighbors: what $425,000 actually buys in each. Square footage, bedrooms, year built, and how many came with a pool.

Where Is Altamonte Springs, and What Makes It Different?

Altamonte Springs sits in south Seminole County where I-4 crosses State Road 436, between Maitland and Longwood, with Cranes Roost Park and Uptown Altamonte at its center and a SunRail station on its east side. It is one of the county's main retail and office centers, and much of its condo stock went up in the 1970s and 1980s alongside the offices and the mall. The mean commute is 26.8 minutes, close to both of the towns compared here.

Altamonte Springs Housing Market Snapshot (2026)

Over the last twelve months 676 homes sold in Altamonte Springs at a median of $305,000, down 3.2% against the twelve months before. In August 2026, 48 homes closed at a median of $324,500 and the typical one went under contract in 47 days. One month is too small a sample to read a direction from, which is why the twelve-month figure leads here. There are 301 active residential listings as of October 9, 2026, with a median asking price of $195,000, or $175 per square foot.

Is Altamonte Springs a buyer's or seller's market right now? We answer that from current MLS data, weighing months of supply and how close sellers get to their original asking price against the four counties: Is Altamonte Springs a buyer's or seller's market?

Best Neighborhoods in Altamonte Springs, FL: Communities to Know

Altamonte Springs divides by building type before it divides by location.

  • The 1960s and 1970s house neighborhoods, Spring Oaks, Sanlando, Weathersfield and their neighbors: 336 homes built before 1980 closed at a median of $350,000; Spring Oaks closed 34 at $429,500 and Sanlando 26 at $431,750, each in three to four weeks, while Weathersfield's smaller houses closed 17 at $345,000
  • The upper tier, Spring Valley Farms and Spring Lake Hills, the top of the resale market: Spring Valley Farms closed 15 at $711,000 on about 3,000 square feet and went under contract in 5 days, and Spring Lake Hills 12 at $695,000
  • The condo buildings, 264 closings at a median of $159,750: Hidden Springs closed 23 at $168,000, Lakewood Park 14 at $127,000, Destiny Springs 12 at $122,500, and the 496 square foot units at Waterside at Cranes Roost 13 at $80,000 after more than three months on the market
  • Townhomes, the middle step, 57 closings at $271,350 that went under contract in about five weeks, mostly 1980s communities
  • New construction, 18 closings at a median of $929,995 on about 3,000 square feet, ten of them in Eden Preserve near $970,000

Filter by property type first. A search that mixes the two shows an average that neither a condo buyer nor a house buyer can use.

The 15 communities in Altamonte Springs where the most homes have sold over the last twelve months, each with its own page:

Another 98 Altamonte Springs communities have their own page too. You can also browse every Altamonte Springs listing in one place.

Altamonte Springs vs. Casselberry vs. Longwood: The Honest Comparison

 Altamonte SpringsCasselberryLongwood
Median asking price$195,000$287,200$450,000
Median $/sq ft$175$214$240
Mean commute26.8 minutes26.7 minutes27.0 minutes
Median household income$64,106$57,816$77,214
Population45,65729,47315,952

Casselberry is the neighbor to the east, with housing of a similar age, a fifth as many condo sales and a median single-family sale about $20,000 lower. Longwood is the step up to the north: larger houses, a higher household income, a median single-family sale near $515,000 and a small condo market. Altamonte Springs is the one of the three where a buyer can still own for under $160,000, and the one where the house and the condo should never be averaged. The asking medians in the table mix condos with houses, which is why Altamonte Springs looks so much cheaper there than it is for a house buyer.

Schools, Commute, and Day-to-Day Life

Seminole County Public Schools serves the city, and assignment varies by address rather than by city name, so confirm the zoning for the specific property before you buy on a school reputation.

Mean travel time to work is 26.8 minutes, against 26.7 from Casselberry.

Is Altamonte Springs, FL Safe?

Altamonte Springs' reported violent crime rate is 331.7 per 100,000 residents against 280.8 for Florida as a whole, so it runs above the state figure, and the context matters more than the number. Rates are calculated against resident population while the offense count includes everyone passing through, so a town that draws more workers, shoppers or visitors each day than it has residents will read higher than its residents' own risk.

Figures are reported offenses from the FBI Crime Data Explorer for the Altamonte Springs Police Department (ORI FL0590100), 2023, the most recent year that agency reported in a usable form. Reporting years differ between agencies, so this is compared to the Florida rate for the same year and is not comparable to another town's page.

Cost of Living in Altamonte Springs, FL

Housing is the line that moves a Central Florida budget. Altamonte Springs' median asking price is $195,000 against a median household income of $64,106, which puts a home at about 3.04 times household income here. That ratio, rather than the sticker price, is the number worth carrying between towns, and it is why a cheaper town is not automatically a more affordable one.

Florida charges no state income tax, so the property tax line matters more here than it would elsewhere, and a homestead exemption reduces the taxable value of a primary residence. Millage varies by taxing district, so treat any single quoted rate as an estimate until the specific parcel is checked.

Frequently Asked Questions

Is Altamonte Springs, FL a good place to live?

Start with the numbers. Against the 60 places this site tracks across Orange, Seminole, Lake and Volusia counties, the median asking price of $195,000 is lower than most and the mean commute of 26.8 minutes is shorter than most. The median household income here is $64,106, which puts housing at 3.04 times income, a lighter load than in most of those places. On local incomes, that makes buying here easier than in most of the group. Who it fits, and who it does not, is laid out at the top of this page.

What is the median home price in Altamonte Springs, FL?

The median sale price was $324,500 in August 2026 across 48 closed sales. Over the last twelve months 676 homes sold at a median of $305,000, down 3.2% against the twelve months before. The median asking price across 301 active listings is $195,000, or $175 per square foot.

Is Altamonte Springs cheaper than Casselberry?

On the asking median, yes: $195,000 against $287,200. Measured against household income, Altamonte Springs is at 3.04 times income and Casselberry at 4.97, so on that basis Altamonte Springs is the more affordable of the two. See what $425,000 buys in each town.

Is Altamonte Springs, FL safe?

The reported violent crime rate runs above the Florida average, though city rates are measured against resident population while the offense count includes everyone passing through.

What is the cost of living in Altamonte Springs, FL?

Housing is the deciding line. A median asking price of $195,000 against a median household income of $64,106 puts a home at roughly 3.04 times income, and Florida charges no state income tax, which shifts weight onto the property tax line.

What school district serves Altamonte Springs, FL?

Seminole County Public Schools. Assignment varies by address within the city, so confirm the zoning for the specific property.

Thinking About a Move to Altamonte Springs?

I work these four counties every week and I will tell you when a town is wrong for you. If you want the numbers for your budget before you tour anything, start with what $425,000 buys across Altamonte Springs and its neighbors, or call me at 407-616-9019.

You can also browse homes for sale in Altamonte Springs, which updates with current inventory.

Oct. 2, 2026

Living in Maitland, FL: Who It Fits, and Who Should Look Elsewhere

Maitland's median price is a poor guide to what a house here costs. A quarter of what closes here is condos at about $235,000, and they pull the headline down to a number that describes neither the condo nor the house. The single-family median is $595,000, and on the Orange County side, where the 1960s lake streets are, it is $725,000. This page starts by separating those, because a buyer who walks in with the portal's number is well short of a typical Orange-side house.

$549,990
Median Sale Price
August 2026, 31 closed sales
19,268
Population
U.S. Census ACS 2023, up 8.5% since 2019
88
Active Listings
Active residential listings in the city, October 9, 2026
22.2 min
Mean Commute
Against 23.8 minutes from Winter Park

Who Maitland Fits, and Who It Doesn't

Strong fit: buyers who want Winter Park's lake neighborhoods and 1960s houses at a price Winter Park no longer offers, because Dommerich Estates and Highland Park Estates closed at about $612,000 to $772,000 in about three weeks; anyone whose commute runs on I-4 or Maitland Boulevard, since the mean commute here is among the shortest of any town on this list; buyers who want the Seminole County schools with a Maitland address, because the Seminole side closed 87 houses at $508,000, $217,000 under the Orange side; and condo buyers who want the zip code without the house price, with 82 closings at $235,000 and the lakefront Moorings at $525,000.

Weaker fit: anyone who wants new construction, because only a handful of new homes close here in a year and there is no subdivision being built; buyers who want a large modern house, since the median house here was built in 1968 and is about 2,060 square feet, and the ones over $800,000 are mostly the same era; buyers who read the city median as a house budget, because at that number the choice is a Seminole-side house or an Orange-side condo, not a typical Orange-side house; and anyone who needs inventory to choose from, because this is one of the thinnest markets in this series and a typical house goes under contract in about three weeks.

Still deciding between towns? We pulled the closed sales around a $725,000 budget and put Maitland side by side with its neighbors: what $725,000 actually buys in each. Square footage, bedrooms, year built, and how many came with a pool.

Maitland sits across two counties and they price differently, so there are two of these. The Seminole County side runs closer to $500,000: what $500,000 buys on that side.

Where Is Maitland, and What Makes It Different?

Maitland sits directly north of Winter Park on the chain of lakes, split between Orange and Seminole counties, with I-4 and Maitland Boulevard on its west side and 17-92 running through it. The old town is the 1950s and 1960s streets around Lake Maitland, Lake Sybelia and Lake Minnehaha; the north edge past the county line is Seminole and the same era at a lower price. The mean commute is 22.2 minutes, among the shortest on this list, because downtown Orlando is a short run down I-4 and the Maitland Center offices are inside the city. With almost no new houses being built, there are few homes for sale here at any one time.

Maitland Housing Market Snapshot (2026)

Over the last twelve months 353 homes sold in Maitland at a median of $515,000, up 5.1% against the twelve months before. In August 2026, 31 homes closed at a median of $549,990 and the typical one went under contract in 24 days. One month is too small a sample to read a direction from, which is why the twelve-month figure leads here. There are 88 active residential listings as of October 9, 2026, with a median asking price of $434,950, or $259 per square foot.

Wondering whether it is a buyer's or seller's market around Maitland? We publish that answer for Orange County as a whole, from current MLS data: Is Orange County a buyer's or seller's market?

Best Neighborhoods in Maitland, FL: Communities to Know

Maitland divides by county line first and by product second, and the county line runs through the middle of it.

  • The Orange County lake streets: Dommerich Estates, Highland Park Estates and the Lake Maitland and Lake Sybelia shores, the top of the market: Orange-side houses closed at $725,000 and $322 per square foot with a 1967 median build year; Dommerich Estates closed 16 at $772,000 in a median of 21 days and Highland Park Estates 10 at $612,400 in 15, and the 69 sales over $800,000 citywide ran at $996,000
  • The Seminole County side: English Estates, Northgate and the streets north of the line, the same era at a lower price: 87 houses at $508,000 and $272 per square foot; English Estates closed 19 at $509,000 to $525,000 in about three and a half weeks and Northgate 7 at $515,000 in about three, and these carry the Seminole County school assignment
  • The 1990s and 2000s pockets: Winfield, the Enclave at Maitland and Druid Hills Park, the small newer-build slice: Winfield closed 9 at $415,000, the Enclave townhomes 10 at $437,500, and Druid Hills Park 7 at $385,000, which is where a buyer under $450,000 finds a house here
  • The condos, a quarter of the market: 82 closings at $235,000 in 42 days; Lake Maitland Terrace at $245,000 on 816 square feet, the Visconti buildings at $194,500 to $220,000, and the lakefront Moorings on Lake Maitland at $525,000, the most expensive square footage in the city at $412 per foot

Know which county the address is in before you look at the price. The same 1965 house is worth about $215,000 more south of the line than north of it, and the schools change with it.

The 15 communities in Maitland where the most homes have sold over the last twelve months, each with its own page:

Another 75 Maitland communities have their own page too. You can also browse every Maitland listing in one place.

Maitland vs. Winter Park vs. Longwood: The Honest Comparison

 MaitlandWinter ParkLongwood
Median asking price$434,950$649,900$450,000
Median $/sq ft$259$353$240
Mean commute22.2 minutes23.8 minutes27.0 minutes
Median household income$93,318$98,076$77,214
Population19,26829,92915,952

Winter Park is the reference point for everything here: a higher asking median, a higher price per square foot, and the downtown Maitland does not have, and the Orange-side lake streets are the closest thing to Winter Park a buyer can get without paying for the name. Longwood is the other direction, further up I-4 with a similar asking median, a lower income and a longer commute. Maitland is the one of the three with the shortest commute and the thinnest inventory.

Schools, Commute, and Day-to-Day Life

Orange County Public Schools (Seminole County Public Schools on the Seminole side) serves the city, and assignment varies by address rather than by city name, so confirm the zoning for the specific property before you buy on a school reputation.

Mean travel time to work is 22.2 minutes, against 23.8 from Winter Park.

Is Maitland, FL Safe?

Maitland's reported violent crime rate is 238.2 per 100,000 residents against 280.8 for Florida as a whole, about 15% below the state figure. That is a real difference and it is one of the things buyers here are paying for. The same caveat applies in reverse though: rates are measured against resident population, so a town that few people commute into will tend to look better than a comparable one that they do.

Figures are reported offenses from the FBI Crime Data Explorer for the Maitland Police Department (ORI FL0480200), 2023, the most recent year that agency reported in a usable form. Reporting years differ between agencies, so this is compared to the Florida rate for the same year and is not comparable to another town's page.

Cost of Living in Maitland, FL

Housing is the line that moves a Central Florida budget. Maitland's median asking price is $434,950 against a median household income of $93,318, which puts a home at about 4.66 times household income here. That ratio, rather than the sticker price, is the number worth carrying between towns, and it is why a cheaper town is not automatically a more affordable one.

Florida charges no state income tax, so the property tax line matters more here than it would elsewhere, and a homestead exemption reduces the taxable value of a primary residence. Millage varies by taxing district, so treat any single quoted rate as an estimate until the specific parcel is checked.

Frequently Asked Questions

Is Maitland, FL a good place to live?

Start with the numbers. Against the 60 places this site tracks across Orange, Seminole, Lake and Volusia counties, the median asking price of $434,950 is higher than most and the mean commute of 22.2 minutes is shorter than most. The median household income here is $93,318, which puts housing at 4.66 times income, a lighter load than in most of those places. On local incomes, that makes buying here easier than in most of the group. Who it fits, and who it does not, is laid out at the top of this page.

What is the median home price in Maitland, FL?

The median sale price was $549,990 in August 2026 across 31 closed sales. Over the last twelve months 353 homes sold at a median of $515,000, up 5.1% against the twelve months before. The median asking price across 88 active listings is $434,950, or $259 per square foot.

Is Maitland cheaper than Winter Park?

On the asking median, yes: $434,950 against $649,900. Measured against household income, Maitland is at 4.66 times income and Winter Park at 6.63, so on that basis Maitland is the more affordable of the two. See what $725,000 buys in each town.

Is Maitland, FL safe?

The reported violent crime rate runs about 15% below the Florida average, though city rates are measured against resident population while the offense count includes everyone passing through.

What is the cost of living in Maitland, FL?

Housing is the deciding line. A median asking price of $434,950 against a median household income of $93,318 puts a home at roughly 4.66 times income, and Florida charges no state income tax, which shifts weight onto the property tax line.

What school district serves Maitland, FL?

Orange County Public Schools (Seminole County Public Schools on the Seminole side). Assignment varies by address within the city, so confirm the zoning for the specific property.

Thinking About a Move to Maitland?

I work these four counties every week and I will tell you when a town is wrong for you. If you want the numbers for your budget before you tour anything, start with what $725,000 buys across Maitland and its neighbors, or call me at 407-616-9019.

You can also browse homes for sale in Maitland, which updates with current inventory.